
Q1 FY27 highlights: record $253.8M originations and FY27 guidance upgrade
In its Q1 FY27 market update for the period ending 30 September 2026, Wisr recorded loan originations of $253.8M, up 73% on Q1 FY26 ($146.8M). The company upgraded its FY27 Cash NPAT guidance to at least $7.0M, previously at least $5.0M, a 40% lift.
The loan book reached $1,211.0M, up 40% on Sep-25 ($867.6M), while revenue rose 32% to $33.1M (Q1 FY26 $25.0M). Q1 FY27 financial metrics and performance are unaudited.
Management said the expected improvement in FY27 Cash NPAT will be driven by continued loan origination and loan book growth, operating leverage, disciplined cost management and productivity gains from investments in automation and technology.
Wisr also expects Cash NPAT to grow substantially in FY28 as the business benefits from increased scale and further operating leverage. The company holds $97.9M in carried-forward tax losses to support strong cash generation as taxable profits are achieved.
The upgraded FY27 target builds on Wisr’s first full-year Cash NPAT profit of $1.0M in FY26, which reversed a $5.3M loss in FY25 and came with all four guidance metrics exceeded.
Guidance will be reviewed and updated in accordance with Wisr’s continuous disclosure obligations.
Andrew Goodwin, Chief Executive Officer
“The record quarter and 40% FY27 Cash NPAT guidance upgrade (at least $7M, previously $5M) are testament to effective business execution since returning to growth… putting the business on a $1B+ annual run-rate and driving continued operational leverage.”
When big ASX news breaks, our subscribers know first
Lending performance: growth with improving credit quality
Originations by product
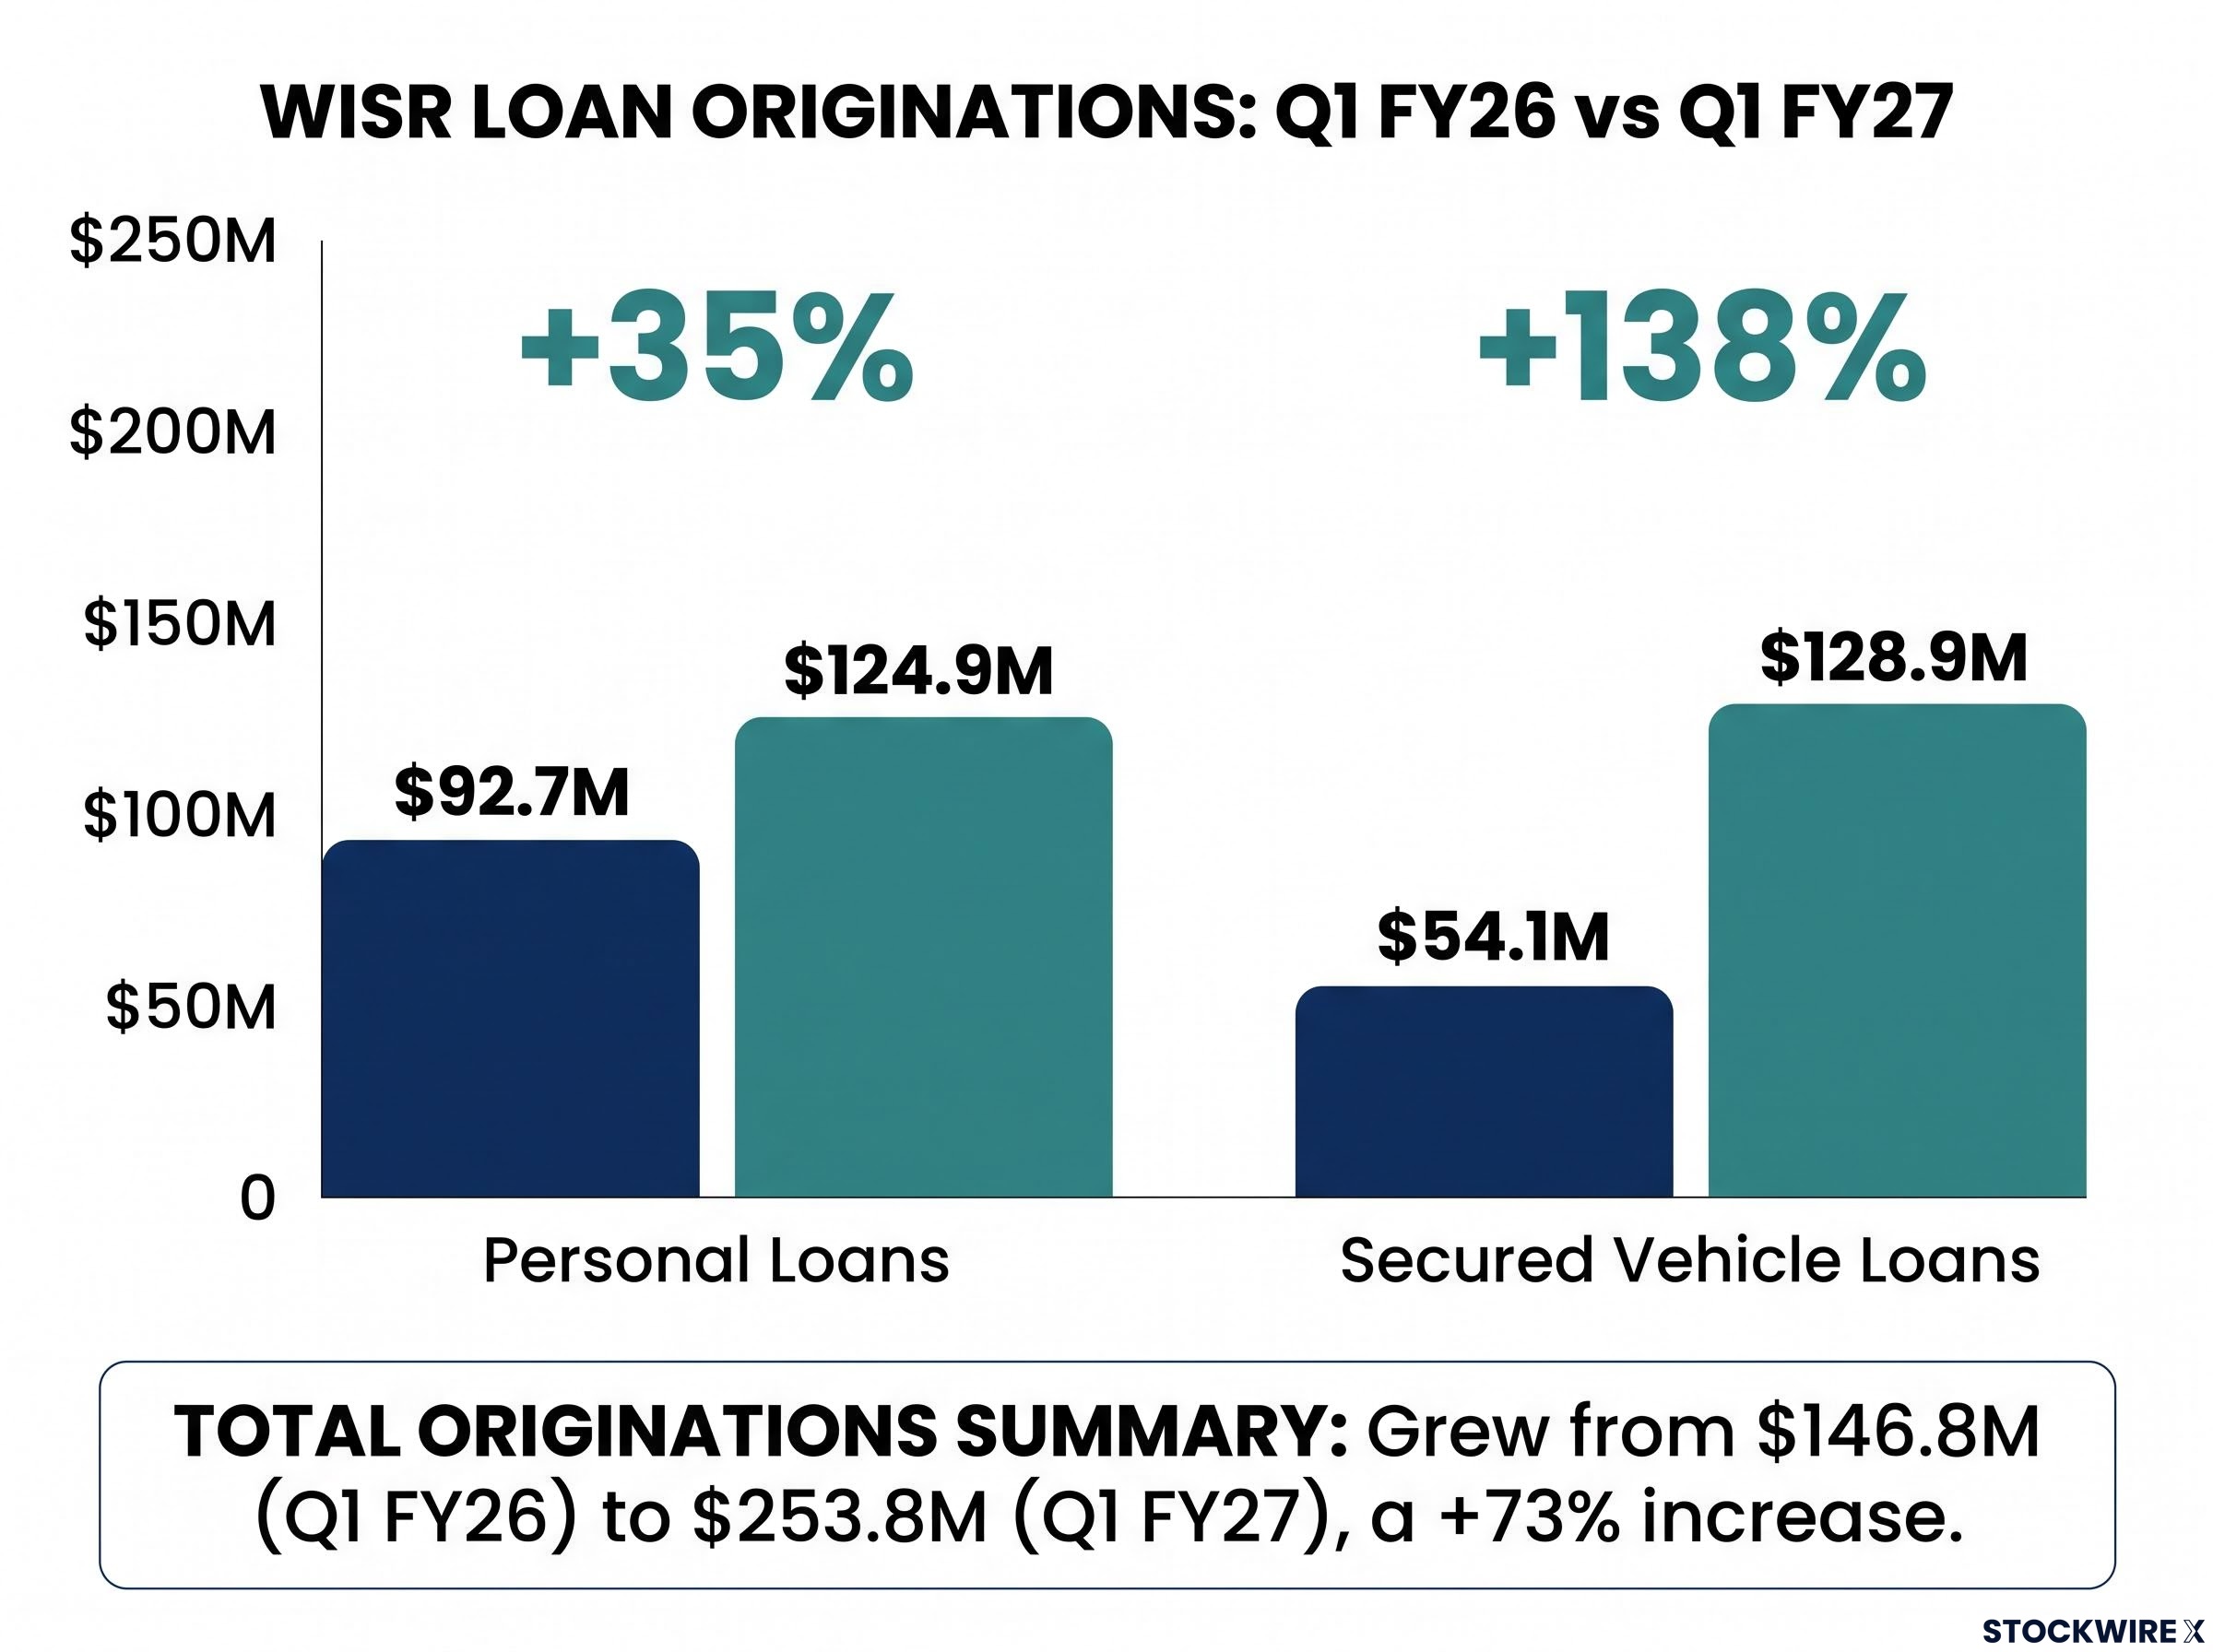
Both product lines grew strongly against the prior corresponding quarter, with secured vehicle loans more than doubling. Secured vehicle loan originations now slightly exceed personal loan originations.
| Metric | Q1 FY27 | Q1 FY26 | Change |
| Personal loan originations | $124.9M | $92.7M | +35% |
| Secured vehicle loan originations | $128.9M | $54.1M | +138% |
| Total loan originations | $253.8M | $146.8M | +73% |
Originations were also up 28% on Q4 FY26 ($198.1M), and the closing loan book was up 12% on Jun-26 ($1,084.0M).
The loan book first crossed the $1 billion mark in Q3 FY26, and the growth since then has come alongside falling arrears, with secured vehicle lending the fastest-growing product line.
Credit quality
The loan book scaled while arrears and net losses declined:
- 90+ day arrears of 0.86% (Sep-25 1.14%; Jun-26 1.01%)
- Net losses of 1.19% (Q1 FY26 1.63%; Q4 FY26 1.30%)
- Average credit score of 802 (Sep-25 807; Jun-26 807)
The average credit score eased slightly from both comparison dates, though Wisr described it as remaining strong. Management said growth was achieved alongside continued improvement in credit performance.
Financial results and margins
Revenue of $33.1M was up 10% on Q4 FY26 ($30.0M), driven by loan book growth. Portfolio yield was stable at 11.03% (Q4 FY26 11.00%; Q1 FY26 11.14%), as front book pricing increases implemented in Q1 FY27 offset the mix shift towards secured vehicle loans, which carry lower yields, funding costs and credit losses.
Net Interest Margin (NIM) decreased to 4.90%, down 21 bps on Q4 FY26 and 36 bps on Q1 FY26, reflecting the shift in portfolio mix during the quarter.
Risk-adjusted margin (RAM) was stable at 3.71%, as the improvement in net losses largely offset NIM compression.
| Metric | Q1 FY27 | Q4 FY26 | Q1 FY26 |
| Portfolio yield | 11.03% | 11.00% | 11.14% |
| NIM | 4.90% | 5.11% | 5.26% |
| RAM | 3.71% | 3.81% | 3.64% |
What are NIM and RAM, and why do they matter for a lender?
Net Interest Margin (NIM) measures the difference between the interest a lender earns on loans and what it pays to fund them, expressed as a percentage of the loan book. A lower NIM means a thinner spread between income and funding costs.
Risk-adjusted margin (RAM) takes NIM and then accounts for credit losses, showing what is left after loans that go unpaid. Wisr said secured vehicle loans carry lower yields, funding costs and credit losses, and that the lower loss profile helped RAM hold steady despite NIM compression.
Funding, liquidity and customer momentum
Wisr reported the following capital position at the end of the quarter:
- Three warehouse facilities with total commitments of $887M (Jun-26 $887M) and $165M of undrawn capacity
- $30.0M drawn from the $50.0M corporate facility, with $20.0M undrawn ($7.5M committed and $12.5M uncommitted capacity)
- Unrestricted cash of $13.0M, which together with the undrawn corporate facility provides total liquidity of $33.0M to support growth
On the customer side, Wisr recorded a customer Net Promoter Score of +80 and a broker Net Promoter Score of +81. It was also awarded WeMoney’s Innovation of the Year – Debt Reduction for DebtBustr, which lets users compare credit card and loan repayments against a Wisr debt consolidation loan.
Targeted AI and automation initiatives during the quarter included:
- Product expansion: simplified assessment for eligible personal loans
- Faster loans: integration of vehicle inspections and automated customer ID checks
- Customer self-service: an increase in AI service agent tasks, reducing cost to service
Looking ahead, Wisr now expects FY27 Cash NPAT of at least $7.0M and expects Cash NPAT to grow substantially in FY28.
Don’t Miss the Next Fintech Winner
Join 20,000+ investors getting FREE breaking ASX news in their inbox within minutes of release, complete with in-depth analysis. Click the “Free Alerts” button at Big News Blast to hear about market-moving financials and fintech announcements the moment they break, and stay ahead of the market.