

2Q27 highlights: Plenti records $613m in loan originations and grows portfolio to $3.5bn
In its 2Q27 update for the quarter ended 30 September 2026, Plenti Group Limited recorded quarterly loan originations of $613m, up 29% on the prior corresponding period (PCP) and up 14% on the prior quarter.
It was the first time Plenti surpassed $600m in quarterly loan originations, achieving the FY27 exit run-rate objective in 2Q27. Quarterly loan origination records were achieved in three verticals.
The loan portfolio increased to $3.5bn, up 24% on PCP and up 7% on the prior quarter. Revenue reached $89.7m, up 18% on PCP.
Key figures from the quarter:
- Loan originations of $613m, up 29% on PCP
- Loan portfolio of $3.5bn, up 24% on PCP
- Revenue of $89.7m, up 18% on PCP
- Annualised net credit losses of 96bps, compared with 94bps in PCP
- 90+ day arrears of 42bps at quarter end, down from 46bps at the end of the prior quarter
- NAB powered by Plenti (NPBP) loan portfolio of $186m, up 22% on the prior quarter
Adam Bennett, Chief Executive Officer
“Surpassing $600m in quarterly loan originations for the first time is a significant milestone for Plenti. This continues our path to a $5bn portfolio and is a result of our scalable platform and diversified business…”
For investors, the result pairs growth with stable credit metrics, on the path to a $5bn portfolio referenced by management.
Originations and portfolio trend
The five-quarter trend shows originations rising from $475m in 2Q26 to $613m in 2Q27, while the portfolio grew from $2,832m to $3,521m.
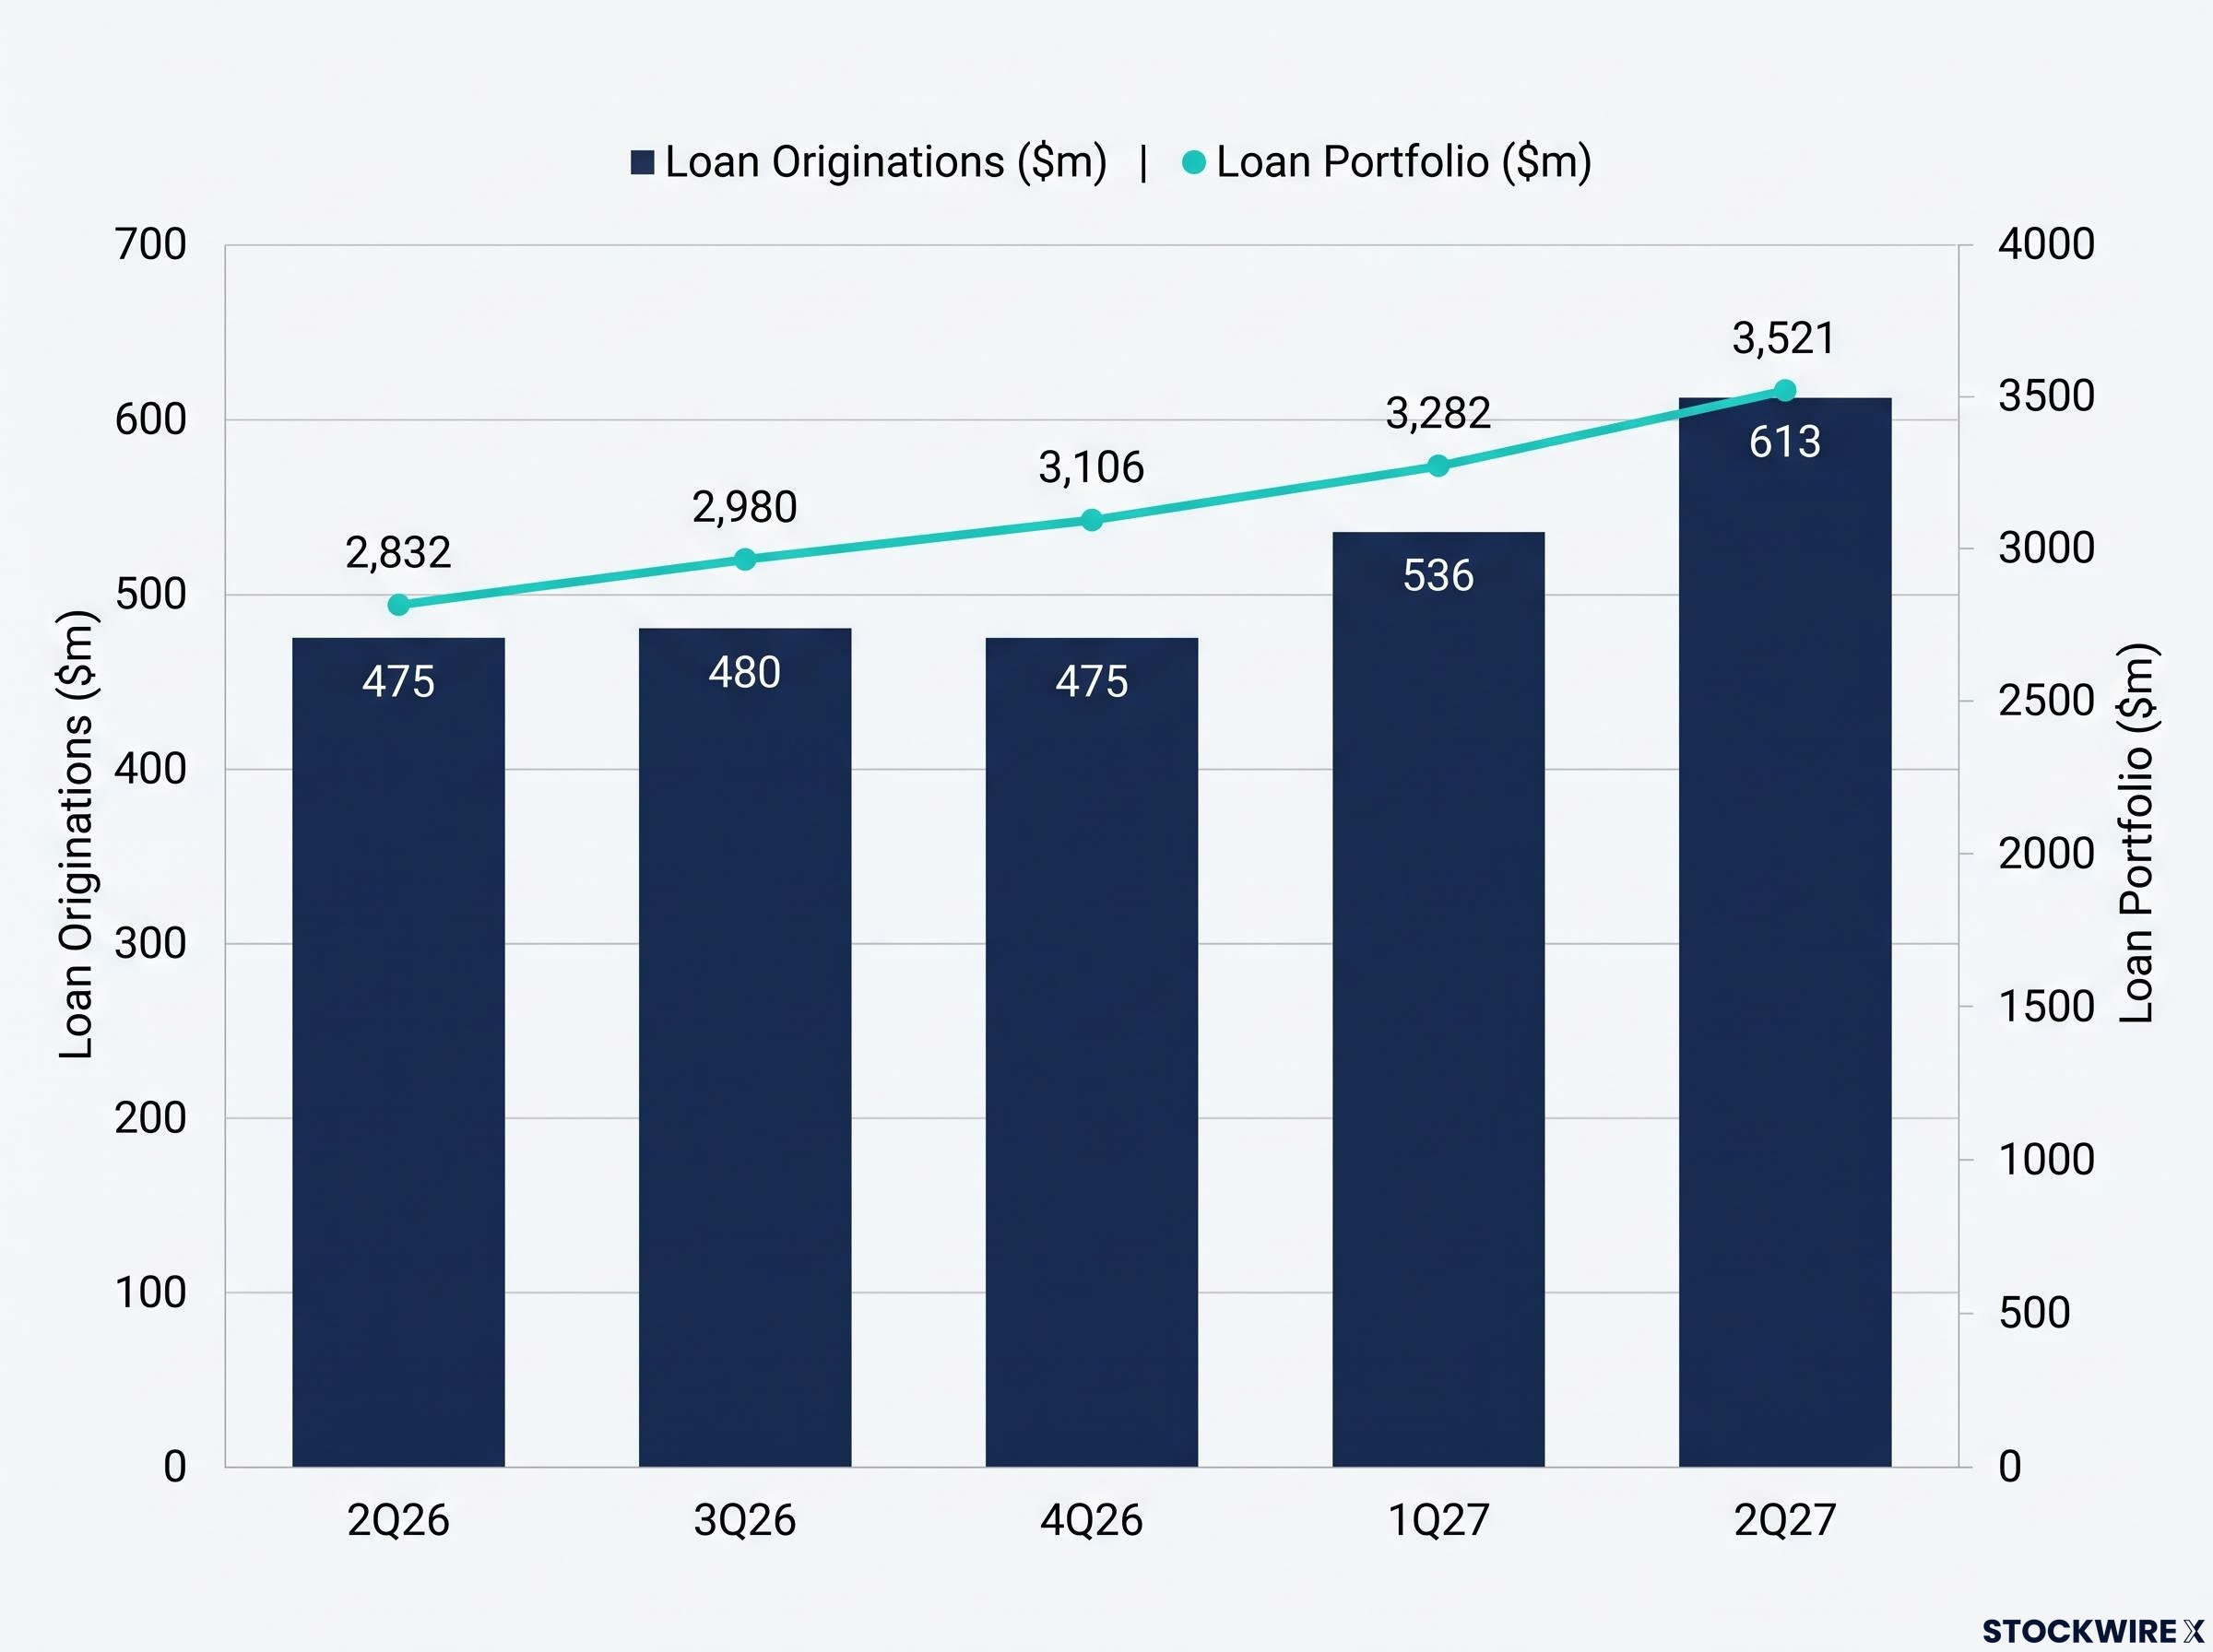
The step up to $613m builds on the record $536m quarter reported for 1Q27, when originations rose 13% on the prior quarter and records were set simultaneously across automotive, renewable energy and personal lending.
| Metric | 2Q26 | 3Q26 | 4Q26 | 1Q27 | 2Q27 |
|---|---|---|---|---|---|
| Loan originations ($m) | 475 | 480 | 475 | 536 | 613 |
| Loan portfolio ($m) | 2,832 | 2,980 | 3,106 | 3,282 | 3,521 |
| Revenue ($m) | 76.3 | 79.9 | 82.8 | 84.6 | 89.7 |
When big ASX news breaks, our subscribers know first
Performance by vertical: renewable energy more than doubles
Renewable energy originations more than doubled on PCP, supported by Federal and State Government battery programs. The table below sets out each vertical’s 2Q27 originations and portfolio.
| Vertical | 2Q27 originations ($m) | VPCP% | VPQ% | 2Q27 portfolio ($m) |
|---|---|---|---|---|
| Consumer automotive | 180 | 7% | 20% | 1,169 |
| Commercial | 129 | 35% | (1)% | 833 |
| Renewable energy | 117 | 105% | 36% | 539 |
| Personal lending | 186 | 21% | 10% | 979 |
Consumer automotive delivered a record $180m, up 7% on PCP and up 20% on the prior quarter. The NPBP product complemented the result with 10% growth in originations on the prior quarter, and NAB and Plenti launched the renewables referral offering to market in 2Q27.
Commercial originations were $129m, up 35% on PCP and (1)% on the prior quarter. The company described this as a pleasing result after record originations in 1Q27 driven by financial year end.
Renewable energy reached a record $117m, up 105% on PCP and up 36% on the prior quarter. Over 11,300 rebates were processed under the WA Residential Battery Scheme during the quarter, and originations under the NSW Government’s Home Energy Saver program have scaled at a pleasing rate since its June launch.
Personal lending hit a record $186m, up 21% on PCP and up 10% on the prior quarter, underpinned by growth in both the broker and direct channels. The direct channel represented 51% of originations in 2Q27.
Why government-backed renewables matter
Loan originations measure the value of new loans written in a period. The loan portfolio is the total balance of loans on the books, so strong originations feed portfolio growth over time.
Renewable energy loans are one example. Plenti pointed to growing support from Government incentive programs at both the Federal and State level, and the renewable energy portfolio rose to $539m, up 15% on the prior quarter.
Margins, funding costs and credit quality hold steady
The average net interest margin on loan originations held at about 5.3% in 2Q27, in line with 1Q27, as Plenti actively passed higher funding costs through to customer pricing.
In September, the market component of Plenti’s funding costs rose by about 40 basis points, driven by global macroeconomic challenges and a shift in market expectations for RBA rate decisions. Plenti increased customer pricing during September, while still delivering record quarterly originations, and made further pricing changes in October.
The majority of Plenti’s loans are fixed and hedged at origination, so the increase in funding costs has not impacted the back book portfolio. Plenti continues to have one of the lowest funding costs for comparable companies in similar asset classes, as demonstrated by the Auto ABS deal in July and the PL & Renewable ABS deal in October.
The October $450m PL & Renewable ABS priced at a 1.33% weighted average margin with Class A credit support tightening to 18.50%, which supports the view that Plenti’s funding position remains competitive despite higher market costs.
Credit performance for the quarter:
- Annualised net credit losses of 96bps, compared with 98bps in the prior quarter (excluding the impact of the debt sale completed in 1Q27) and 94bps in PCP
- 90+ day arrears of 42bps, down from 46bps in the prior quarter and up from 35bps in PCP
- Weighted average Equifax credit score of 851, stable
- No single exposure greater than $300k
Plenti said this reflects its disciplined approach to credit and continued focus on lending to prime credit customers.
FY27 objectives and what happens next
Costs are well controlled and credit performance continues to be stable. As a result, Plenti remains on track to deliver its remaining profitability and efficiency objectives for the year to 31 March 2027.
The priority FY27 objectives are:
- Growth: build on loan origination growth momentum and exit FY27 having achieved $600m a quarter. The >$600m quarter was delivered in 2Q27
- Profitability: continue to drive meaningful Cash PBT growth
- Efficiency: cost to net margin below 55%
Upcoming and recent events:
- An online investor webcast was scheduled for 9:00am AEDT on 27 October 2026, hosted by Plenti.
- Plenti will report its 1H27 financial results on Wednesday 25 November 2026.
All numbers in the release are preliminary and unaudited.
Stay Ahead on Fintech and Finance News
Get breaking ASX finance announcements delivered FREE within minutes of release, with in-depth analysis already done. Join 20,000+ investors using Big News Blast to stay ahead of the market. Click the “Free Alerts” button to start receiving real-time alerts the moment news breaks.