
September 2026 performance: MEC returns 1.3% as AI sell-off weighs
In its September 2026 monthly report, Morphic Ethical Equities Fund (MEC) reported a net return of +1.3% for the month, against +1.9% for the MSCI All Countries World Daily Total Return Net Index. Over the rolling 12 months, MEC returned +2.3% versus the Index return of +11.2%.
The report linked the weakness to the sell-off in AI stocks, noting that it negatively impacted the portfolio given the Fund’s large weighting to AI related businesses. The three-month figure shows the scale of the drawdown over the quarter.
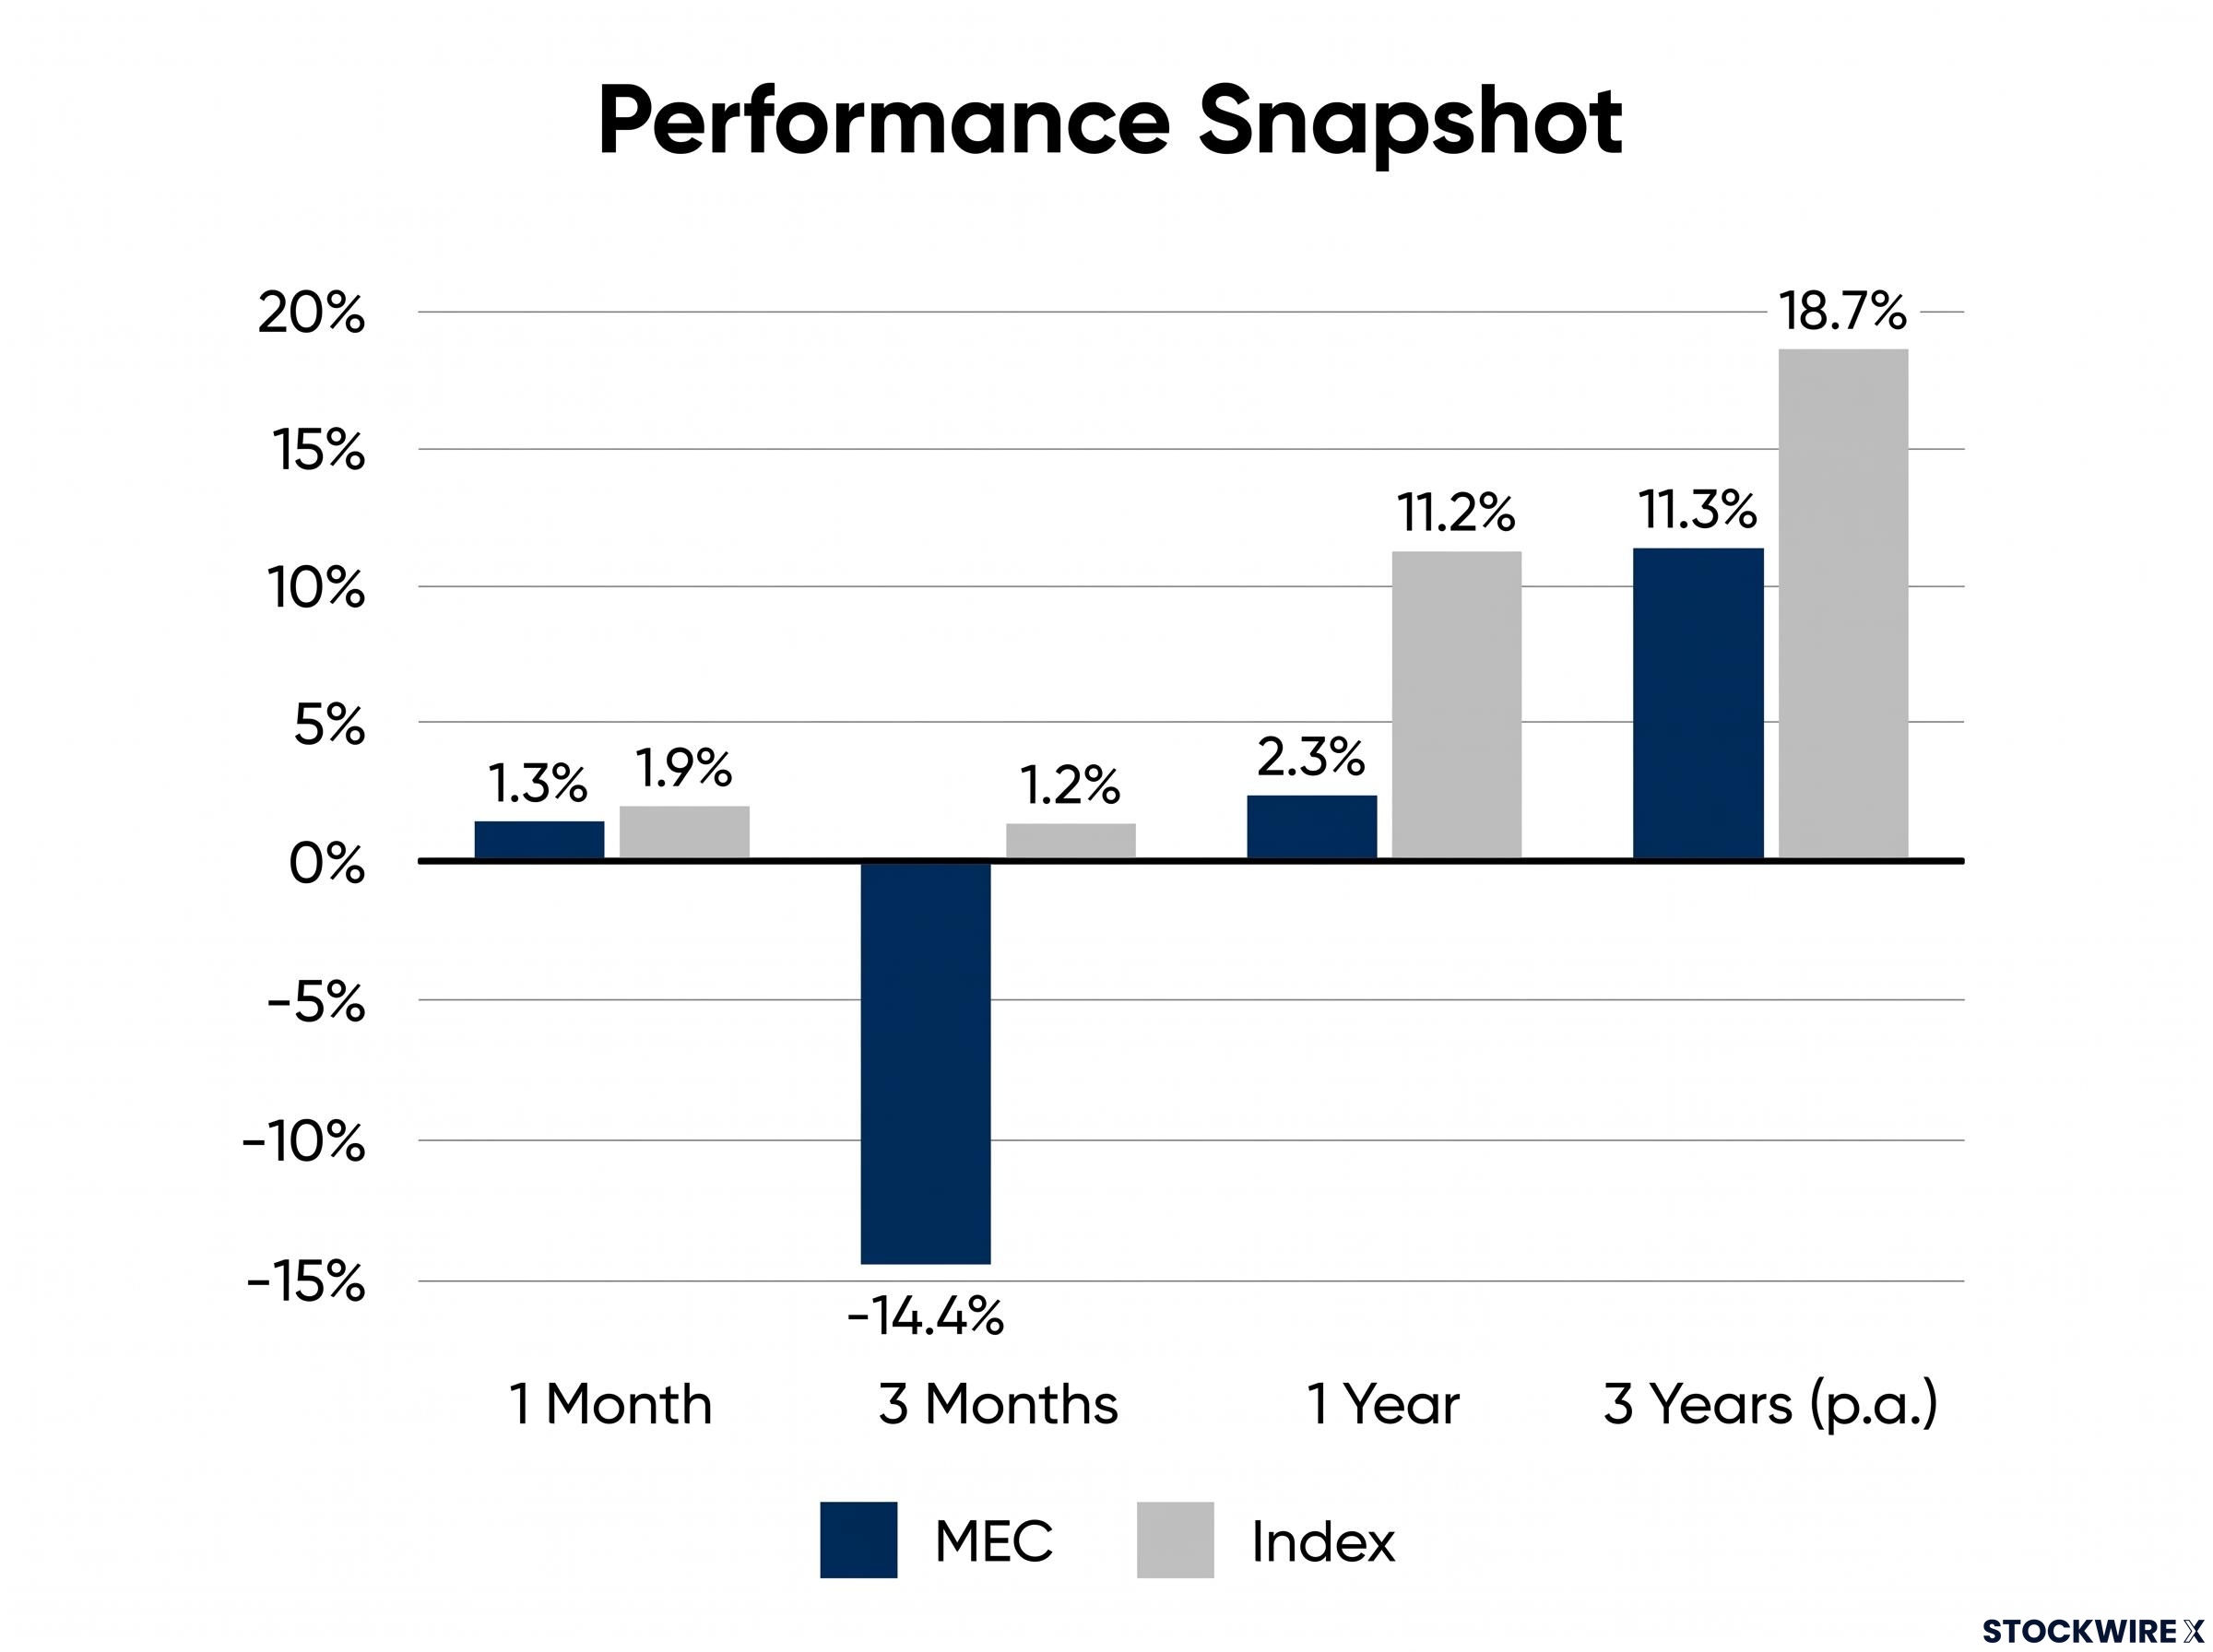
| Period | MEC | Index |
|---|---|---|
| 1 Month | **1.3%** | **1.9%** |
| 3 Months | **-14.4%** | **1.2%** |
| 6 Months | **6.7%** | **15.0%** |
| 1 Year | **2.3%** | **11.2%** |
| 3 Years (p.a.) | **11.3%** | **18.7%** |
| 5 Years (p.a.) | **4.9%** | **12.4%** |
| ITD (p.a.) | **8.2%** | **12.9%** |
Performance is net of investment management fees, before company admin costs and taxes. The Fund listed on the ASX on 3 May 2017, and past performance is not an indication of future performance.
When big ASX news breaks, our subscribers know first
What drove the AI sell-off
The Morgan Stanley Technology Momentum Long Index, described as a proxy for AI stocks, fell 19% through the quarter. The fall was as high as 37% from its June peak to the July trough.
The report described this as the fastest and steepest 30-day tech momentum sell-off in history, surpassing even the dotcom bust. It cited the following catalysts:
- News that Meta was aiming to set up a new cloud business to sell ‘excess’ compute, which the market interpreted as potential ‘oversupply’. The report said this assumption has largely been debunked following Meta’s recent result and rising GPU prices.
- Widening credit spreads of the hyperscalers, as the market questioned the sustainability of their spending commitments and weak free cashflow.
- The release of a Chinese open-source model named ‘Kimi K3’, which achieved near frontier performance on many metrics at lower cost.
- Increasing political scrutiny of data centre development in the US, which raised the possibility of delays to GPU capacity coming online.
- Rapid de-grossing of hedge funds. After quarter end, the rise in US bond yields triggered a further sell down in AI related names on funding fears.
The report said the Kimi K3 release should be considered broadly positive for AI demand, though potentially at the expense of frontier models and their share of AI inference demand.
Why the manager still sees AI fundamentals as constructive
Beyond the weak equity performance and negative headlines, the manager said it continues to see the AI story ‘on the ground’ as constructive. The report pointed to several indicators:
- Token demand: Tokens, the input/output currency of models, continue to grow solidly.
- GPU pricing: Prices continue to rise for both older and newer GPUs, with rental prices accelerating through July and continuing to rise through September and into October, particularly for B200s.
- Model advancements: Recent releases include Meta’s ‘Watermelon’, ‘Muse Wonder Full’ and OpenAI’s ‘Astra’, which all received strong reviews. REA (Reverse Engineer Anything) is now the #1 repository on Github.
- Healthy 2Q results: Hyperscaler cloud revenues are accelerating year on year and quarter on quarter, with margins also increasing.
Financing remained a key market debate. Yields on select unsecured corporate bonds of some neoclouds, including Coreweave, are entering distressed territory.
Outside of this, debt and convertible bond raisings through the quarter were oversubscribed and done at relatively attractive prices. At the end of September, HUT 8 announced a ~$1.1b senior secured revolving credit facility at SOFR +1.75% (~5.65% today), while yield on cost for many data centre developers is now approaching 20% in some cases.
How AI demand flows to ethical-fund holdings
A token is the input/output currency of AI models. Producing one requires a power connection (preferably to the grid), a data centre shell, and GPUs.
The manager said its core AI holdings are largely levered to token demand, not the price of tokens or the success of an individual AI model. If demand for tokens continues at its current rate, the current physical bottlenecks (power, cooling, and data centre capacity) will still take many years to resolve.
The holdings named were AI cloud (NBIS), data centres (CORZ, GLXY, HUT) and other companies levered to AI capital spend (MTZ, FPS, Anritsu, AAOI). The manager said it will continue to review position sizing and adjust for the current market volatility where it thinks appropriate.
Key contributors, detractors and portfolio snapshot
Contributors and detractors
The figures below are for the quarter. Moves for Corpay, GFL Environmental and MasTec are in local terms, while SharonAI’s fall is within the Fund.
| Stock | Move | Contribution to relative performance |
|---|---|---|
| Corpay | **+17%** | **+95bps** |
| GFL Environmental | **nearly +14%** | **+52bps** |
| SharonAI | **-31%** | **-258bps** |
| MasTec | **-49%** | **-192bps** |
Corpay continues to grow EPS at rates above 25% and trades at 14x 2027 earnings. Management continues to target $50 of EPS by 2029.
GFL Environmental is a North American solid waste and environmental services company. In July, management announced the business is potentially exploring a take private transaction, with the CEO willing to entertain north of $50 per share (versus $43 at the time of writing).
SharonAI is an emerging Australian neocloud that fell in sympathy with other neoclouds, despite the rise in GPU contract prices. MasTec fell alongside the AI drawdown and at its 2Q results on the back of a small delay in its communications segment, with EBITDA growth expected to compound at 20% per annum in the coming years.
Fund facts
Key facts from the report include:
- ASX code / share price: MEC / $1.180
- NTA before tax: $1.3520; after tax: $1.2870 (estimated and unaudited)
- Market capitalisation: $35.4m, with 29,980,579 shares outstanding
- Profit reserve: $1.094
- Management fee: 1.25%; performance fee: 15%
- Dividend per share: $0.01
- Net exposure: 91.46%; annualised volatility: 14.08%
North America made up 63.89% of the regional exposure. Top 10 positions, listed alphabetically, include AerCap Holdings NV, Corpay, Nebius Group N.V. and Hut 8 Corp.
MEC seeks to provide investors a way to grow their wealth without investing in businesses that harm the environment, people, and society. Its exclusions cover coal and uranium mining, oil and gas, tobacco, alcohol, armaments and gambling, among other categories.
Don’t Miss the Next Financials Winner Before the Market Moves
Get FREE breaking ASX news delivered to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ investors already using Big News Blast to stay ahead of the market. Click the “Free Alerts” button to start receiving alerts the moment market-moving announcements break.