
3Q26 trading update: NPAT of $36.5m and PCA coverage ratio of 2.01x
In its 3Q26 trading update for the quarter ended 30 September 2026, Helia Group Limited (ASX:HLI) reported statutory net profit after tax (NPAT) of $36.5 million for the quarter and $136.5 million year-to-date (YTD Sep 26), compared with $200.9 million in YTD Sep 25.
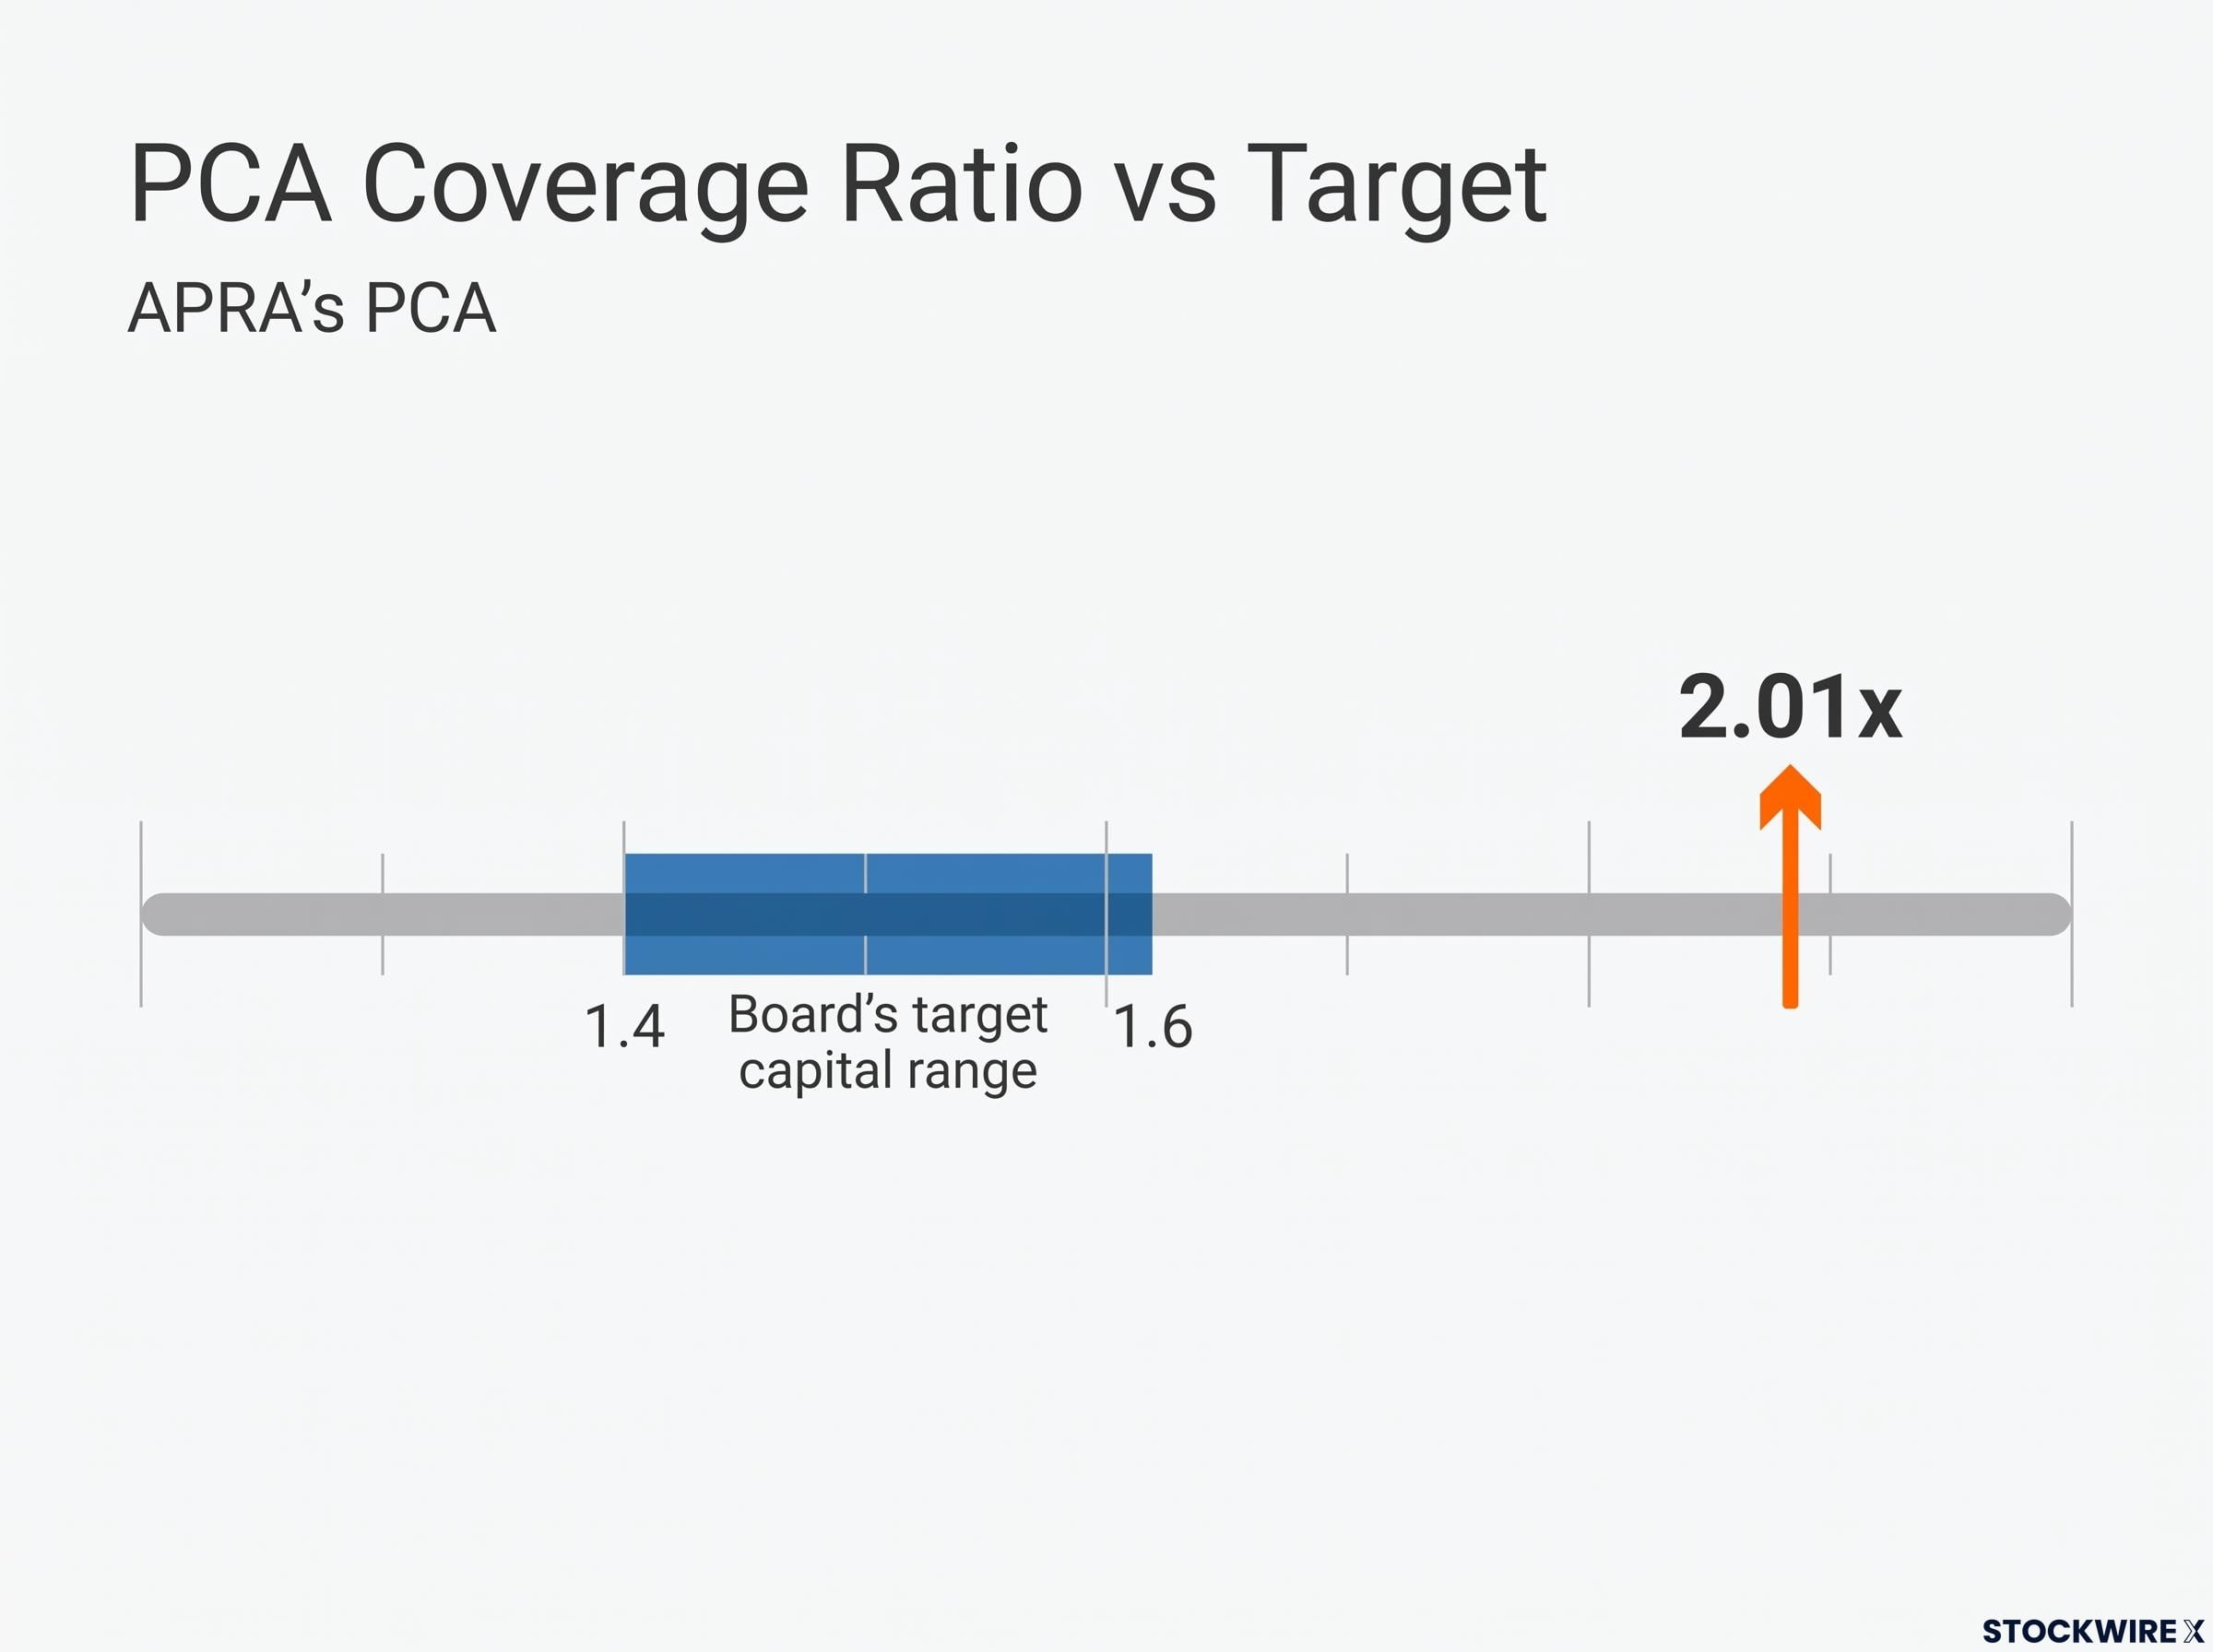
The Prescribed Capital Amount (PCA) coverage ratio stood at 2.01x at 30 September 2026, and FY26 guidance was unchanged.
The figures are extracted from the APRA lodgement for Helia Insurance Pty Ltd, the main operating entity, which is not consolidated, has not been externally reviewed or audited, and does not embrace a full review of claims reserving.
Headline figures from the update:
- NPAT: $36.5 million in 3Q26 and $136.5 million YTD Sep 26
- PCA coverage ratio: 2.01x at 30 September 2026
- 90-day delinquency rate: 0.83%, up four basis points in the quarter
- FY26 insurance revenue guidance: unchanged at $330 million to $360 million
When big ASX news breaks, our subscribers know first
Key results at a glance
Financial snapshot
The table below reproduces the figures from the APRA lodgement extract, with total incurred claims shown as presented in the source.
| Metric ($m) | YTD Sep 25 | YTD Sep 26 | 3Q26 |
|---|---|---|---|
| Gross written premium (GWP) | **176.0** | **82.5** | **20.9** |
| Insurance revenue | **274.9** | **253.4** | **82.8** |
| Total incurred claims | **(54.0)** | **(8.4)** | **5.1** |
| Insurance service result | **242.5** | **186.1** | **52.7** |
| Net investment revenue | **121.3** | **47.2** | **3.5** |
| Net financial result | **68.5** | **23.6** | **4.2** |
| Statutory NPAT | **200.9** | **136.5** | **36.5** |
| PCA coverage ratio | **1.85x** | **2.01x** | **2.01x** |
The PCA coverage ratio shown is below the Helia Group Limited PCA coverage ratio due to the timing of intercompany transactions.
Premium and revenue trends
GWP for the first nine months of the year was lower than the prior corresponding period (pcp). The company attributed this to the loss of the CBA contract, the expansion of the Australian Government’s 5% Deposit Scheme and a slowing in home lending.
Premium pressure from the CBA loss is partly offset by the four-year ING exclusive LMI deal from 1 July 2026, which secures a counterparty that contributed roughly 20% of FY25 gross written premium.
Insurance revenue year-to-date was down 8% on pcp, reflecting lower GWP in recent years.
Claims, housing market conditions and investment returns
The September 2026 quarter saw further slowing in the Australian housing market, including lower property transaction volumes and lower house prices. Helia said these conditions had some impact on its results over the quarter.
Claims performance
Total incurred claims were $5 million in 3Q26, resulting from a modest increase in delinquencies and the impact of declining house prices.
Year-to-date claims were negative $8.4 million, a net release from the incurred claims liability, reflecting continued strong cures and lower levels of new arrears.
The 90-day delinquency rate for the total portfolio increased four basis points during the quarter to 0.83%, which the company said remains relatively low.
Investment performance
Net investment revenue in 3Q26 was lower than pcp, reflecting realised and unrealised losses from higher bond yields and a smaller investment portfolio.
The annualised net investment return was 3.3% for the nine months to 30 September 2026, compared with 4.7% in the prior year period. Net running yield increased 130 basis points on pcp to 5.2%.
How mortgage insurance claims and capital ratios work
Three points help interpret the figures:
- Claims and cures: Lenders mortgage insurance protects lenders if a borrower defaults. Claims are driven by delinquencies (borrowers behind on payments) and cures (borrowers who return to good standing).
- Negative incurred claims: Total incurred claims can be negative, caused by low levels of paid claims and a reduction in reserves. This is what the company described as a net release from the incurred claims liability.
- PCA coverage ratio: The ratio compares capital held with APRA’s prescribed requirement. At 2.01x, it remains well above the Board’s target capital range of 1.4 to 1.6 times APRA’s PCA, as lower capital requirements were partly offset by capital management initiatives.
Capital strength and FY26 guidance
For investors, the update pairs a capital position well above the Board’s target range with claims that remained contained, with year-to-date incurred claims in a net release position.
Unchanged guidance arrives as Helia completes its permanent leadership team, with Craig Ward confirmed as CFO from 1 July 2026 and Mark Senkevics due to take over as CEO by December 2026.
Helia’s FY26 guidance was unchanged:
- Insurance revenue guidance remains at $330 million to $360 million.
- The total incurred claims ratio (total incurred claims divided by insurance revenue) is expected to remain well below through-the-cycle average levels.
Don’t Miss the Next Financials Mover
Join 20,000+ investors getting FREE ASX alerts delivered within minutes of release, with breaking news, in-depth analysis and the full announcement in one email. Click the “Free Alerts” button at Big News Blast to stay ahead of the market on financials and fintech news.