
Peet reaffirms FY27 NPAT growth target with $862m contracts on hand
Peet Limited (ASX: PPC) has reaffirmed that it is targeting net profit after tax (NPAT) growth in FY27, compared with FY26 NPAT of $103m. The outcome is subject to market conditions and settlement timing.
The FY26 base of $103m reflects record FY26 earnings, with net operating profit up 77% and fully franked dividends lifted 68%, which sets a demanding comparison for the FY27 growth target.
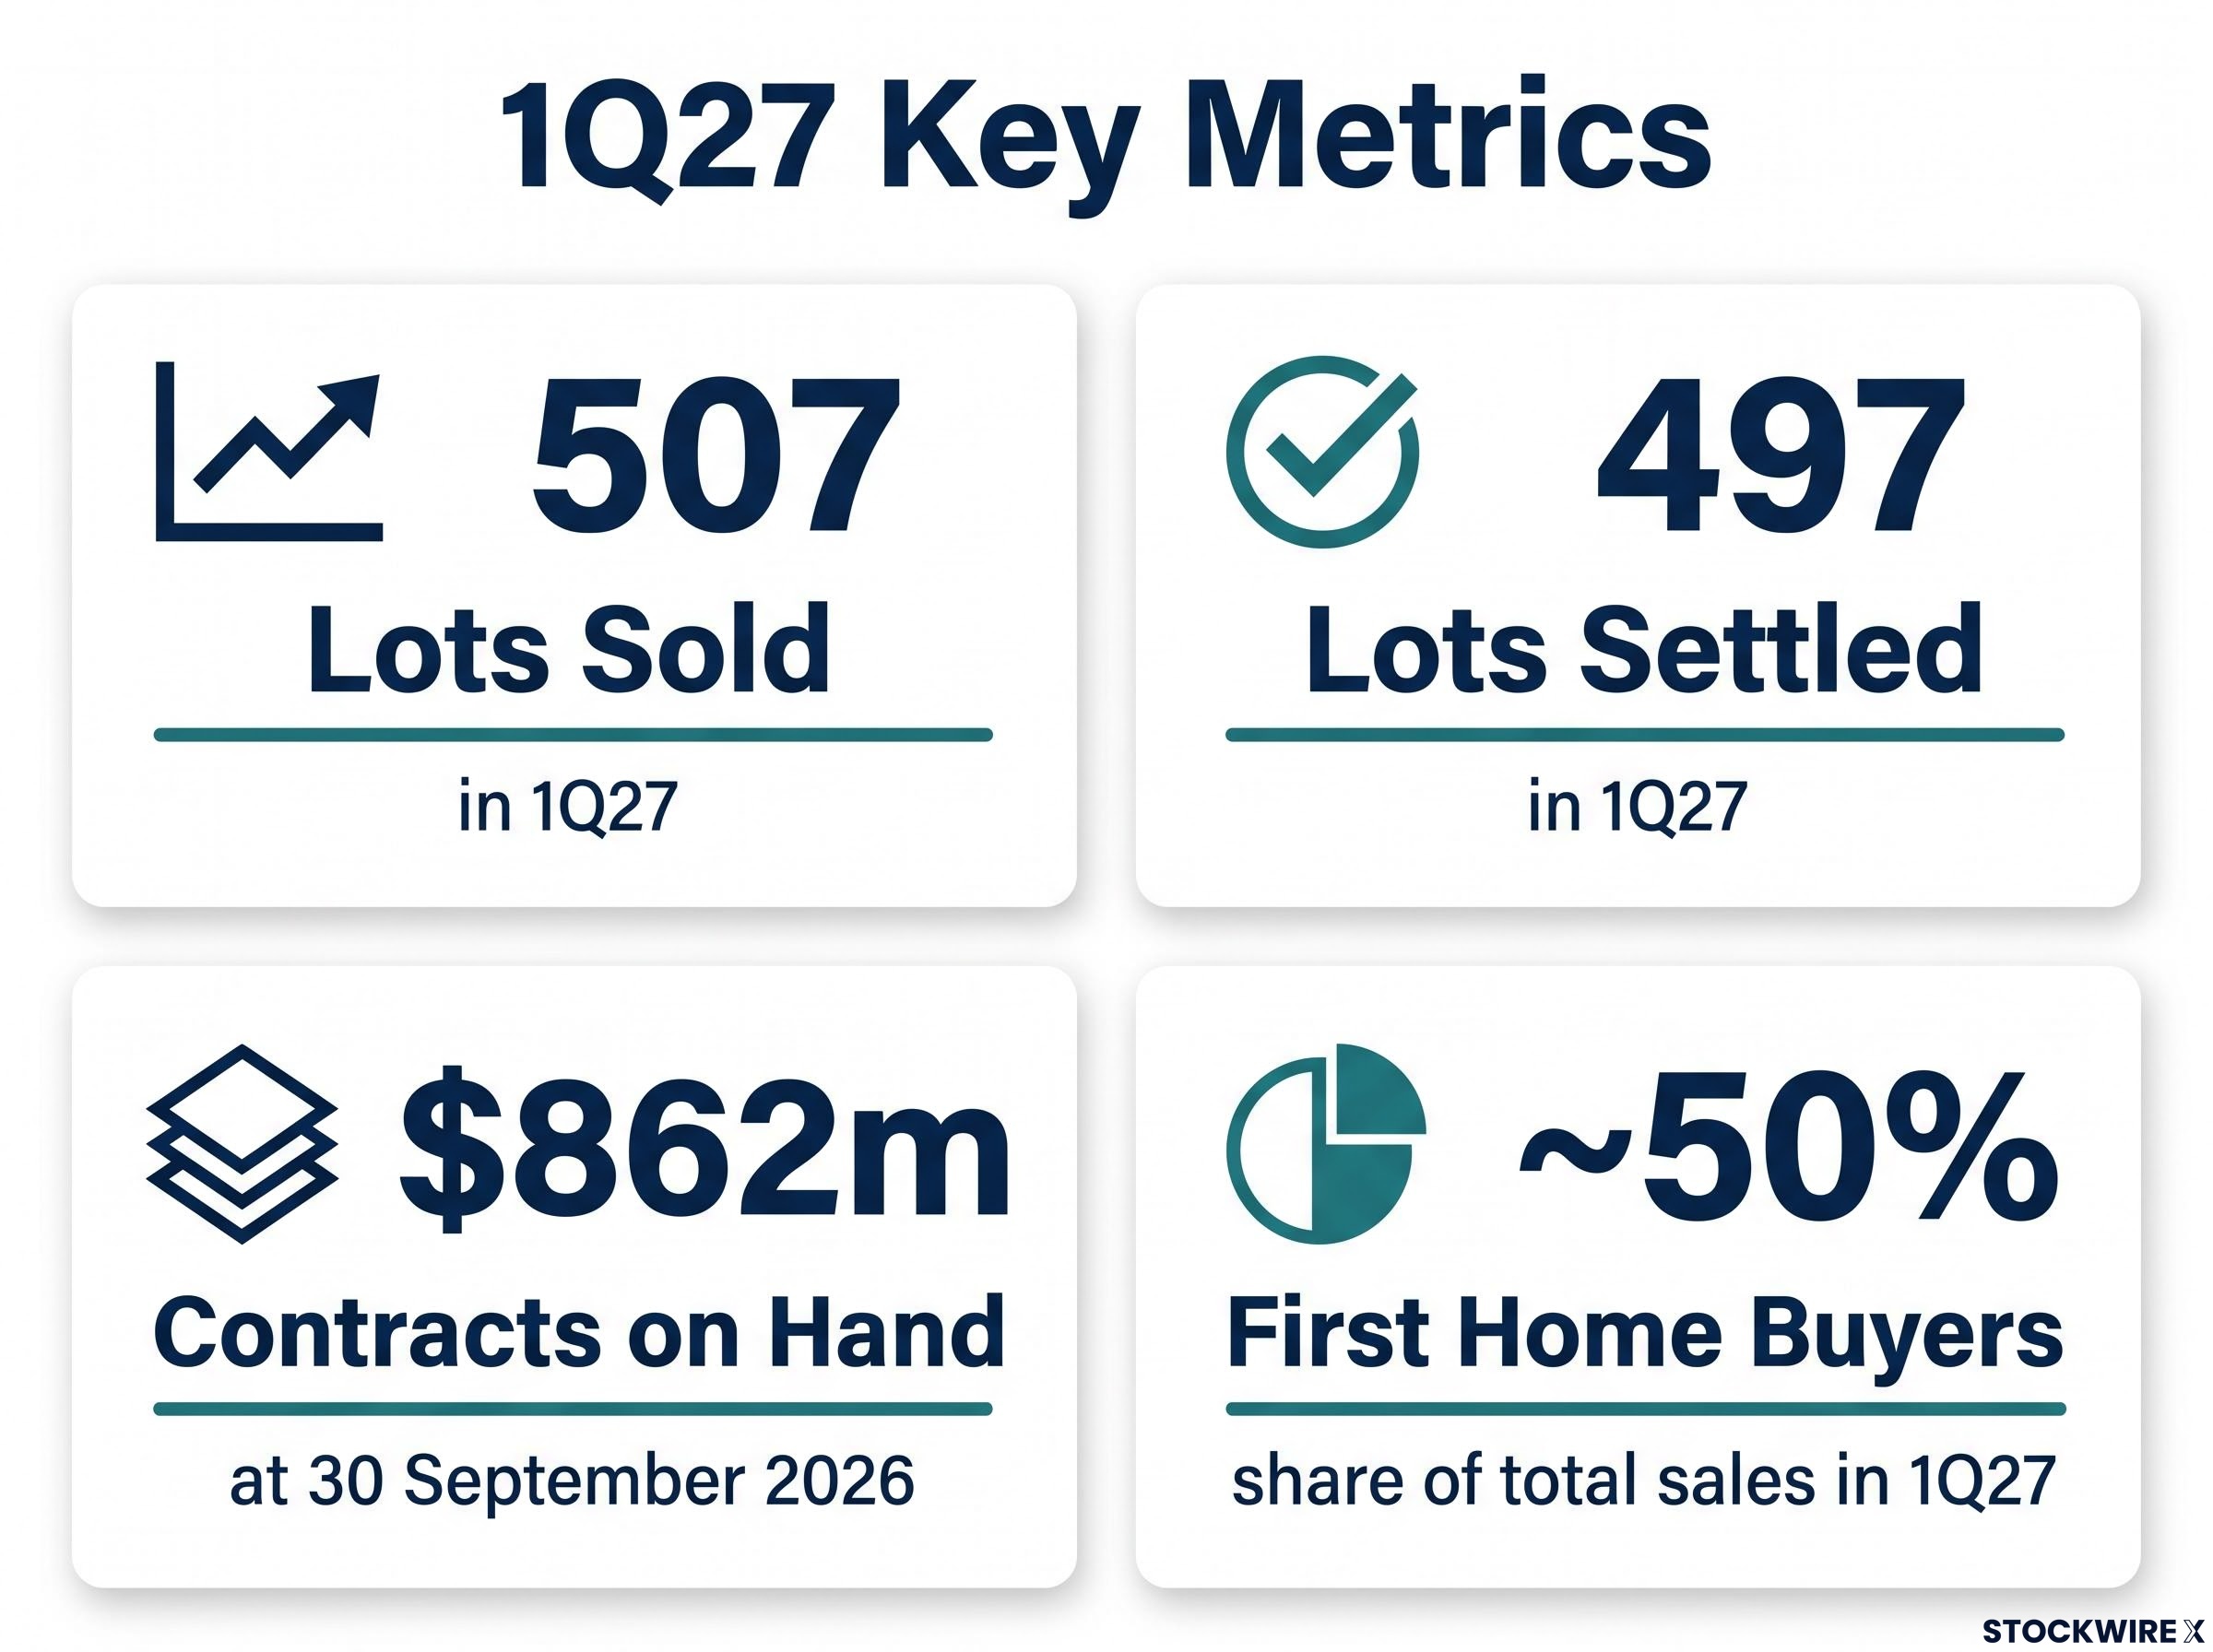
The business update, released on 30 October 2026, reports contracts on hand of $862m at 30 September 2026, in line with $851m at 30 June 2026. Contracts on hand give investors a view of earnings for the rest of the financial year.
Key 1Q27 metrics from the update:
- 507 lots sold and 497 lots settled in 1Q27 (including equivalent lots)
- Cancellation rates remain below long-term averages
- 1Q27 operating performance in line with budget
- $280m of the contracts on hand relate to projects 100% owned by Peet
The $862m figure also represents a 41% increase since 30 June 2025.
When big ASX news breaks, our subscribers know first
1Q27 operating performance and a more measured market
Sales steady after near record FY26 volumes
Peet achieved 507 sales in 1Q27, following near record FY26 volumes. Enquiries declined 21% compared with 4Q26, which the company attributes to a more measured purchasing environment.
New project activations are expected to contribute to near to medium-term sales volumes. Peet describes its outlook as positive, citing large, diversified land holdings in markets facing a long-term structural undersupply of housing and scarcity of available land for residential development.
First home buyers and affordability
House and land product in Peet’s estates is typically priced at a discount to established housing stock, which supports demand from first home buyers. First home buyers represented approximately half of total sales in 1Q27.
Investor interest in new house and land packages remains, given exemptions for new housing within recent taxation changes. Peet also says it can adapt product mix through increased density and pricing strategies as market conditions require.
Acquisition pipeline
Peet is assessing 2,800 potential acquisition lots (including equivalent lots). The company says it is focused on capital efficient structures.
Why Peet’s key markets matter: a short guide to masterplanned communities
Peet develops masterplanned communities (MPC), and its portfolio is mature, with an average age of approximately 15 years and strong cash generation. Approximately 80% of the property portfolio is activated, with all lots in a project counted as activated once the project is launched.
Gross development value (GDV) is the forecast future sales price of the remaining equivalent lots, subject to market conditions. Understanding these terms helps investors read the contracts on hand and the timing of settlements.
Approximately 75% of the portfolio sits in the major growth corridors of Greater Perth and South East Queensland.
| Market | Share of portfolio | Key projects | Market drivers |
|---|---|---|---|
| Greater Perth | About 35% | Yanchep, Shorehaven, Brabham | Relative affordability compared with Eastern States, interstate migration, first home buyers |
| South East Queensland | About 40% | Greater Logan, Sunshine Coast | ~2.0% compound annual growth rate to 2046 versus 1.3% nationally, estimated annual shortfall of about 13,000 homes |
| Melbourne | n/a | Aston (Craigieburn), activated in 1Q27: 984 lots over six years | High growth corridors, continued demand for affordable housing |
Portfolio percentages are based on Peet’s property portfolio and equivalent lots as at 30 June 2026.
Greater Perth and South East Queensland
In Greater Perth, Peet’s exposure is weighted to Yanchep, Shorehaven and Brabham, located in the northern and north eastern corridors. These corridors continue to benefit from significant infrastructure investment and residential demand led by first home buyers.
The South East Queensland market is moderating from peak conditions but remains supported by strong fundamentals, according to Peet. Supply is expected to tighten further over the medium to longer term, driven by a material reduction in available credit for new projects, a further lengthening in delivery lead times, and an expected tightening in contracting and labour markets ahead of the 2032 Olympic Games.
Peet says it is well placed to “opportunistically step into” the growing supply shortfall, given its projects are in production and available to meet demand for affordable residential product.
Peet’s key MPC pipeline at a glance
The appendix lists Peet’s key MPC projects as at 30 June 2026. Final settlement dates are approximate and subject to market conditions.
| Project | State | Final settlement | Project structure | GDV ($m) | Lots |
|---|---|---|---|---|---|
| Flagstone City | QLD | FY34+ | Owned | 3,994 | 9,324 |
| Palmview | QLD | FY33+ | Owned / Managed | 557 | 1,175 |
| Shorehaven | WA | FY34+ | Managed | 422 | 705 |
| Yanchep | WA | FY34+ | Managed | 738 | 2,025 |
| Brabham | WA | FY34+ | Managed | 814 | 2,038 |
| Newhaven | VIC | FY32+ | Managed | 320 | 1,017 |
| Aston | VIC | FY33+ | Owned | 477 | 984 |
| Googong | NSW | FY34+ | Managed | 550 | 941 |
| Key MPC Projects | n/a | n/a | n/a | 7,872 | 18,209 |
| Other MPC Projects | n/a | n/a | n/a | 1,529 | 5,853 |
| Total MPC Projects | n/a | n/a | n/a | 9,401 | 24,062 |
Lots include equivalent lots, Palmview includes contiguous land holdings across owned and managed projects, and Googong reflects Peet’s 50% share.
GDV is a long-term, forward-looking measure that reflects assumptions made by Peet management regarding the future development and sale of projects.
What happens next for Peet
Peet’s stated milestones and commitments are:
- FY27 NPAT outcome: Peet is targeting NPAT growth versus FY26 NPAT of $103m, subject to market conditions and settlement timing.
- Board updates: The Peet Board will continue to monitor market conditions and provide updates as appropriate.
- Aston project delivery: The Aston project’s 984 lots (including equivalent lots) are to be delivered over the next six years.
The Ingenia takeover proposal adds a further variable to the outlook, with a scheme meeting targeted for early December 2026 and implementation by late December, subject to ACCC and court approval.
Don’t Miss the Next Real Estate Mover on the ASX
Join 20,000+ investors getting FREE breaking ASX news within minutes of release, complete with in-depth analysis already done. Click the “Free Alerts” button at Big News Blast to get real-time property and other non-resource updates in your inbox the moment market-moving announcements break.