

NZK lifts FY26 earnings guidance as fish performance beats expectations
New Zealand King Salmon Investments Limited (NZX/ASX: NZK) has upgraded its FY26 earnings guidance, with pro-forma EBITDA now expected in the range of $36 million to $39 million, up from the previous range of $30 million to $34 million. Pro-forma EBIT guidance has also been revised upward to $27 million to $30 million, compared with the prior range of $21 million to $25 million.
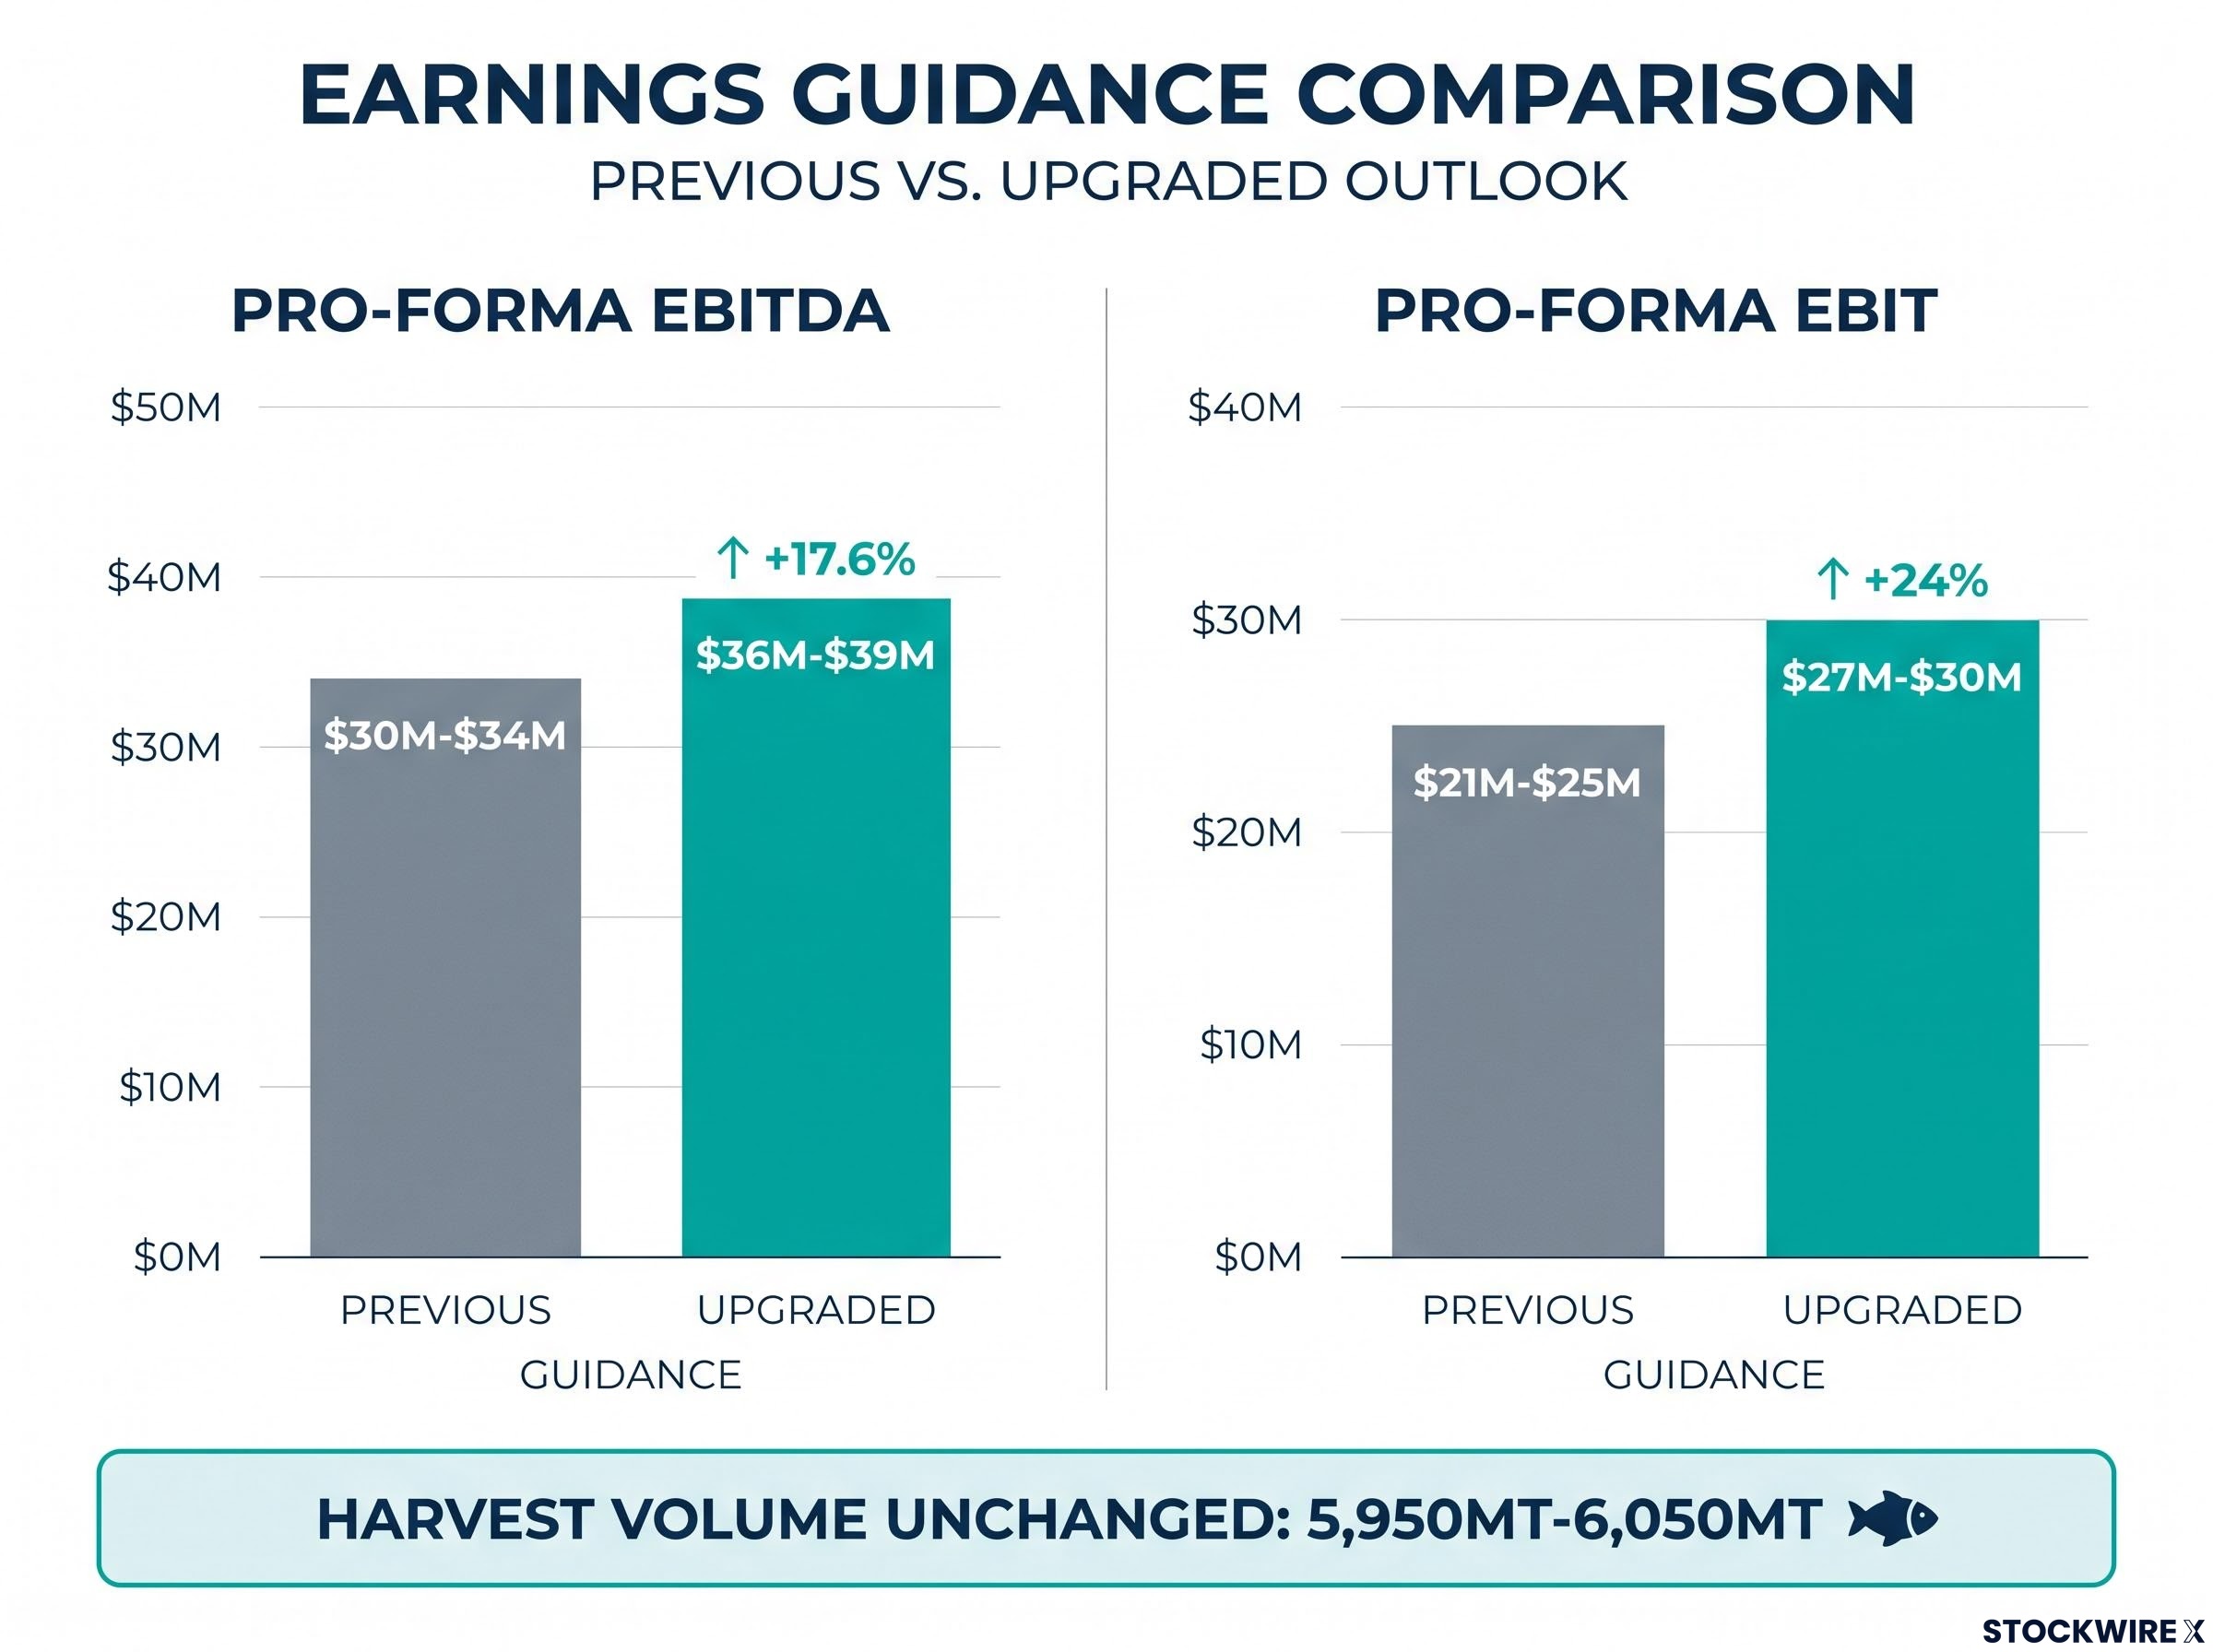
This represents a further guidance upgrade for the period, with harvest volume guidance remaining unchanged at 5,950MT to 6,050MT (whole gilled and gutted).
When big ASX news breaks, our subscribers know first
What’s driving the upgrade
The improvement in earnings is attributed directly to fish performance, with mortality levels continuing to come in below expectations. CEO Carl Carrington provided the following commentary:
Carl Carrington, CEO
“It is pleasing to be able to provide a further guidance upgrade for FY26. Our ongoing focus on fish performance continues to have a positive flow on impact to our earnings with mortality levels continuing to come in below expectations and ongoing fish performance upside.”
Understanding salmon farming economics — why fish performance moves the needle
In salmon aquaculture, mortality rates are one of the most direct levers on earnings. When fewer fish are lost during the growing cycle, the same initial stock produces a greater volume of harvestable fish. This improves yield without a corresponding increase in core production costs, which flows directly into margins.
Harvest volumes for NZK are measured in whole gilled and gutted (G&G) weight. This is the standard industry measure that reflects the usable weight of a salmon after initial processing — removing the gills and gut cavity — and serves as the primary production metric against which guidance is set.
The fact that NZK has upgraded its EBITDA range while leaving harvest volume guidance unchanged illustrates precisely this dynamic. The same expected volume of fish is now projected to generate materially higher earnings, reflecting better survival rates and the associated cost efficiencies that flow from stronger fish performance throughout the growing cycle.
Guidance comparison at a glance
The table below summarises the revision across NZK’s key FY26 guidance metrics.
| Metric | Previous Guidance | Upgraded Guidance |
|---|---|---|
| Pro-forma EBITDA | $30M–$34M | $36M–$39M |
| Pro-forma EBIT | $21M–$25M | $27M–$30M |
| Harvest Volume (G&G) | 5,950MT–6,050MT | 5,950MT–6,050MT (unchanged) |
What comes next — FY27 investment and cost headwinds flagged
While the FY26 upgrade is a positive development, NZK has been transparent about the cost environment ahead. The company is continuing to invest in growth to support delivery of the harvest volumes previously guided for FY27 and FY28.
NZK’s longer-term volume growth story extends beyond its existing freshwater and coastal operations, with the Blue Endeavour open ocean pilot farm now fully rigged and awaiting first fish stocking, a milestone that could validate a commercially scalable production model for the company.
Supply chain cost pressures already beginning to emerge in FY26, specifically increasing feed prices and wellboat expenses, are expected to be more fully realised in FY27. Investors should note that FY27 guidance is expected to be provided in November at the FY26 results announcement, making that the key near-term catalyst to watch.
The willingness to flag these headwinds alongside a strong upgrade reflects a balanced and transparent communication approach from management.
Key items for investor watchlists:
- FY26 results announcement: November 2026 (FY27 guidance expected at this point)
- Cost pressures to monitor: Increasing feed prices and wellboat expenses
- Growth investment: Ongoing capex to support FY27–FY28 harvest volume targets
Don’t Miss the Next Consumer Sector Earnings Upgrade
Big News Blast delivers FREE breaking ASX news directly to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ subscribers staying ahead of market-moving announcements. Click the “Free Alerts” button at StockWire X to start receiving alerts the moment news breaks.