
In its 23 October 2026 Strategy and Business Model Update, Doctor Care Anywhere outlined its reset and £4.9m EBITDA
In its 23 October 2026 Strategy and Business Model Update, Doctor Care Anywhere Group PLC (ASX: DOC) told the story of its January 2025 reset under Chief Executive Laura O’Riordan through its own lodged numbers. The primer states that it contains no new financial information, no forecast, no target and no guidance.
Management outlined £4.9m of EBITDA for the twelve months to 30 June 2026 (derived, with no adjustments) and cash of £7.7m at 30 June 2026, up 60% in a year. Free cash flow was £1.5m in H1 FY26. The primer gives investors a single reference document and a repeatable way to read each future update.
From reset to result
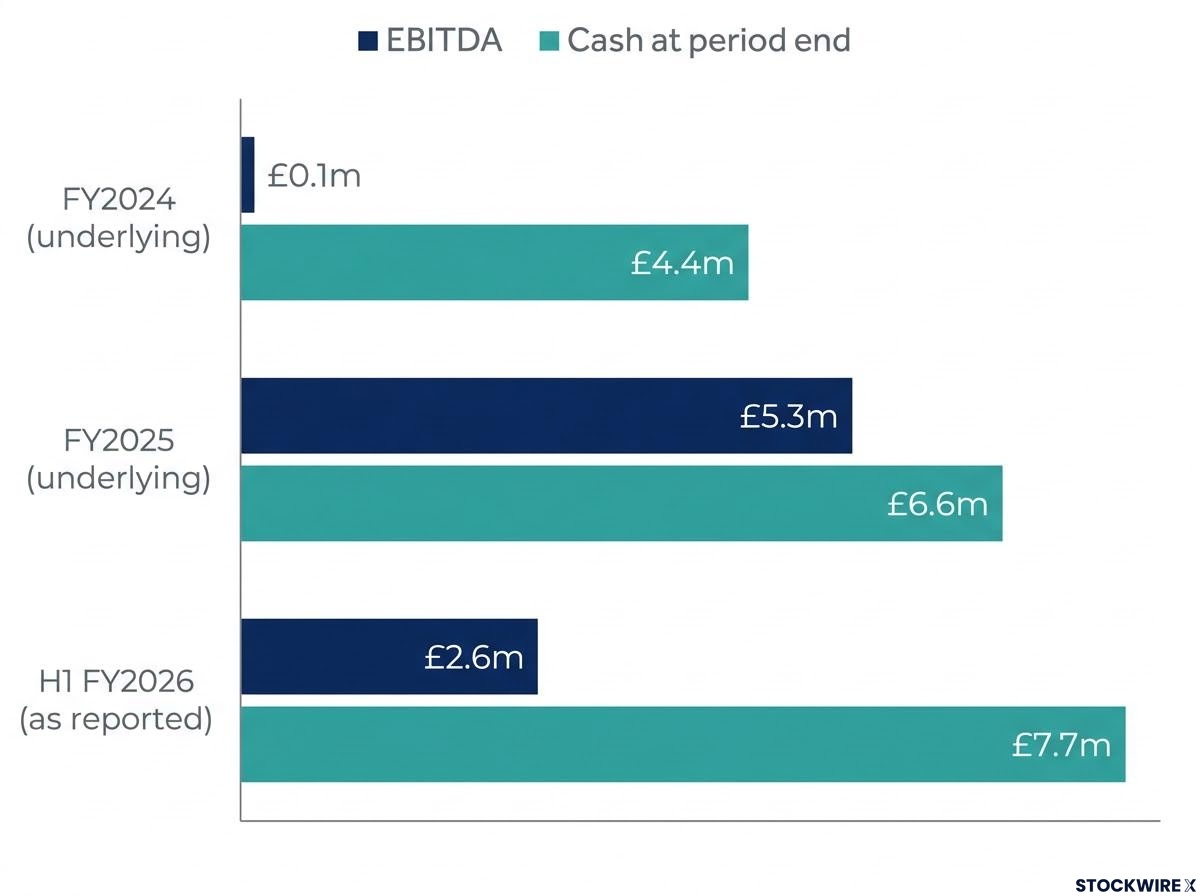
The primer’s Table 2.1 sets out the outcome across three balance dates. FY2024 and FY2025 EBITDA are on the Company’s underlying basis, while H1 FY2026 is as reported.
| Measure | FY2024 (underlying) | FY2025 (underlying) | H1 FY2026 (as reported) |
|---|---|---|---|
| EBITDA | **£0.1m** | **£5.3m** | **£2.6m** |
| Contribution margin | **38.3%** | **43.5%** | **42.0%** |
| Cash at period end | **£4.4m** | **£6.6m** | **£7.7m** |
| Net assets / (liabilities) at period end | **(£645,000)** | **£1.0m** | **£1.8m** |
The Company said FY2025 EBITDA was £4.4m on a statutory basis. It describes FY2025 as its first profitable year, with cash generation positive for the first time, in its own milestones table.
In May 2026, the Chair described the balance sheet as “rehabilitated”.
When big ASX news breaks, our subscribers know first
How the reset worked: operating leverage and diversification
Labour cost down 4.9% as revenue grew 6.3%
The Company moved its clinician mix toward advanced clinical practitioners (ACPs), pharmacists and paramedics, reaching a 60:40 GP to ACP mix. Mental health practitioners and physiotherapists were added to the platform in the second quarter of 2025, which the Company says lowers its cost to serve.
In H1 FY26, total labour cost fell 4.9% while revenue grew 6.3% to £20.4m. Contribution was £8.6m and the EBITDA margin was 12.8%. The Company attributes the labour result to better control of labour hours and mix.
The H1 FY26 results showed EBITDA up 27.1% on revenue growth of only 6.3%, and the ASX granted relief from quarterly cash reporting in July 2026 as the company moved into sustained cash generation.
Subscription share rising to 10.8% and weight management
On 8 May 2026, the Company acquired the GLP-1 and medicated weight-loss business of Outcome Diagnostics and MedicSpot for £850,000 in cash. It contributed £0.9m of revenue in its first 54 days, at approximately breakeven.
Subscription revenue share reached 10.8% in H1 FY26 from 7.1% in H1 FY25. The Company’s own illustration of the acquired run rate would put it at around 19%. The Company states that this illustration is not a forecast, involves risks and uncertainties, that actual results may differ, and that it does not undertake to update it.
Other channels were also covered. A partnership with Ramsay Health Care UK gives Ramsay patients self-pay online GP appointments with onward referral into its hospitals. An October 2026 partnership with Rippl, dated 2 October 2026, took the weight-management service into employer benefits.
The primer lists three routes, each with lodged evidence:
- Direct to consumer: 2.4 million UK adults now use GLP-1 medication, and the NHS programme reaches about one in fifteen of those eligible.
- Employers: Mercer Marsh Benefits reports that demand for private virtual GP appointments is accelerating.
- Insurers: a large UK insurer, Vitality, added a second virtual GP provider in February 2026 rather than consolidate on one.
Reading DCA: three numbers and eight levers
UK insurers can pay for private GP consultations, which Australian insurers are not permitted to do. DCA is paid for activity delivered and does not carry underwriting risk.
Utilisation revenue comes from individually purchased consultations. Subscription revenue comes from monthly or annual service subscriptions. Because subscription revenue is where corporate and direct-to-consumer channels are recorded, the Company regards its share as the best available indicator of diversification.
The primer follows three numbers:
- Consultations: 354,900 in H1 FY26, up 1.4%.
- Revenue: £20.4m in H1 FY26.
- Subscription share: 10.8% in H1 FY26.
Each quarterly update is to report consultations, total revenue, subscription revenue and cash at bank. The primer also names eight levers, six that move revenue and two that move cost, each tied to the reported number it would move.
The primer sets out what would show the reset is not holding:
- Consultations falling
- Subscription revenue share flat or falling
- Contribution margin falling
- Free cash flow turning negative
What investors should weigh: concentration, convertible notes and register
The primer presents these as the Company’s own “Hard Facts”.
- Around 93% of FY2025 revenue came from the Company’s largest customer relationship. Around 89% of H1 FY26 revenue came from insurance (derived).
- £10.6m of interest-free convertible notes mature on 31 December 2027, with just over half held within that same relationship. Full conversion at £0.0459 (A$0.0875) per CDI would add up to 231,788,288 CDIs, approximately 38.7% of enlarged capital.
- 367,065,323 CDIs were on issue at 19 August 2026 (derived composite). The register analysis is stated separately at 6 March 2026.
- The fully diluted figure, which includes options and notes, totals 667,741,418 CDIs (derived).
| Outcome | Effect on register | Effect on cash |
|---|---|---|
| Conversion, in whole or part, at £0.0459 per CDI | Up to **231,788,288** new CDIs, **38.7%** of enlarged capital | None leaves |
| Redemption at maturity | New equity, if that is the route, brings new holders onto the register | Approximately **£10.6m** against **£7.7m** cash at 30 June 2026 |
The Care Quality Commission rating remains “Requires Improvement”, unchanged since October 2023.
The primer is updated after each half-year and full-year result and each quarterly update, and always after the Company has released the information to the ASX.
Don’t Miss the Next Healthcare Breakout
Join 20,000+ investors getting FREE breaking ASX news within minutes of release, complete with in-depth analysis and the full announcement. Click the “Free Alerts” button at Big News Blast to receive healthcare and other non-resource alerts the moment market-moving news breaks, ahead of the crowd.