Taiwan has just posted the largest trade surplus in its history, and the Taiwan dollar is weaker than it was in January. Ministry of Finance data released today show a US$23.63bn surplus for September 2026, built on record exports of US$87.22bn, yet USD/TWD closed at 31.875 on 8 October, softer than the 31.48-31.63 range of early 2026.
Any Taiwan dollar analysis that starts from “big surplus, strong currency” runs straight into that gap.
The timing matters. September consumer prices rose 2.73% year-on-year, the fastest pace since early 2024, and Taiwan’s central bank (CBC) holds its next board meeting on 17 December. If you follow Asian rates, currency markets or AI-linked assets, the currency puzzle and the rate decision are now the same story.
Here is what the evidence says about which flows actually move the Taiwan dollar, and how to judge whether a December rate hike is a realistic prospect.
Why has a record surplus not lifted the Taiwan dollar?
The headline numbers are hard to argue with. Exports jumped 60.9% from a year earlier, a monthly record for the second month in a row, while imports climbed 51.7% to their own record.
| Metric | Sept 2026 value | YoY change |
|---|---|---|
| Exports | US$87.22bn | +60.9% |
| Imports | US$63.59bn | +51.7% |
| Trade surplus | US$23.63bn | Up from US$12.30bn |
| Export prices (USD basis) | Index | +25.8% |
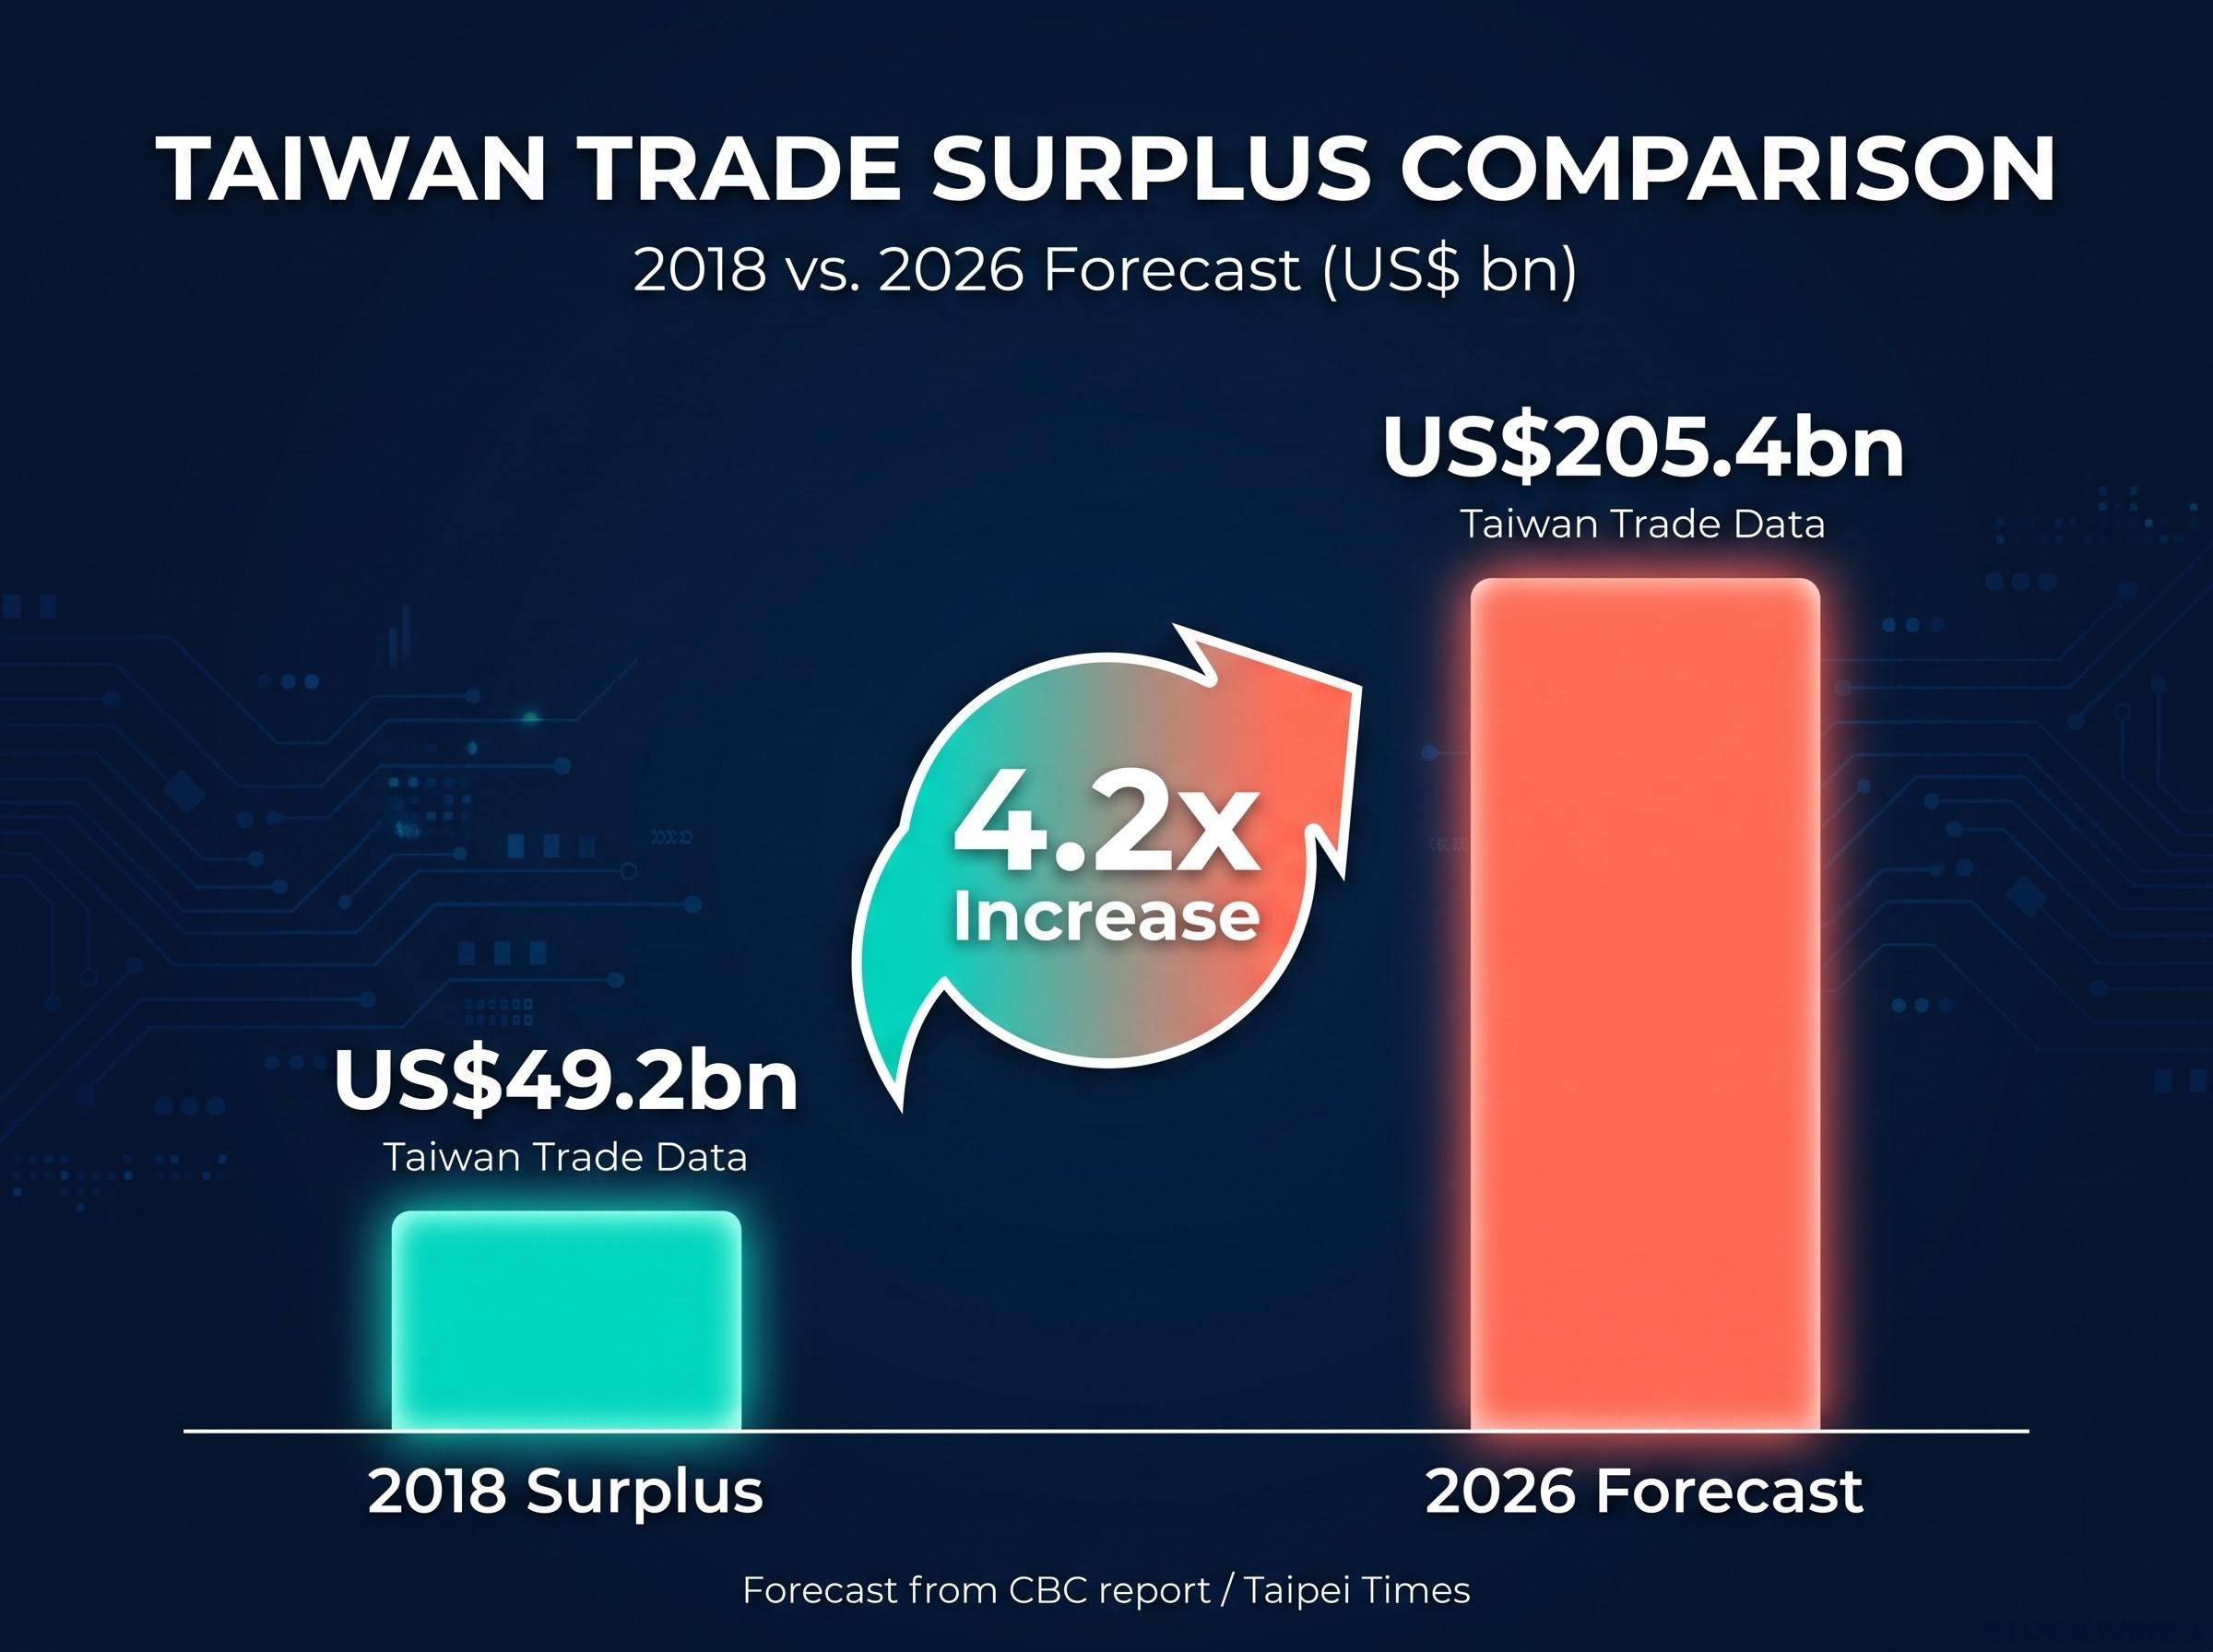
AI and semiconductor demand drove the surge, led by communication products and electronic components. The January-September surplus now stands at US$160.55bn, and a CBC report cited by the Taipei Times forecasts US$205.4bn for the full year, 4.2 times the US$49.2bn recorded in 2018.
The currency tells a different story. USD/TWD has traded roughly 31.78-31.94 through October, a modest depreciation for the year. Lynn Song of ING noted that, despite record surpluses and heavy foreign money flowing into a buoyant equity market this year, the Taiwan dollar has not gained the kind of strength those conditions would normally suggest.
That is the mismatch. The trade data measure how much the world wants Taiwan’s chips; the exchange rate measures where the money ends up.
Newsquawk on trade prints Monthly Taiwan trade releases have rarely shifted TWD durably by themselves, with the currency more responsive to the broader dollar, equity flows through the tech-heavy local market and the central bank’s smoothing.
The read for you is direct: a record trade headline is a poor signal for trading the Taiwan dollar. Flows and policy carry the weight.
Analysts increasingly argue that foreign equity flows into the Taiwan Stock Exchange, rather than rate spreads, dominate day-to-day USD/TWD moves, with Bank of America and Commerzbank both pointing to a ceiling near 32.00.
When big ASX news breaks, our subscribers know first
How trade surplus money gets diverted: outward investment, yield gaps and central bank smoothing
The standard link, and where it breaks
The intuitive mechanism is simple. An exporter sells chips abroad, earns US dollars, and converts them into Taiwan dollars to pay staff and suppliers. Multiply that across an export boom and you get rising demand for the local currency.
In Taiwan, that chain is being interrupted before the conversion happens. ING and the CBC point to three leaks:
- Outward investment: corporates use export earnings to build production capacity overseas, keeping the dollars abroad.
- The yield gap: a yield gap is the difference between interest rates in two countries, and US rates sit well above Taiwan’s, so investors park funds offshore rather than bring them home.
- CBC smoothing: the central bank leans against sharp moves, limiting how far the currency can rise.
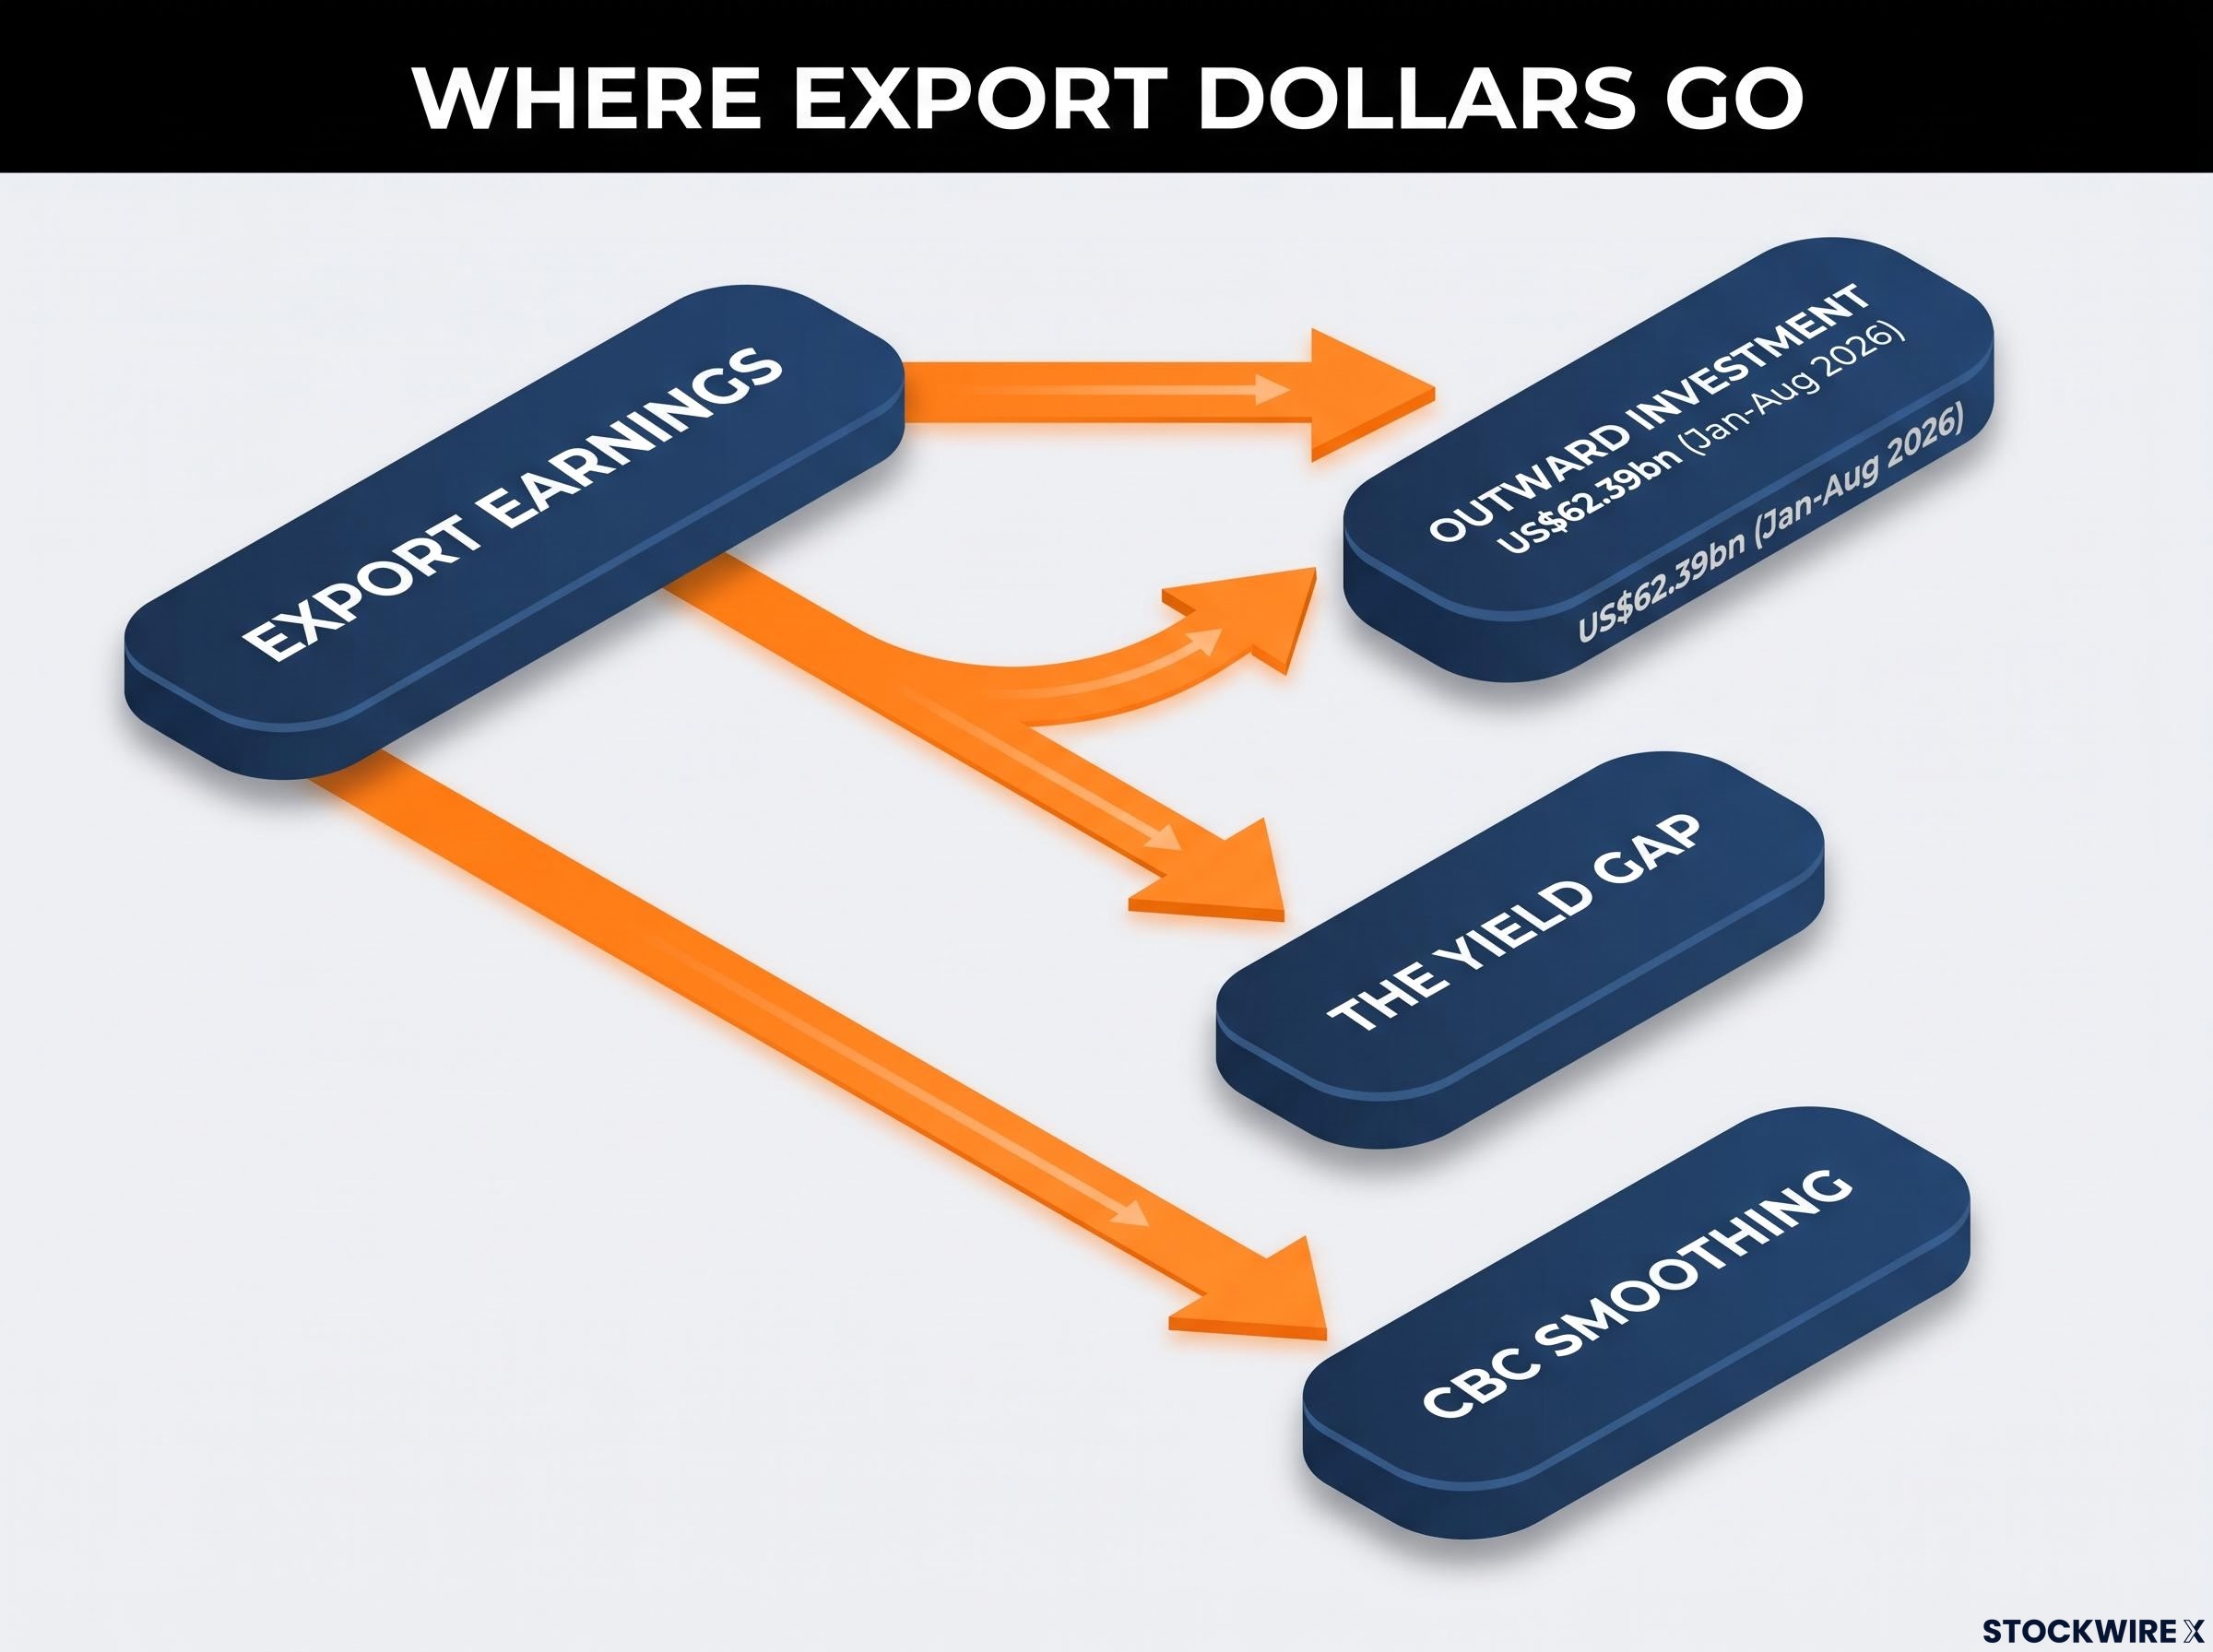
The first leak is large. Outward investment excluding mainland China reached about US$62.39bn in January-August 2026. The second is a carry-type outflow, meaning money moves to where it earns more interest, and it compounds the first.
One caution on another widely quoted figure. The CBC reports foreign portfolio holdings of securities and deposits at US$1,927.2bn, equal to 321% of foreign exchange reserves. That is a stock, the total accumulated over years, not a monthly flow, so it tells you how much money could move rather than how much is moving now.
There is also a gap in the evidence. The research did not find data on how much exporters or life insurers hedge their dollar exposure, so the size of that channel remains unquantified.
The central bank’s role in capping moves
The CBC is open about its role. It states that when irregular forces, such as large short-term capital flows, or seasonal factors cause excess volatility or disorderly movements, the bank will step in to keep the market orderly.
Leaning against large moves works in both directions. It can also stop the currency appreciating in line with trade fundamentals, which helps explain why a record surplus produced so little movement.
The CBC’s managed-float regime, backed by reserves of roughly US$594-597bn, explains why USD/TWD has stayed pinned near 31.50-32.00 even as exports set records; the framework holds the range by design.
What this tells you is that the surplus is real, but much of its dollar value stays offshore. Underlying demand for the Taiwan dollar is weaker than the headline suggests, and that framework (trade balance, capital account and central bank read together) applies to any export-led currency.
Is a December rate hike justified? Weighing inflation, growth and the currency
The case for a hike starts with prices. Inflation jumped from 2.05% in August to 2.73% in September, the fifth consecutive month above the CBC’s 2% target. ING described the print as “hot”.
Growth gives the CBC room to act. AI-driven exports suggest the economy no longer needs rates this low, and policy settings remain where the board left them on 17 September: a 2.0% discount rate, 2.375% collateralised lending rate and 4.25% short-term lending rate.
ING’s view “There’s a solid case for the CBC to hike at its December meeting,” said Lynn Song of ING, adding that much could change before then.
ING’s argument also links back to the currency. A hike would narrow the yield gap that encourages money to leave, which could offer the Taiwan dollar some support.
The CBC itself has sounded more measured. It held in September, describing inflation as contained this year while monitoring risks, and it keeps returning to exchange-rate stability.
- Case for a hike: inflation above target for five months, strong AI-led growth, and a narrower yield gap that could reduce outflows.
- Case for holding: the September hold, the bank’s description of inflation as contained, and its priority on orderly currency markets.
The research found no named institution arguing explicitly against a December move. That leaves the debate weighted towards a hike but not settled.
For you, the point is that a hike would act on two fronts at once: inflation and the capital outflow channel. That matters if you hold Taiwan dollar assets or exposure to Taiwanese equities, but treat it as a probability rather than a forecast.
These statements are speculative and subject to change based on market developments and policy decisions.
For readers weighing the timing, our full explainer on the CBC’s hold sets out why Commerzbank sees Q1 2027 as the first live window for a hike.
What could break the pattern: risks to the surplus and the currency
The current picture rests on a narrow base. Three fault lines would change the analysis:
- AI-cycle concentration: Reuters and ING both stress that export growth leans heavily on AI chips, ICT and electronic parts, so a slowdown in data-centre spending would hit the surplus directly.
- US trade policy: the CBC’s own comparison runs from the US$49.2bn surplus of 2018, when the US-China tariff dispute began, to the US$205.4bn forecast for 2026, and shifts in tariffs could threaten that export engine.
- Fed policy and short-term capital: with foreign holdings at 321% of reserves, a change in US rates could trigger reallocations that move the Taiwan dollar regardless of trade data.
The last channel is the one the CBC names most often as a source of disorderly moves. It is also the one most likely to overwhelm any monthly trade print.
The Fed’s 25 basis point rate hike to 3.75%-4.00% in September, delivered under a monetarist lens, widens the very yield gap that encourages Taiwanese capital to stay offshore.
The takeaway is that this surplus is cyclical and concentrated. Any view or position built on it needs a plan for an AI slowdown or a global rate shift.
Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors.
What to watch before the 17 December CBC meeting
Taiwan’s trade strength confirms global tech demand. The currency’s path is set elsewhere: by outward investment, the yield gap and a central bank that prefers calm over momentum.
Three variables will shape the December decision:
- October and November CPI: whether inflation stays above the 2% target.
- Fed direction and the yield gap: any narrowing could slow outflows.
- AI-export momentum and CBC smoothing: signs of cooling shipments or heavier intervention.
Much can change before the meeting. If inflation holds and the yield gap narrows, ING’s hike case strengthens; if either slips, the CBC’s caution is likely to win.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.