Nike reports earnings after market close today, 1 October 2026, and the stakes sit higher than any routine quarter would warrant. The stock has shed more than 44% of its value this year, the company was ejected from the S&P 100 last month after an 18-year run, and CEO Elliott Hill’s turnaround is now approaching its two-year mark without a convincing top-line reversal to show for it.
This is not a check-in. Tonight’s numbers land in a market that has already delivered a harsh verdict, with more than $220 billion in value erased since the November 2021 peak.
For anyone holding Nike shares, or weighing whether the collapse has opened a buying window, the report is the first hard test of whether Hill’s strategy is working or whether the structural cracks are widening.
Here is a framework for reading tonight’s release: which signals carry weight, which are noise, and how to make a more informed call on Nike as an investment at a genuinely uncertain moment.
Where Nike stands before tonight’s numbers
Before any analysis of what Nike reports tonight, the magnitude of where the company already sits deserves to register fully. The decline is not abstract; it is measurable, and it is severe.
The three figures that define the backdrop:
- Year-to-date share-price decline of more than 44% through October 2026, leaving the stock near a 12-year low
- A market-value loss exceeding $220 billion from the November 2021 peak
- Removal from the S&P 100 after roughly 18 years, announced 4 September 2026 and effective 21 September 2026
Nike has shed more than $220 billion in market value since its November 2021 high. That is not a correction. It is a wholesale re-rating of what the market believes the business is worth.
The index expulsion is more than symbolic. Removal from the S&P 100 triggers forced selling from index-tracking funds that must mirror the benchmark, and it quietly removes Nike from the default watchlists of generalist institutional money. Winning that capital back is a harder, slower task than simply posting one good quarter.
Passive fund flow dynamics explain much of why Nike’s S&P 100 removal carried consequences beyond the symbolic: index-tracking funds that must mirror the benchmark were obligated to sell, quietly removing the stock from the default watchlists of generalist institutional money that is hardest to win back.
The financial baseline matters just as much. For fiscal 2026, Nike reported full-year revenue of approximately $46.4 billion, down roughly 2% on a currency-neutral basis. That is stagnation, not growth, and it is the number every forward projection now builds from.
| Metric | Q4 FY2026 | Full-year FY2026 |
|---|---|---|
| Revenue | $11.0B (-4% currency-neutral) | ~$46.4B (-2% currency-neutral) |
| Diluted EPS | $0.72 (incl. $0.52 tariff benefit) | Not separately disclosed in research |
| Gross margin | 49.2% (+890 bps YoY) | Not separately disclosed in research |
| Channel split (Direct / Wholesale) | Reported at full-year level | $17.7B / $27.5B |
Here is what this baseline tells you. A 12-year low and an index expulsion mean the market has already priced in significant deterioration. That cuts both ways: the bar for what counts as “bad news” tonight is lower than usual, but any genuine positive surprise lands against depressed expectations and carries amplified upside.
When big ASX news breaks, our subscribers know first
What Elliott Hill has actually changed, and where the evidence is thin
Strip away the management narrative and Hill’s turnaround comes down to a concrete set of operational decisions. The clearest way to read whether they are working is not his commentary; it is the channel data.
Hill’s plan rests on three pillars: refocusing Nike on sports performance, including soccer and running; rebuilding the wholesale partnerships Nike had deliberately walked away from; and retreating from the Nike Direct-first model that defined the company’s prior strategic era.
That last point is the pivot that matters. For years, Nike pushed customers toward its own stores and app, selling directly to protect margin and brand control. Nike Direct simply means the company’s own channels, its retail shops and digital platforms, as opposed to selling through third-party retailers. Hill is reversing that bet.
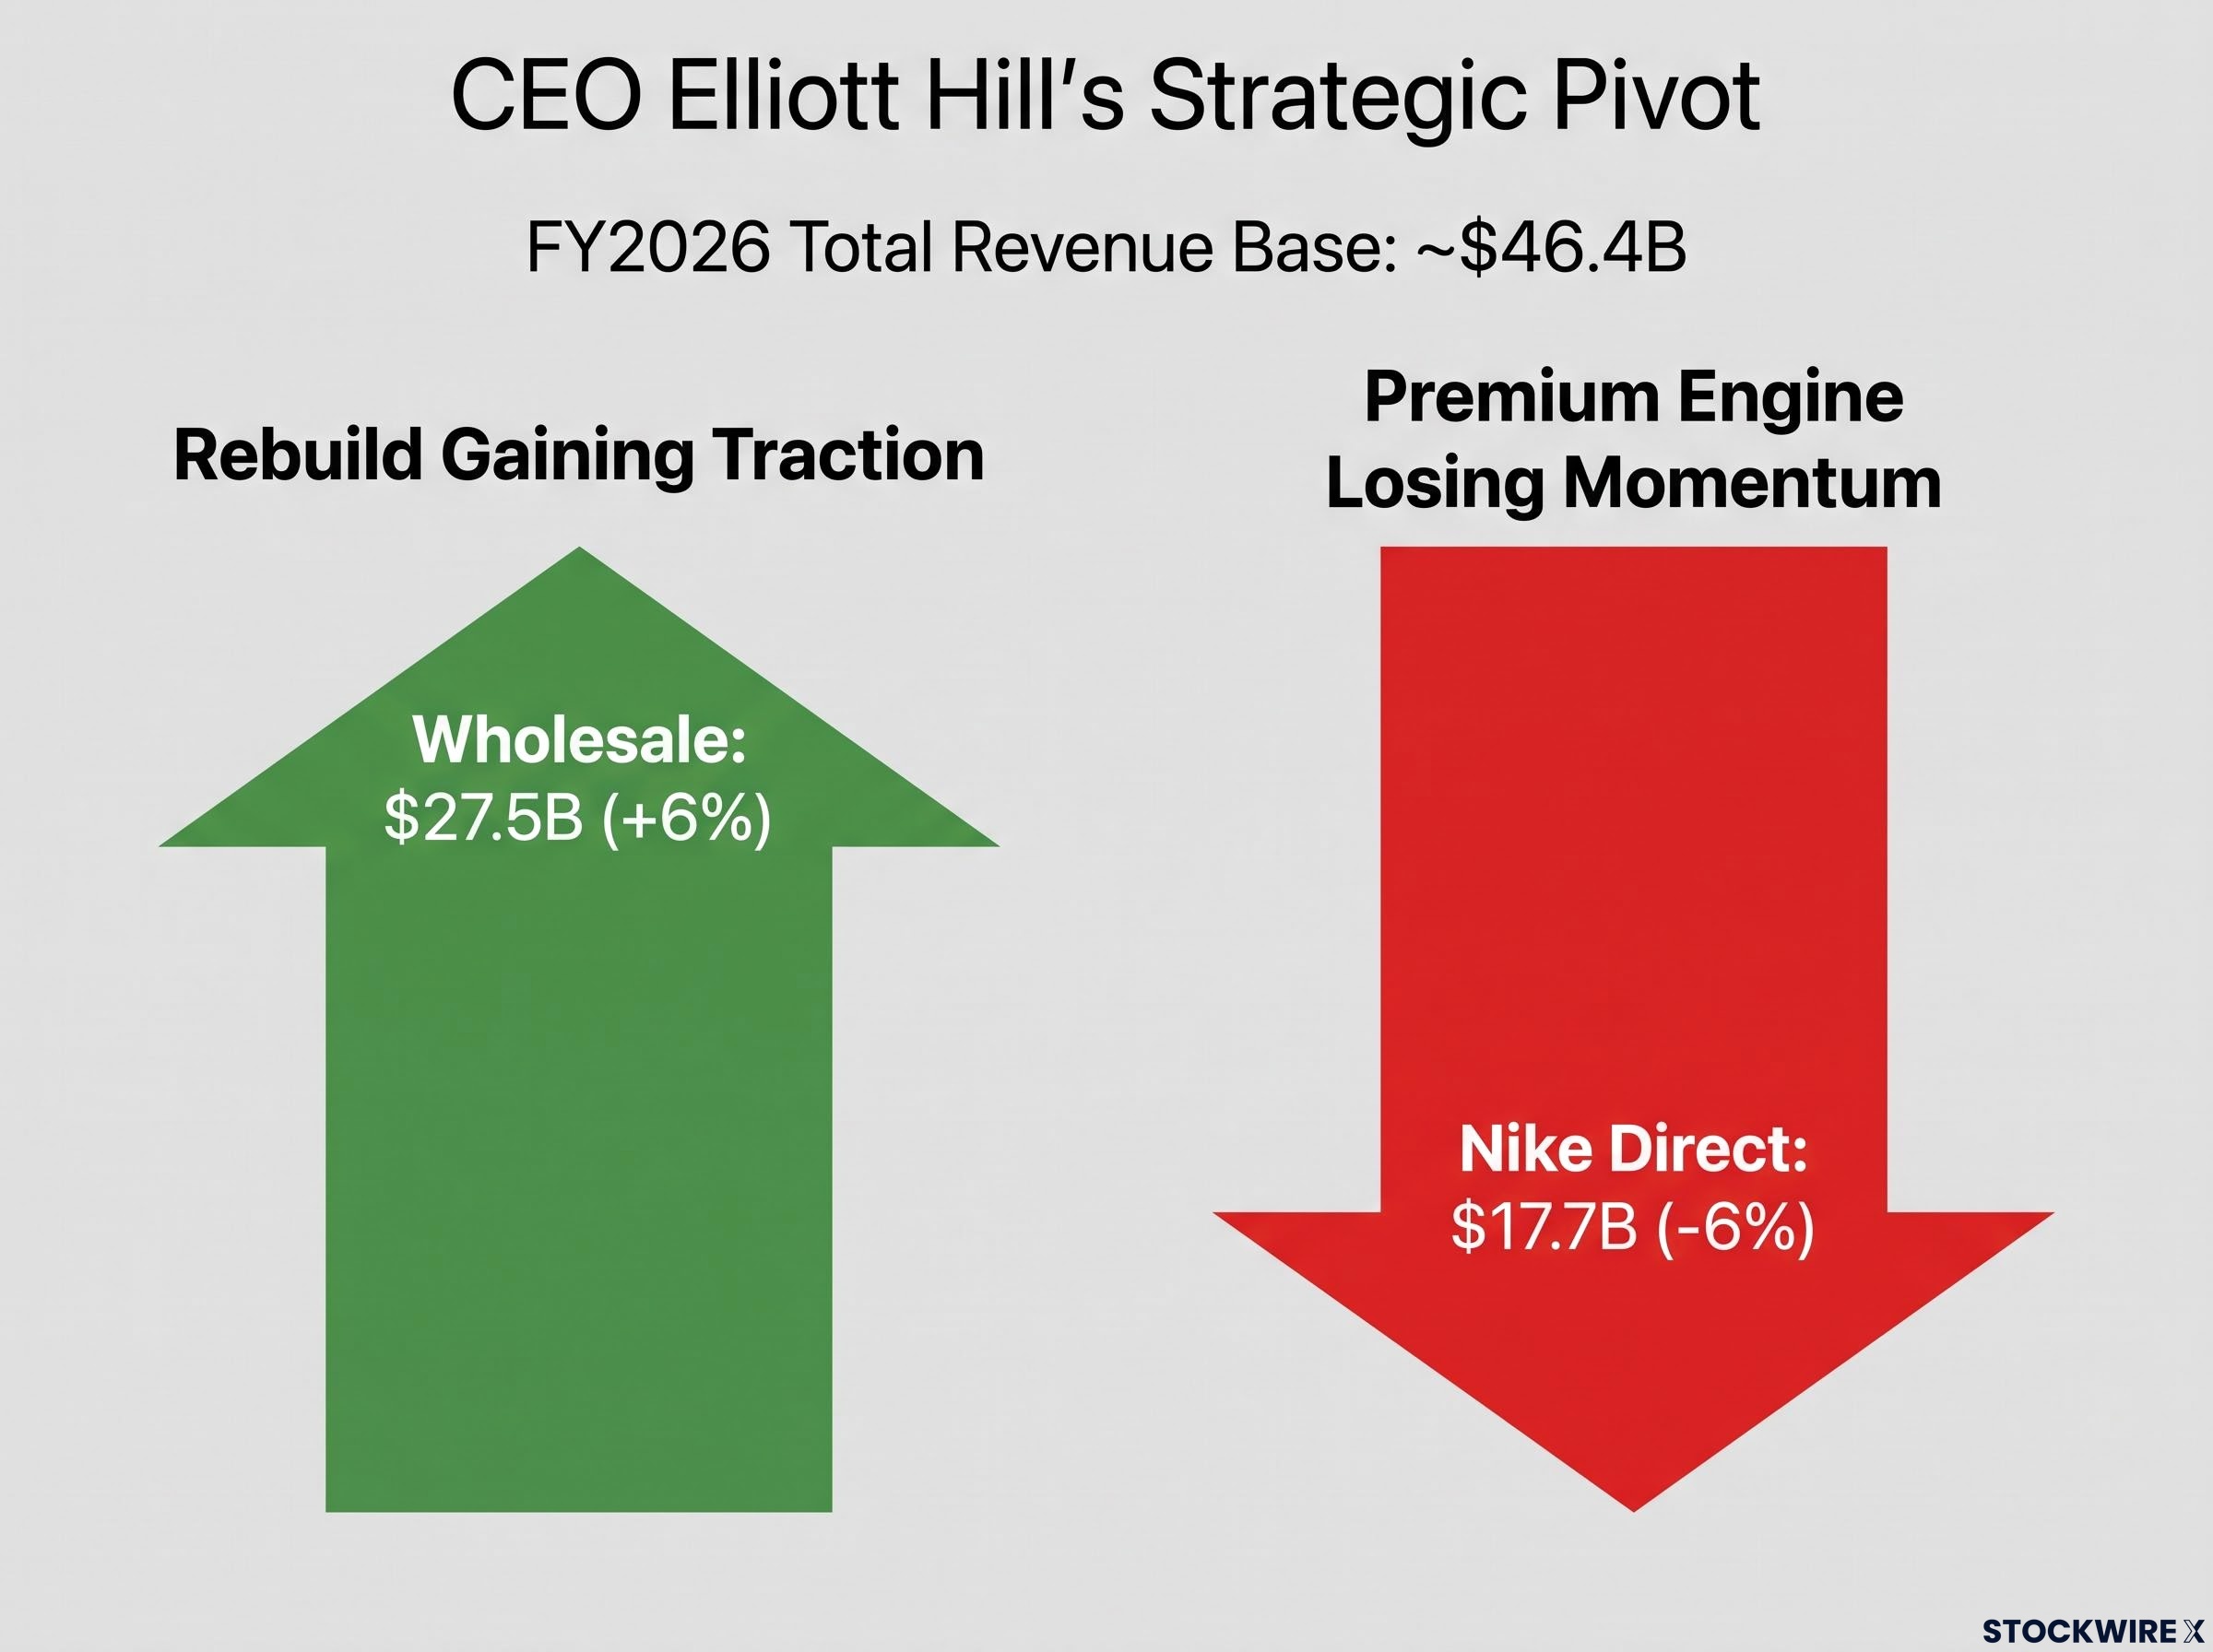
The fiscal 2026 channel split is the clearest measurable evidence of the shift:
| Channel | Wholesale | Nike Direct |
|---|---|---|
| FY2026 revenue | $27.5B | $17.7B |
| Year-over-year change | +6% | -6% |
| Strategic implication | Rebuild gaining traction | Premium engine losing momentum |
The wholesale rebuild in detail
The wholesale recovery is Hill’s most tangible result. It involves re-engaging retail partners Nike had sidelined, widening product availability back through third-party channels, and reversing the selective-distribution approach that defined the previous strategy.
There is a cost to this. Rebuilding wholesale means surrendering some of the brand control and margin premium that Nike Direct was built to protect. You are trading margin quality for volume reach, and that trade-off will show up in future profitability.
Where the turnaround narrative still lacks proof
Here is the uncomfortable arithmetic. A 6% wholesale gain does not offset a 6% Nike Direct decline at the dollar level, because the channels are different sizes and pull in opposite directions. The result is an overall top line still stuck near $46.4 billion.
Hill has been in the chief executive seat for close to two years. The strategic pivot is visible, but the revenue needle has not moved, and management issued no specific numerical guidance at the June release.
Consumer brand turnarounds of Nike’s scale rarely resolve in two years; Starbucks similarly faced a multi-quarter gap between its strategic reset announcement and measurable top-line improvement, reinforcing why analysts and investors apply a high evidentiary standard before re-rating a stock on turnaround momentum alone.
Reuters captured the gap bluntly, noting the quarter “failed to reassure investors seeking clear signs that Hill’s nearly two-year effort to revive growth is gaining traction.” What this tells you is simple: the wholesale recovery is real but partial, and the strategic pivot remains incomplete.
The China problem and why it matters more than any single quarter
If one geography deserves disproportionate attention tonight, it is Greater China. And the reason is a trend, not a level.
Greater China sales fell 17% on a constant-currency basis in Q4 fiscal 2026. Constant-currency simply strips out exchange-rate swings to show the underlying demand picture. The prior quarter, that same figure was a 10% decline.
Greater China sales dropped 17% constant-currency in Q4, widening from a 10% fall the quarter before. The direction is what matters, not the single number.
China is not a peripheral market for Nike. It was one of the company’s most important growth engines and a central plank of the long-term earnings thesis. A declining China reframes Nike from a global growth story into a mature, shrinking business in a region that was supposed to compound for years.
Reuters described management’s stance on the region as a “cautious outlook,” language that implies the company is braced for continued softness rather than a quick snap-back.
What should you look for tonight on China? Two things:
- Whether the rate of constant-currency decline narrows from the 17% Q4 level. A smaller decline is progress, even without a return to growth.
- Whether management commentary points to active stabilisation measures, specific brand or product actions, rather than passively waiting for the macro backdrop to improve.
The widening from 10% to 17% in consecutive quarters tells you this is not a China macro story that will self-correct. It points to brand-momentum erosion that requires active intervention. Tonight’s number will tell you whether that intervention has begun to register, and that is why watching only the headline EPS while ignoring the China segment leaves you reading the report incompletely.
The risks hiding inside Nike’s best recent numbers
Nike’s Q4 produced two genuinely strong headline figures: an EPS beat and a sharp gross-margin expansion. Both were real. Both were also partly built on foundations that may not hold.
Start with earnings. The Q4 diluted EPS of $0.72 included a $0.52 per-share benefit tied to the expected recovery of IEEPA tariffs, a one-off recovery of previously paid import duties. Strip that out and the underlying adjusted EPS falls to roughly $0.20.
That $0.20 still beat the LSEG consensus of $0.13, so the underlying business did clear a low bar. But $0.20 is a far weaker earnings base than $0.72, and it is the number that reflects how the company actually traded.
Nike’s fiscal 2026 fourth-quarter results, published directly by the company, confirm the $0.52 per-share IEEPA tariff recovery benefit embedded in the $0.72 reported EPS, a disclosure that makes the adjusted $0.20 underlying figure the only reliable baseline for assessing operational earnings power.
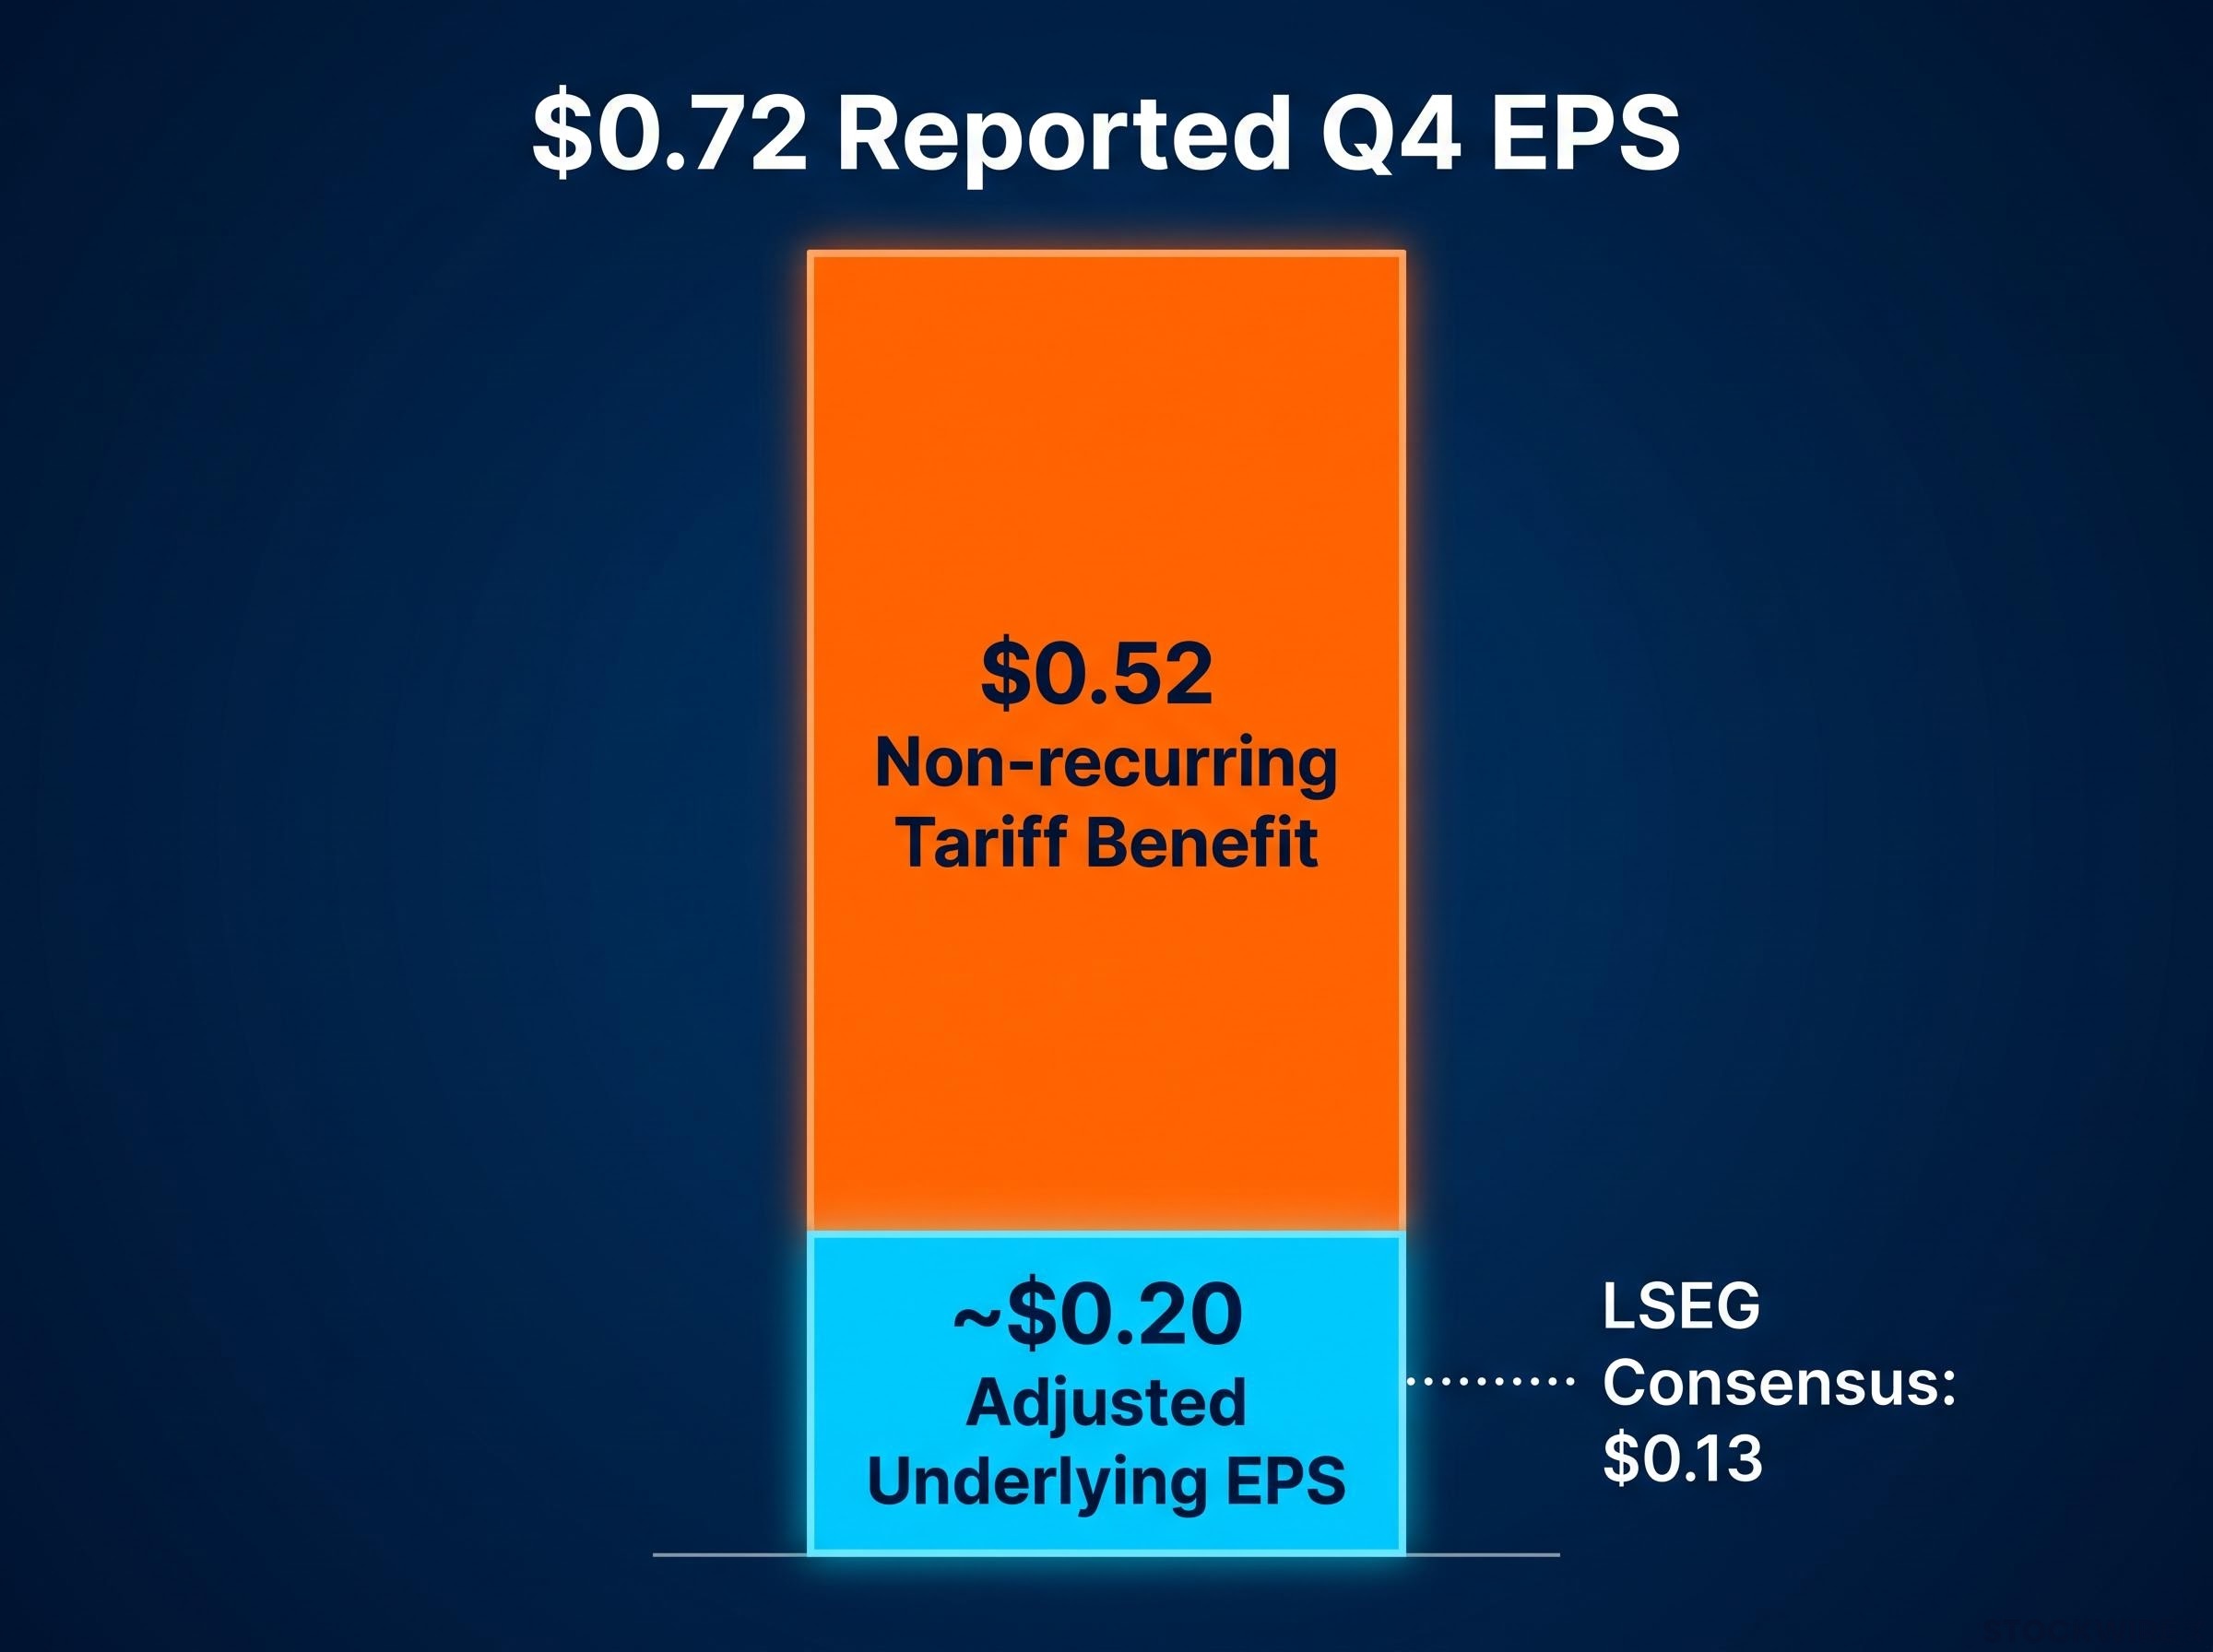
| Earnings component | Q4 FY2026 | Nature |
|---|---|---|
| Reported diluted EPS | $0.72 | Reported |
| Tariff-recovery benefit | $0.52 | Non-recurring |
| Adjusted EPS | ~$0.20 | Underlying |
The same caution applies to the gross margin, which expanded 890 basis points to 49.2%. That is a striking number, but the drivers were lower ocean freight and logistics costs alongside the same tariff benefit. Freight relief is cyclical and can reverse; the tariff benefit is policy-contingent and one-off.
What to watch in tonight’s gross margin disclosure
A sustainable margin improvement looks different from a freight-and-tariff-driven one. The signal to hunt for is whether channel-mix improvement and pricing power are contributing, not just cost relief that could vanish next quarter.
Watch management’s commentary on whether freight and tariff tailwinds are expected to persist into the next fiscal period. If the margin is holding up only because of transitory cost relief, that is not structural profitability.
Here is why this matters to how you value the stock. If you read the $0.72 headline without stripping out the $0.52 tariff benefit, you are looking at an earnings-power picture that is likely to look significantly worse once those tailwinds fade. Distinguishing operating leverage from accounting tailwinds is the difference between a durable recovery signal and a one-quarter distortion.
Five signals that will define the market’s reaction tonight
Forget predicting the headline. Your job tonight is to watch the right variables, the ones that reliably signal whether Hill’s turnaround is gaining traction or stalling. Here are the five, each with what a positive and a concerning reading looks like.
- Greater China. Watch whether the constant-currency decline narrows from the 17% Q4 level. A smaller decline signals stabilisation taking hold; a wider decline confirms the brand-erosion problem is still deepening.
- Nike Direct. Watch whether the 6% full-year decline shows signs of levelling off. Stabilisation suggests the premium channel is finding a floor; further deterioration means the margin engine keeps bleeding.
- Adjusted EPS quality. Watch whether the underlying number, excluding tariff and freight benefits, improves on the roughly $0.20 Q4 baseline. Genuine operating improvement is bullish; another quarter propped up by one-offs is a warning.
- Wholesale momentum. Watch whether the 6% growth rate holds or accelerates, particularly in North America. Sustained or faster growth confirms the rebuild is working; a slowdown would undercut Hill’s clearest success to date.
- Management guidance and tone. Watch whether Hill issues any forward numerical targets or stays cautious and qualitative. Concrete guidance would signal genuine confidence; continued vagueness suggests management still cannot see a clear path.
The single most important signal tonight is probably not the headline revenue number. It is the China constant-currency figure. If that decline widens again, the structural brand-erosion thesis is still intact, regardless of what the headline beats or misses.
This framework turns tonight’s release from an information event into a decision tool. Investors who know what to look for are positioned to act on the underlying data rather than react to the first headline that crosses the wire.
What tonight’s report actually changes for Nike investors
One earnings report will not settle the turnaround question. What it can do is sharpen the picture, and the honest read is that both the bull case and the bear case remain live.
The two sides, side by side:
- Bull case: Wholesale growth of 6% with reported double-digit North America gains (flagged as unverified in the research); adjusted Q4 EPS of $0.20 beating the $0.13 consensus; a share price down more than 44% that may already reflect the worst.
- Bear case: Greater China deepening to a 17% constant-currency decline; Nike Direct down 6% with no clear floor; Q4 margin and EPS strength leaning on non-recurring tariff and freight tailwinds.
A single quarter can provide directional signals on China and Nike Direct. What it cannot do is prove a recovery. A credible turnaround thesis requires several consecutive quarters of improvement, not one beat against lowered expectations.
Nike’s valuation at depressed multiples of approximately 1-2 times sales sits at a level that has historically signalled either deep value or a value trap, with the distinction hinging entirely on whether margin recovery and revenue stabilisation materialise across multiple consecutive quarters rather than a single beat.
Here is the framing to leave with. After a 44% decline and 18 years of index membership erased, Nike is now a turnaround story, not a blue-chip hold. That distinction raises the standard of evidence you should demand before adding or maintaining exposure.
At this valuation, the market has already priced in significant bad news. The risk-reward calculus now hinges on whether tonight delivers the first concrete evidence of stabilisation, not a full reversal, which no single report could credibly provide anyway.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors, and forward-looking assessments remain speculative and subject to change based on market developments and company performance.