
Spokane contract worth A$11 million and H1 FY27 EBITDA guidance
COSOL Limited (ASX: COS) has announced a 10-year Spokane Transit Authority contract worth approximately A$11 million to the company, secured in partnership with IBM. In the same update, dated 12 November 2026, the company outlined its H1 FY27 EBITDA guidance as the benefits of an internal restructure start to take effect.
The headline items from the update are:
- Contract: 10-year Spokane Transit Authority (STA) contract, worth approximately A$11 million to COSOL
- H1FY27 EBITDA: Statutory EBITDA anticipated at $3.3m to $3.6m, and underlying EBITDA anticipated at $3.6m to $3.9m
- Dividend: Resumption of payments targeted following H1FY28, payable in H2FY28
When big ASX news breaks, our subscribers know first
What the Spokane Transit Authority contract delivers
The win came through the Americas division, which Interim Chief Executive Officer Anthony Stokes said has won significant new contracts. The Spokane agreement was signed just this week.
Contract terms
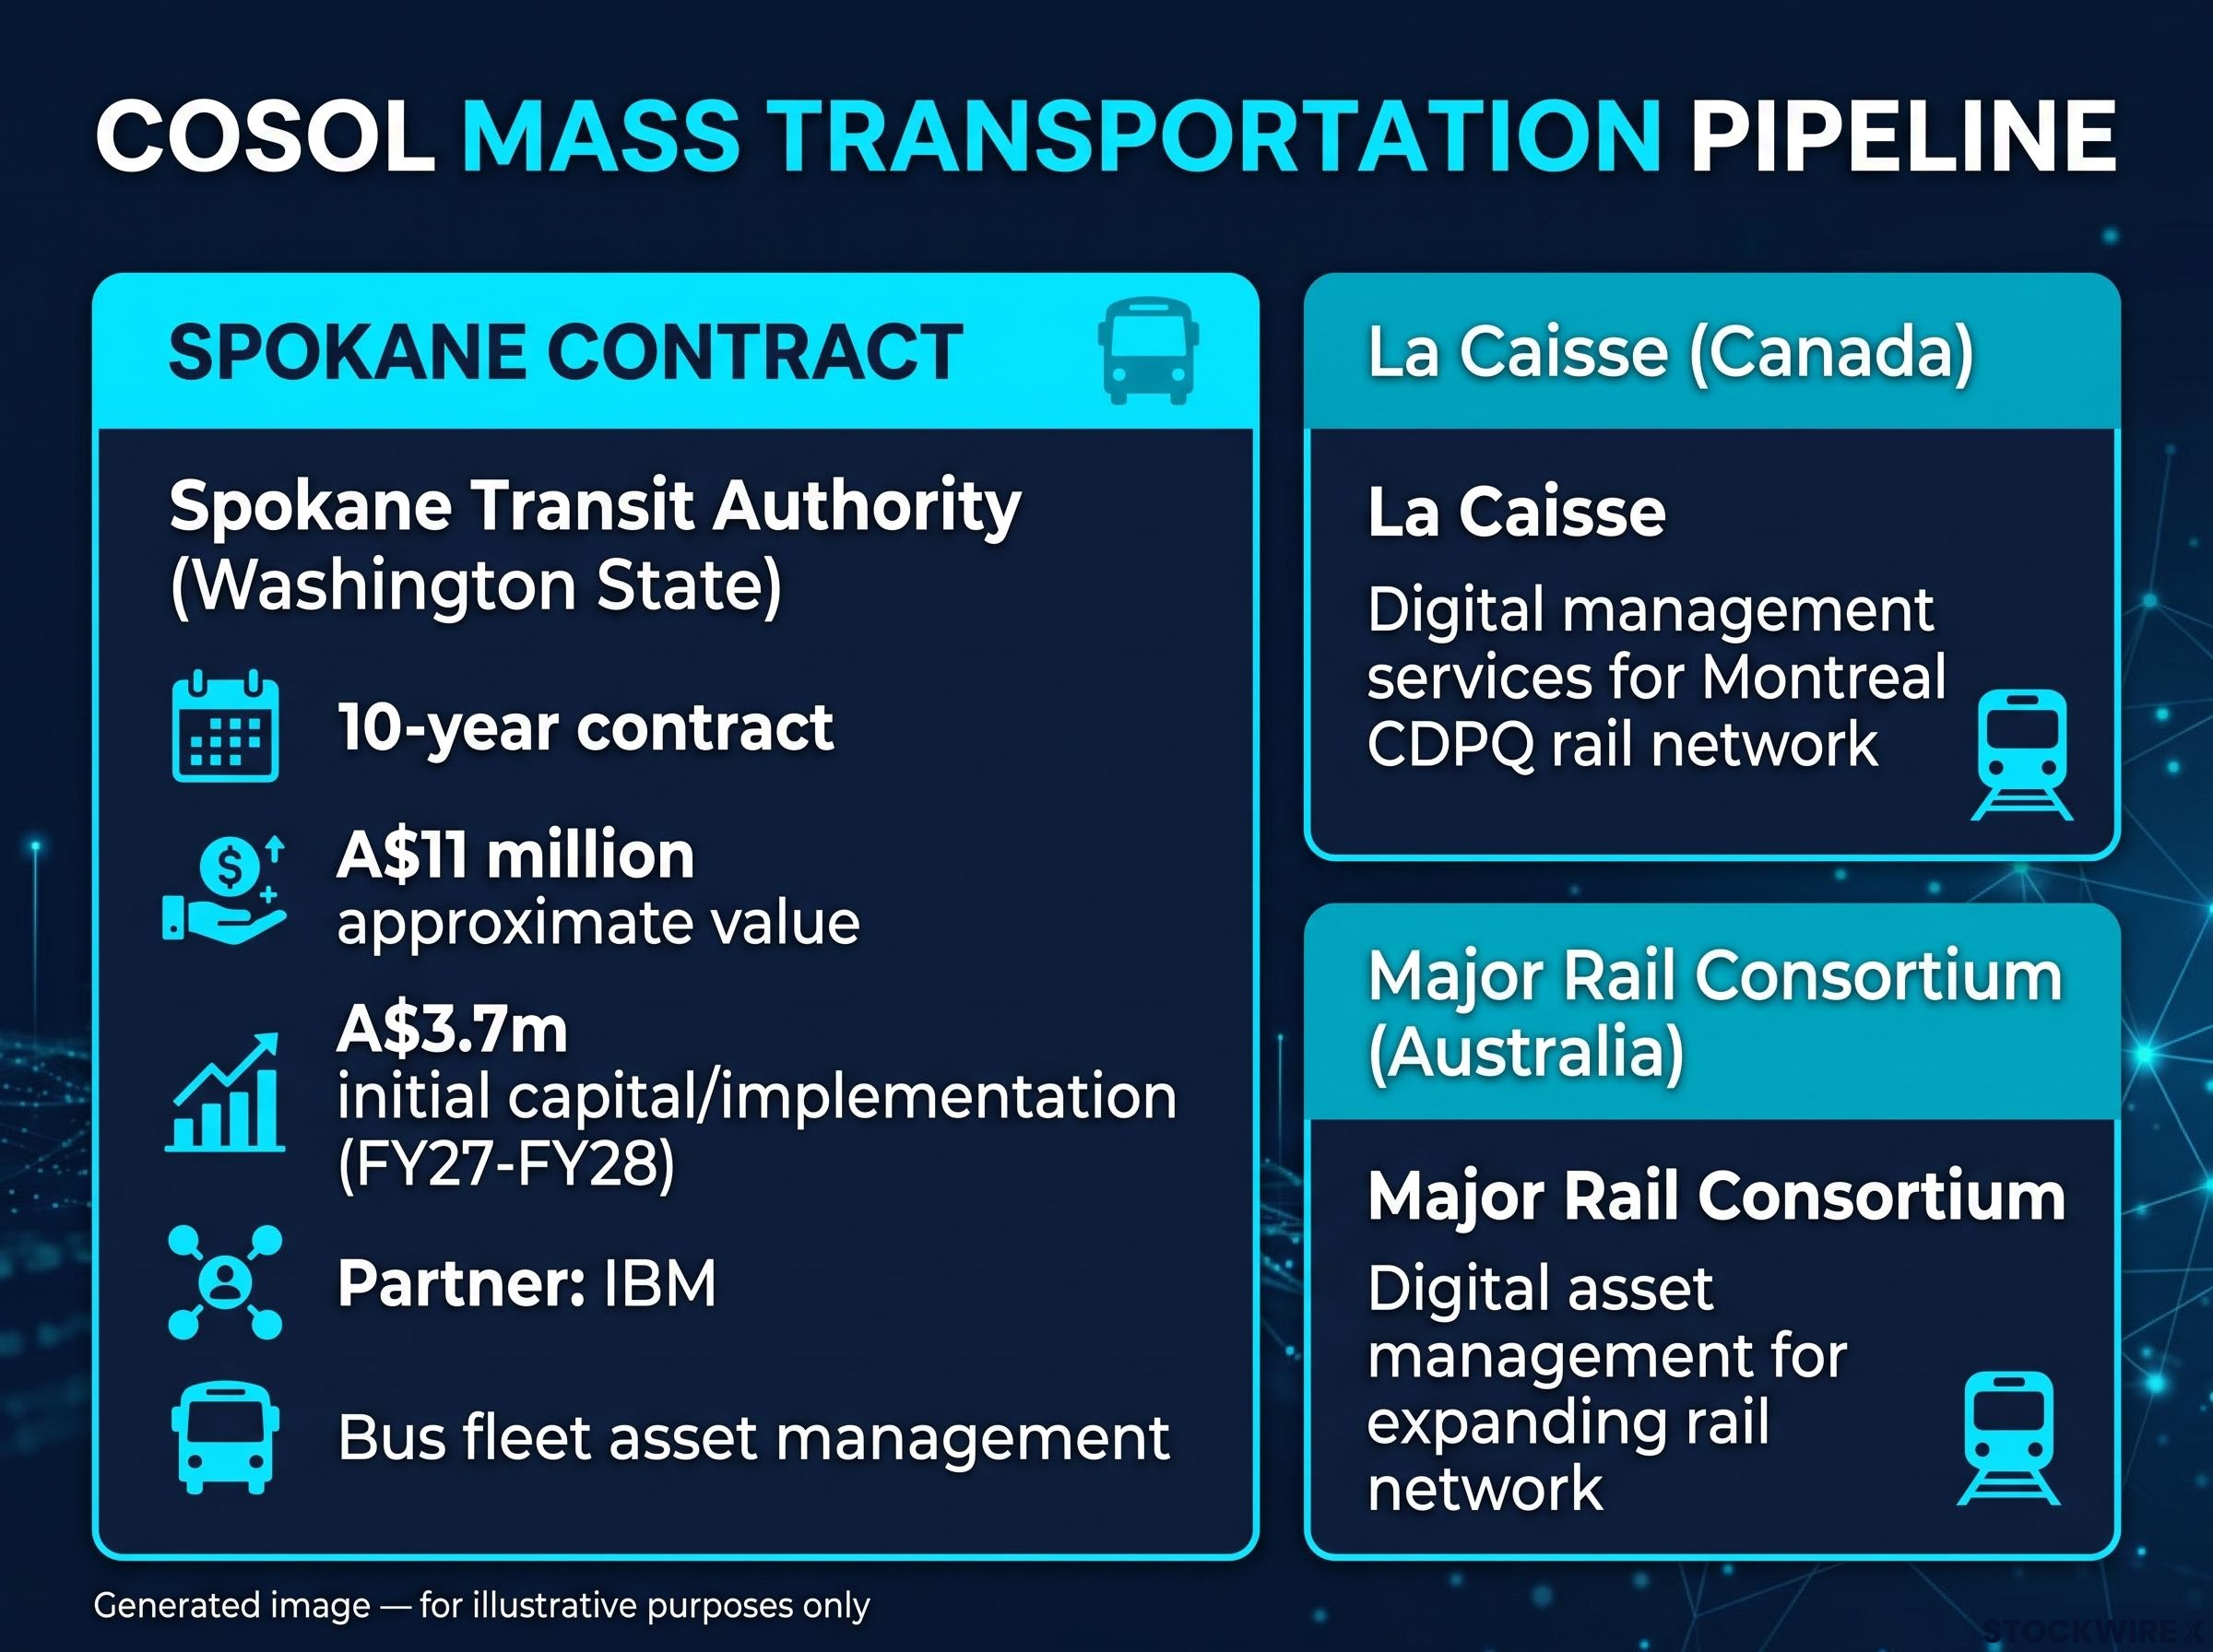
- 10-year contract in Washington State
- Approximate value to COSOL of A$11 million
- Initial capital spend and implementation component, over FY27 and FY28, accounting for A$3.7m of the total
- Secured in partnership with IBM
STA has contracted COSOL to deliver and manage software that will support the optimisation, management, monitoring and maintenance of its physical assets, notably its bus fleet.
A growing mass transportation pipeline
The contract is a significant endorsement of COSOL’s fast-growing mass transportation segment, according to the company. It cites burgeoning demand for ‘live’ digital management of physical assets to strengthen reliability, financial stewardship and long-term operational performance.
The Spokane win follows two contracts secured earlier this year:
- La Caise, a giant Canadian fund, for digital management services for its Montreal CDPQ rail network
- A major rail consortium in Australia, for digital asset management of its expanding network
Mr Stokes said the Spokane contract underlined the quality of COSOL’s digital asset management services and its ability to sell into a highly competitive and sophisticated market such as the US.
Several further opportunities are being actively pursued to deliver similar digital asset services in each of the mass transportation, infrastructure and energy sectors in Australia and the US.
H1 FY27 earnings outlook
Guidance at a glance
Revenue for the first half is expected to be in line with H1FY26, with improvements in statutory and underlying EBITDA. Underlying EBITDA excludes restructuring costs of approximately $0.3m.
| Measure | H1FY27 expected | Movement vs H1FY26 |
|---|---|---|
| Statutory EBITDA | $3.3m to $3.6m | Improvement of ~$0.7m |
| Underlying EBITDA (excludes restructuring costs of ~$0.3m) | $3.6m to $3.9m | n/a |
| Revenue | In line with H1FY26 | n/a |
Restructure benefits flowing through
Mr Stokes said the internal reset of the business, led by a business-wide cost-cutting exercise in H2FY26, was starting to show impact. COSOL expects the margin improvement to carry through to H2, with resumption of revenue growth on the back of several new contracts in the transportation and infrastructure sectors.
COSOL’s FY26 results showed the reset already feeding through, with second-half EBITDA of $6.3m against $3.5m in the first half and EBITDA margin up 570 basis points to 12.8%.
On the Australian consulting business, Mr Stokes said:
Anthony Stokes, Interim Chief Executive Officer
“We expect to regain momentum in the Australian consulting business through the rest of this financial year, with continued focus on cost management and a target to improve operating margins by 150 points as higher margin revenue from AI and proprietary IP-driven contracts flows through.”
Strategy and what happens next
Commercial focus
Digital asset management uses software to track, monitor and maintain physical assets such as vehicle fleets and rail networks. In capital intensive industries with complex asset networks, such as mass transportation, infrastructure and energy, reliability and financial performance leave little room for failure.
Long-term, higher margin engagements in these sectors support earnings quality. Mr Stokes said:
Anthony Stokes, Interim Chief Executive Officer
“It has become clear to us that opportunities in the mass transportation, infrastructure and energy sectors is where COSOL should put its major commercial focus…”
What happens next for COSOL
- The Spokane initial capital spend and implementation phase runs over FY27 and FY28.
- Margin improvement is expected to carry through to H2 FY27, with revenue growth resuming on new transportation and infrastructure contracts.
- COSOL is targeting an operating margin improvement of 150 points over the rest of this financial year, as higher margin revenue from AI and proprietary IP-driven contracts flows through.
- Dividend payments are targeted to resume following H1FY28, payable in H2FY28, with continued recovery of earnings per share through H2 and into the following financial year.
Want Alerts Like This on the Technology Stocks You Follow?
StockWire X Market Intelligence scores every announcement in our coverage for how significant it’s likely to be for investors, and which way it points, then alerts you on the stocks you follow. The first 1,000 founding members lock in 50% off for life: A$247 a year instead of the standard A$495. Join the founding waitlist today.