
Xero outlines H1 FY27 momentum and lifts FY27 outlook
In its H1 FY27 investor presentation for the six months ended 30 September 2026, Xero (ASX: XRO) outlined operating revenue of $1,745m, up 46% reported and 27% pro-forma. Pro-forma means performance as if Xero and Melio were combined for the full comparison periods.
Management highlighted adjusted EBITDA of $362m (+3% reported, +23% pro-forma) and pro-forma free cash flow of $238.1m (+32%). The two headline items were an upgraded FY27 Outlook and an up to A$1bn on-market buy-back.
Customers reached 5.15m, up 12% reported. Chief Executive Officer Sukhinder Singh Cassidy’s “3×3” strategy focuses on Accounting, Payments and Payroll across Australia, the UK and the US.
| H1 FY27 metric | Reported growth | Pro-forma growth |
|---|---|---|
| Operating revenue | +46% | +27% |
| Adjusted EBITDA | +3% | +23% |
| Free cash flow | -26% | +32% |
When big ASX news breaks, our subscribers know first
Growth across Australia, the UK and the US
The company detailed revenue growth and net customer additions by market:
- Australia: revenue +23%, with +91k net customer additions.
- UK: revenue +24%, with +85k net customer additions. MTD for IT drove 16% customer growth.
- US: revenue +51% pro-forma, with +31k customers and strong pro-forma customer growth of 18%.
In the US, pro-forma revenue was $365m. Melio payments revenue reached $283m, up 38% year on year, and Bill Pay is live alongside Xero Payroll powered by Gusto.
Average revenue per customer (ARPC) was $62.21, up 25%, with a Melio contribution of $5.81. Payments and other revenue made up 22% of pro-forma revenue, from 19% in H1 FY26.
Pro-forma gross margin was 76.0%, which the company said was largely driven by mix as Melio payments revenue grows. Operating expenses were 68.6% of operating revenue, excluding M&A costs.
AI adoption building at scale
Xero’s AI features include Auto Bank Rec, which automates bank reconciliation, JAX, its chat assistant, and Smart Doc Capture, which reads documents. The presentation noted that Xero small business and accountant customers are not billed by seats.
- Roughly 1m customers used GenAI features on a rolling 12-month basis.
- Monthly active organisations grew about 9x year on year.
- About 90% of Auto Bank Rec users were return customers.
- XeroForce is in beta with more than 100 workflows.
- Customers using Xero via AI assistants such as Claude, ChatGPT and Copilot grew about 40% month on month.
Xero’s earlier AI monetisation plan framed the shift from a system of record to a system of action, and the JAX engagement data it cited set the baseline against which this half’s adoption figures can be read.
Upgraded guidance, FY28 aspirations and the A$1bn buy-back
FY27 Outlook
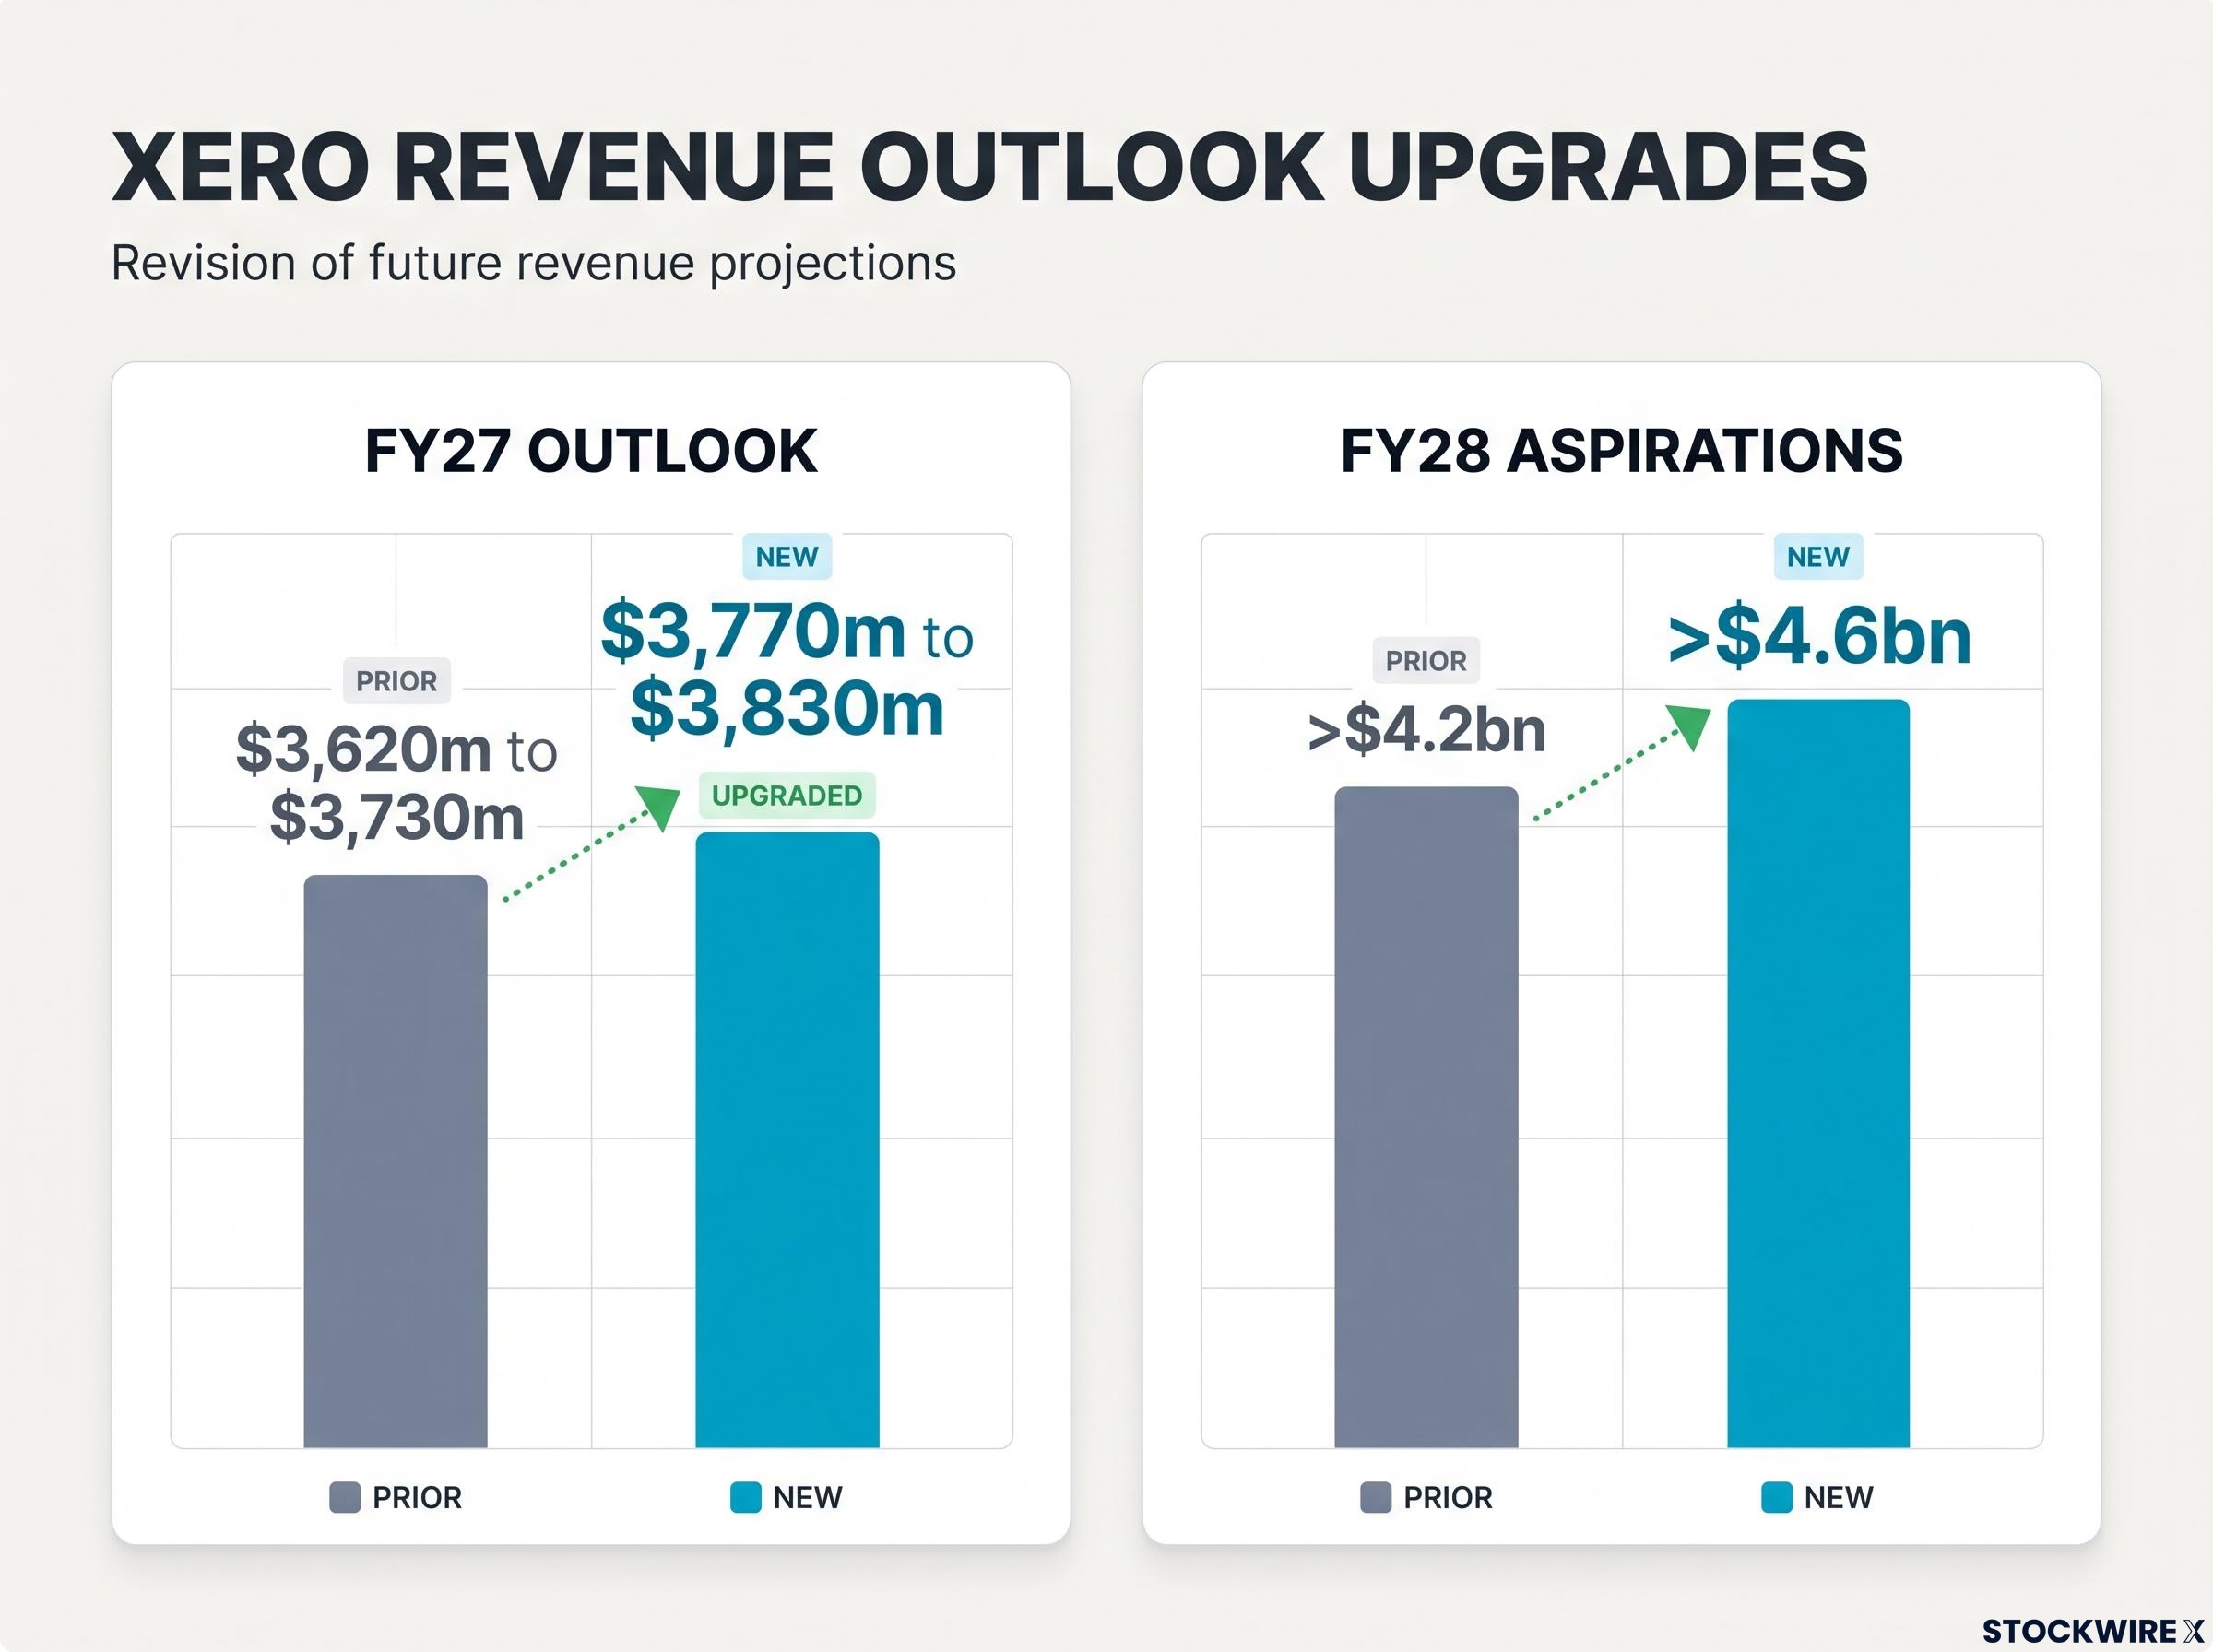
- Operating revenue is now expected at $3,770m to $3,830m (prior $3,620m to $3,730m), reflecting stronger Melio payments performance and an FX benefit from the weaker NZD.
- Adjusted EBITDA is expected at $880m to $920m, with a higher than historical H2 weighting.
- A Rule of 40 outcome of around 40% is expected on a pro-forma basis, earlier than the previous aspiration.
FY28 aspirations
Xero now sees the opportunity for FY28 revenue of more than $4.6bn, excluding revenue synergies, up from more than $4.2bn. Melio is expected to reach adjusted EBITDA breakeven on a run-rate basis in H2 FY28, and the aspiration remains a greater than Rule of 40 outcome in FY28.
For readers wanting to trace how the FY28 aspiration was first set, our detailed coverage of Xero’s FY28 revenue ambition and Melio integration explains the original doubling target, the US$70 million revenue synergy case and the strategic logic behind the US payments push.
Balance sheet and capital return
The buy-back is up to A$1bn over a 12-month program and includes an amount intended to offset dilution from share-based compensation expected for FY28. The Board believes the current share price does not reflect Xero’s long-term value and growth potential.
Net debt was $843.9m at Sep-26 versus $383.4m at Mar-26, and net debt to pro-forma adjusted EBITDA was 1.1x. The completed A$550m dilution offset program involved a $664m outflow.
The remaining US$200m of the revolving credit facility was paid down after 30 September, and the facility is now fully undrawn.
What happens next for Xero
- The H1 FY27 earnings webcast was set for 10:00am AEDT on 12 November 2026, with a replay on Xero’s Investor Centre.
- Xero plans to notify shareholders in writing and release a separate standalone disclosure document on the ASX explaining the on-market buy-back.
- The H2 FY27 pro-forma adjusted EBITDA guide is $518m to $558m, with price rises in New Zealand and the US expected to come through in H2 ARPC and revenue.
- Melio run-rate adjusted EBITDA breakeven is expected in H2 FY28.
Want Alerts Like This on the Technology Stocks You Follow?
StockWire X Market Intelligence scores every announcement in our coverage for how significant it’s likely to be for investors, and which way it points, then alerts you on the stocks you follow. The first 1,000 founding members lock in 50% off for life: A$247 a year instead of the standard A$495. Join the founding waitlist to claim your spot.