
Q3 2026 trading update: novated leasing settlements up 31%
Smartgroup Corporation reported that Q3 2026 total novated leasing settlements, which include refinanced vehicles, rose 31% versus the prior corresponding period (pcp). Novated leasing orders, excluding refinanced vehicles, increased 33% versus pcp.
The company expects CY2026 NPATA of $92-94M and CY2026 capex of $13-15M, as announced with its 2026 half-year results. NPATA is net profit after tax, adjusted to exclude non-cash tax-effected amortisation of intangibles and significant non-operating items.
In Q3 2026, 73% of battery electric vehicle (BEV) new-vehicle orders were below $75k and 83% were below $80k.
Headline Q3 2026 figures:
- Total novated leasing settlements (including refinanced): +31% vs pcp
- Novated leasing orders (excluding refinanced): +33% vs pcp
- CY2026 NPATA: expected at $92-94M
- CY2026 capex: expected at $13-15M
Scott Wharton, Managing Director and CEO
“We are pleased with the Group’s performance in the third quarter, with continued momentum across the business. Despite broader economic uncertainty, demand for novated leasing remains robust, with significant opportunities to grow participation across salary packaging, novated leasing and fleet…”
Record customer numbers across all key product lines
Smartgroup recorded growth across salary packaging, novated leasing and fleet. Figures below run from CY 2023 to Q3 2026.
- Active salary packages: 524,000, up 32%
- Novated leases under management: 98,000, up 60%
- Fleet managed vehicles: 36,300, up 19%
The company retained all significant clients during the period and secured new clients. Customers per operations full-time equivalent (FTE) employee reached 2,036 in Q3 2026, up 17% versus pcp.
When big ASX news breaks, our subscribers know first
Leasing momentum and the shift to electric vehicles
Volume growth came alongside stable direct yield. The table sets out Q3 2026 against pcp.
| Measure | Q3 2026 v pcp |
|---|---|
| New lease vehicle orders | +33% |
| Total settlement volume | +31% |
| New lease vehicle settlement | +38% |
| Refinance vehicle settlement | -11% |
| Direct Yield (yield from direct operations, excludes partnerships) | +3% |
Refinance vehicle settlements fell 11%. Total settlement volume includes new, used and refinance.
The order mix moved sharply towards electric vehicles between CY 2025 and Q3 2026:
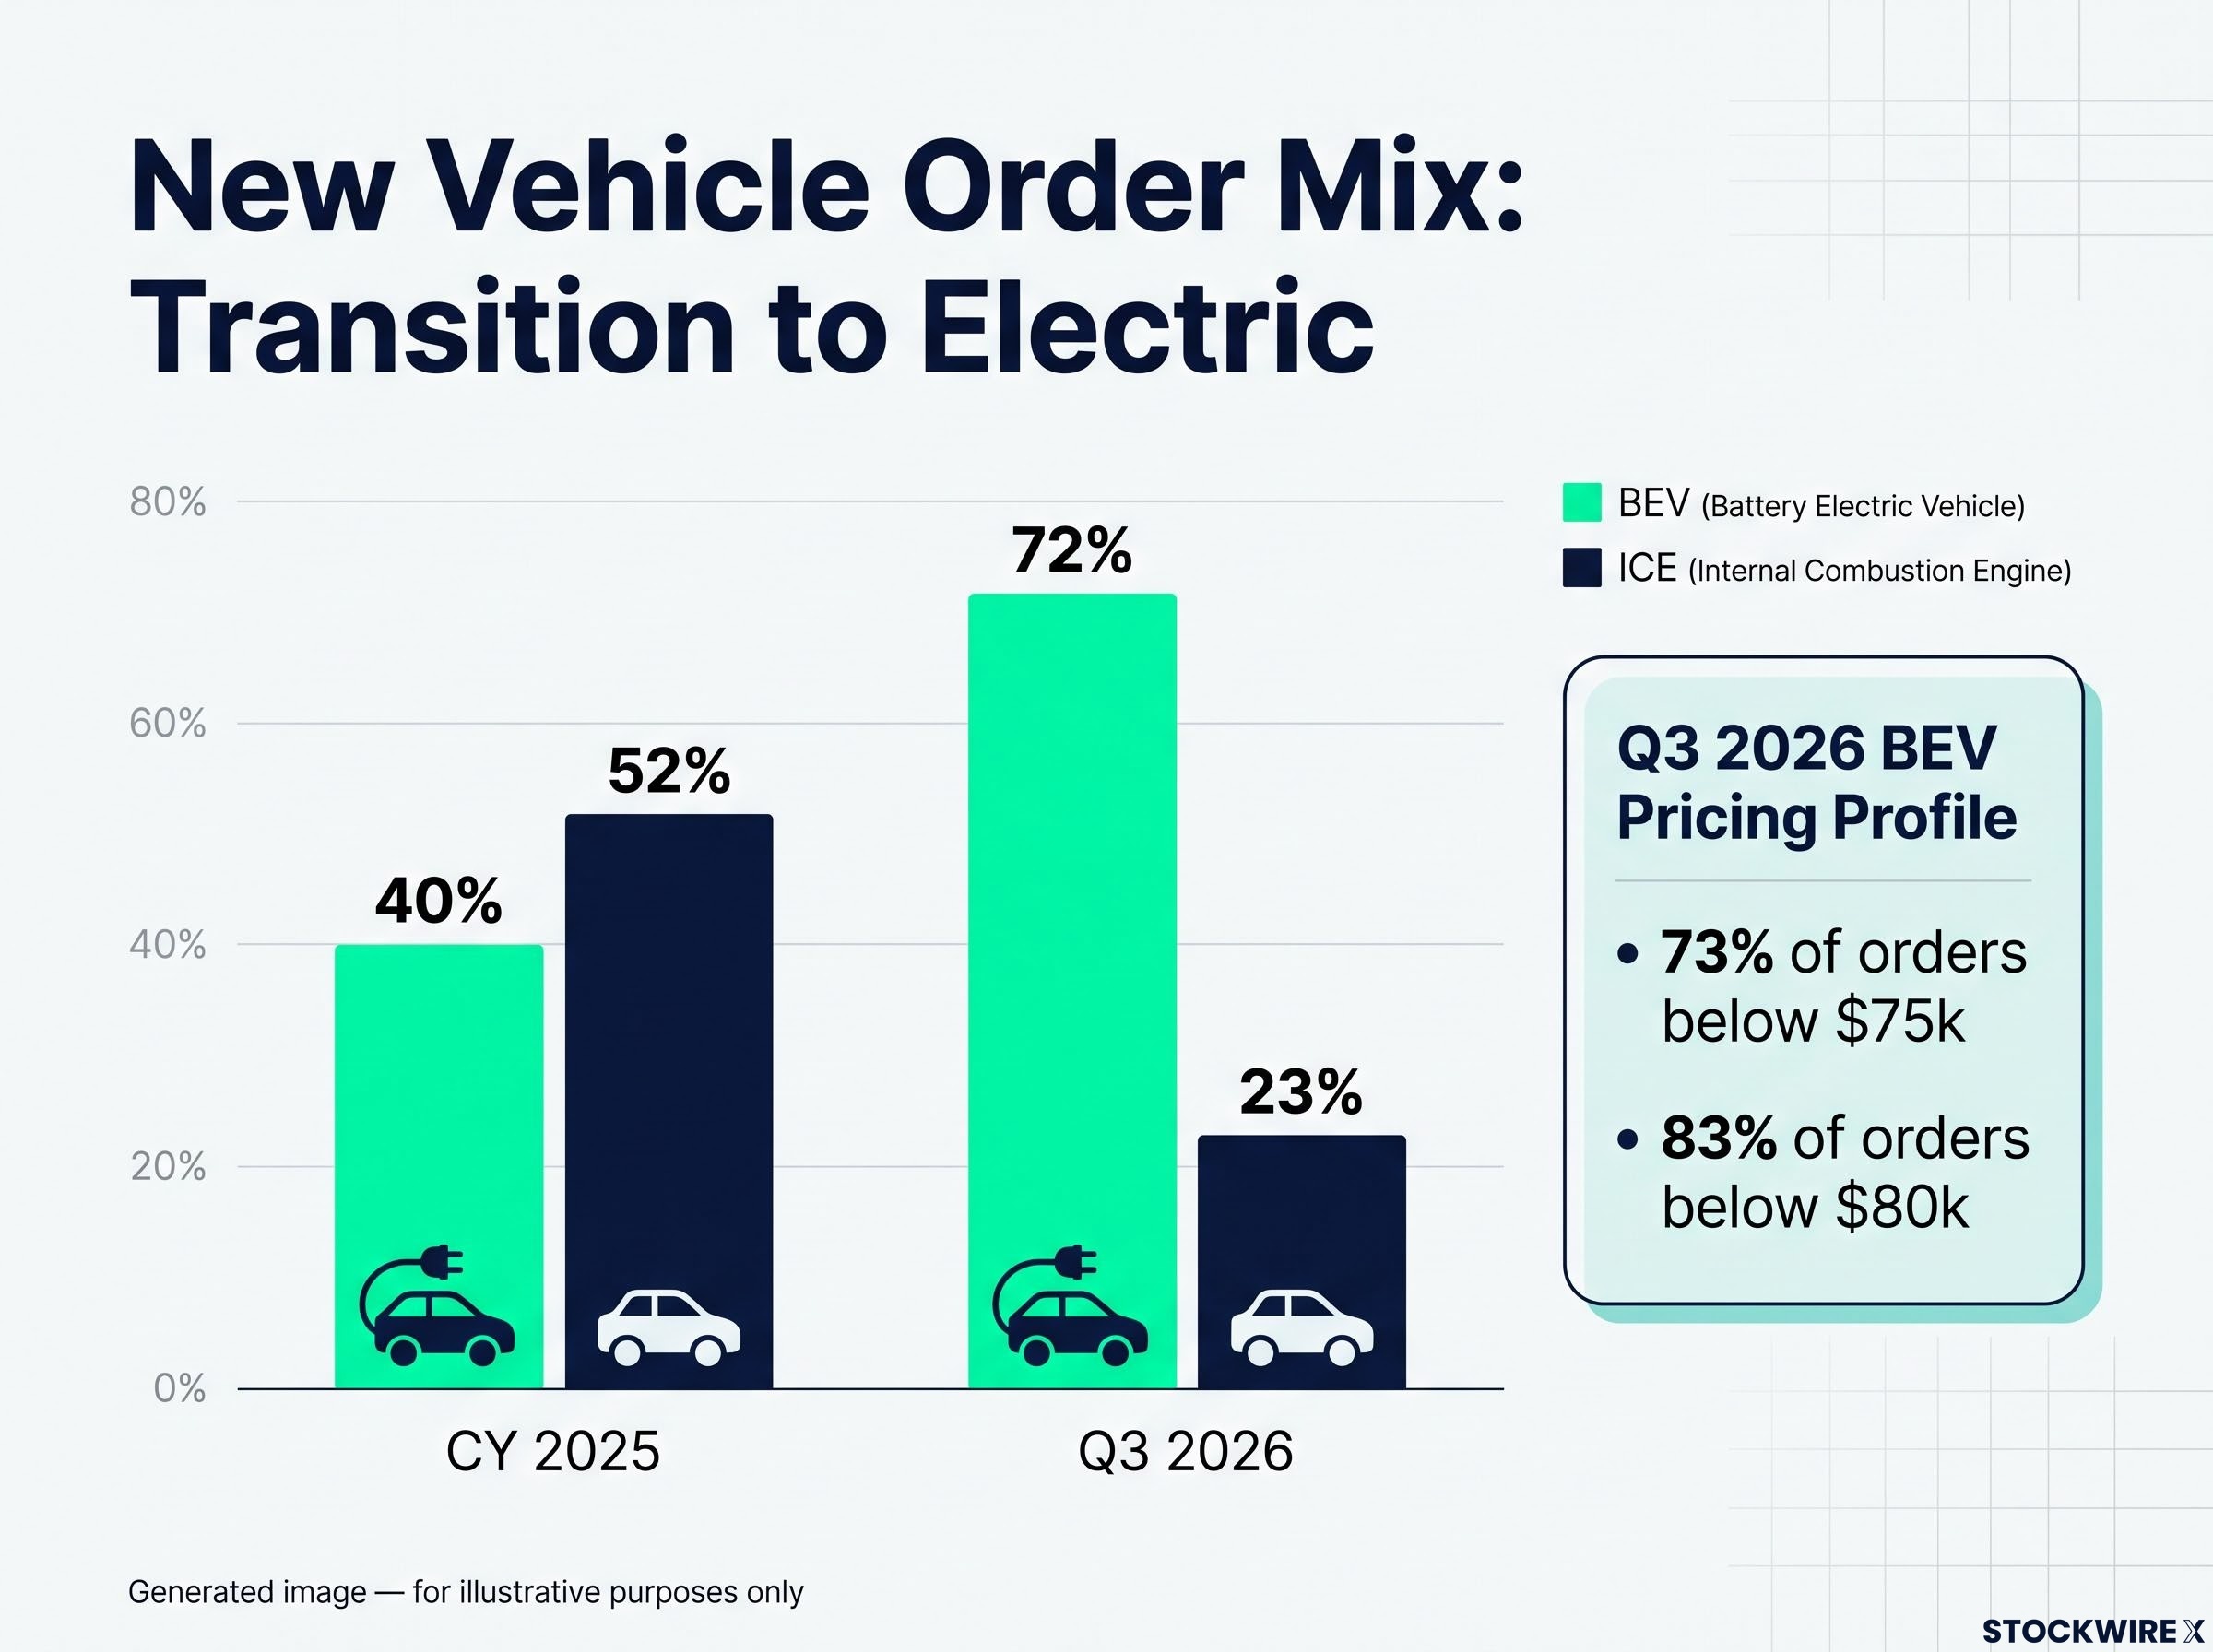
- BEV share of new vehicle orders rose from 40% to 72%
- ICE (internal combustion engine) share fell from 52% to 23%
- Average vehicle order to delivery timeframe was 35 days in Q3 2026, compared with 29 days in H1 2026
The source states that elevated fuel prices are strengthening the economic case for electric vehicles and supporting demand.
Smartgroup’s pipeline of future revenue was c.$17.9M at the end of September 2026, down from $22.5M in June 2026.
Partnerships and platform progress
Smartgroup expanded distribution through new partnerships with BYD, Hyundai, Genesis, Mahindra and AutoLeague.
The AccessPay migration progressed, supporting the transition to a single Smart brand, and a new Smart brand campaign was activated. The fleet pipeline expanded through new client wins and growth within existing clients, with continued momentum in fleet funding supported by a capital-light funding offering.
Strategy delivering scale: the numbers behind the platform
Salary packaging lets employers offer employees a way to pay for eligible expenses through their pay. A novated lease applies that approach to a vehicle, with the employee, employer and lessor involved.
Smartgroup describes its platform as capital-light, generating strong cash flow without residual value exposure. Residual value is the estimated worth of a vehicle at the end of a lease, and carrying that risk can tie up capital.
The company’s HY26 metrics:
- EBITDA margin: 41%
- Cash conversion: 120% (as a percentage of NPATA)
- Leverage: 0.2x
- Revenue CAGR (3 years): 15%
- Potential customers within the existing client base: c.2.5M
Smartgroup positions itself as #1 in salary packaging and novated leasing, based on publicly available customer numbers.
Smartgroup’s H1 2026 results also covered capital management, including a $20m buyback and a fully franked interim dividend of 21.5 cents per share.
| Measure ($M) | CY 2023 (total) | CY 2024 (total) | CY 2025 (total) | H1 2026 |
|---|---|---|---|---|
| Revenue | 251.6 | 305.8 | 329.3 | 179.5 |
| EBITDA | 100.3 | 118.7 | 135.3 | 73.8 |
| NPATA | 63.2 | 72.4 | 80.2 | 42.4 |
Efficiency has improved alongside scale. Customers per operations FTE rose from 1,389 in 2023 to 1,837 in HY26, and to 2,036 in Q3 2026.
The transformation programme is also simplifying the business. The company is rationalising its multiple legacy brands to a target of one (“Smart”) by CY28. Compute in cloud infrastructure reached 85%, up from 45% in CY25, with a target of 100% by CY28.
Outlook: reinvestment now, mid-40s margin targeted in 2027
Smartgroup expects CY2026 NPATA of $92-94M. Consistent with H1, and given current favourable operating conditions, it is deliberately accelerating reinvestment in H2 to strengthen the platform for scalable growth.
The company anticipates H2 EBITDA margin to be similar to H1. It continues to target an EBITDA margin in the mid-40s range during 2027, based on current market conditions and the transformation programme progressing to plan.
Scott Wharton, Managing Director and CEO
“As we move into the next phase of our strategy, we are focused on unlocking new growth opportunities. This includes expanding partnerships with automotive manufacturers and dealer groups, and growing our fleet business through our differentiated capabilities and technology platform…”
What to watch
Items stated in the announcement and presentation:
- CY2026 NPATA of $92-94M
- CY2026 capex of $13-15M
- H2 EBITDA margin anticipated to be similar to H1
- EBITDA margin targeted in the mid-40s range during 2027
- A single Smart brand and 100% of compute in cloud infrastructure, targeted by CY28
Stay Ahead on the Next Industrials Trading Update
Join 20,000+ investors getting FREE breaking ASX news delivered to their inbox within minutes of release, with in-depth analysis already done. Click the “Free Alerts” button at Big News Blast to receive real-time alerts the moment market-moving announcements break, before the wider market catches up.