
Service Stream to acquire Programmed for $975 million with $475 million equity raising
Service Stream is set to buy Programmed, with its wholly-owned subsidiary Service Stream Holdings Pty Ltd entering a binding share sale agreement with PERSOL Asia Pacific Pte Ltd (Persol) to acquire 100% of the issued shares of PERSOL Australia Holdings Pty Ltd and PERSOL APAC Business Support Services Sdn. Bhd (together with their subsidiaries, Programmed). The purchase price is $975 million, implying an Enterprise Value of $1,092 million.
The Programmed acquisition is funded in part by a fully underwritten $475 million equity raising at $2.03 per share. The Acquisition is expected to deliver EPS-A accretion exceeding 20% on a pro forma FY27F basis, including $30 million of run-rate cost synergies.
Completion is expected on or around 1 March 2027, subject to receipt of ACCC approval and other customary closing conditions.
Key deal figures, before any adjustments for debt and debt-like items or any purchase price reduction:
- Purchase price: $975 million
- Implied Enterprise Value: $1,092 million
- EV / LTM Jun-26 EBITDA: 7.4x before synergies, or 6.1x after initial run-rate cost synergies of $30 million
- EPS-A accretion: mid-single digit on a pre-synergies basis
The Acquisition (Service Stream buying Programmed from Persol) and the Equity Raising (the funding) are separate transactions, and their figures are set out separately below.
Leigh Mackender, Managing Director
“The acquisition of Programmed marks a significant and exciting milestone in Service Stream’s journey, bringing together two businesses with highly complementary capabilities…”
Mackender also pointed to “the proven integration and operating approach that underpinned the success of the Lendlease Services acquisition and subsequently improved Service Stream’s financial performance.”
Price adjustments
The $975 million purchase price is subject to customary completion adjustments for working capital and agreed debt and debt-like items, estimated at $65 million.
The price may be reduced by up to $25 million through a post-completion adjustment if Programmed does not achieve a prescribed EBITDA hurdle for the financial year ending 31 March 2027. The Enterprise Value includes Programmed lease liabilities of $117 million as at 30 June 2026.
When big ASX news breaks, our subscribers know first
What Programmed brings to Service Stream
Programmed provides integrated asset maintenance, facility management and resourcing solutions to government and Tier 1 asset owners and operators across Australia and New Zealand. In plain terms, it looks after the upkeep and running of buildings, infrastructure and industrial sites, and supplies staff to do so.
Key facts about the business:
- Established in 1951
- About 5,000 active customers
- About 200 locations
- About 6,600 employees and a pool of about 8,000 specialist contractors
- Four operating segments: Facility Management, Property Services, Industrial Maintenance and Staffing
Programmed has a work-in-hand position of about $3.8 billion, with an additional ~$2.7 billion in extension options, reflecting work-in-hand in the Facility Management division as at May 2026. Within Facility Management, about 73% of revenue is associated with operations and maintenance contracts, and about 27% is exposed to lower-risk minor capital works.
Service Stream’s recent Transport for Victoria contracts, covering intelligent transport systems maintenance on road and motorway networks, point to the kind of recurring, essential-service work that sits alongside Programmed’s operations and maintenance base.
Service Stream sets out the strategic rationale as follows. The Acquisition:
- Enhances Service Stream’s capabilities
- Expands Service Stream’s Total Addressable Market
- Materially diversifies operations and provides enhanced earnings resilience
- Is a highly synergistic transaction
- Delivers sustainable value creation and earnings improvement opportunities to be realised
For investors, the company says the diversification significantly reduces Service Stream’s exposure to any single market, client or contractual agreement.
Combined financials, synergies and balance sheet
The combined group’s FY26 pro forma revenue was approximately $6,155 million. EBITDA from Operations was approximately $312 million before synergies, or $342 million including the full estimated annual run-rate synergies.
Of the $30 million of initial run-rate cost synergies, about 50% are expected within 18 months of Completion and 100% within 36 months. One-off integration costs are estimated at approximately $35 million, while Acquisition and Offer transaction costs are estimated at $40 million, excluding one-off integration costs.
Net debt / FY26 pro forma EBITDA is expected to be 2.2x at Completion, reducing to approximately 1.5x within 24 months. To assist with debt reduction, Service Stream intends to maintain a dividend quantum per share in line with FY26 for a period of up to 24 months, subject to the financial performance and capital requirements of the combined group.
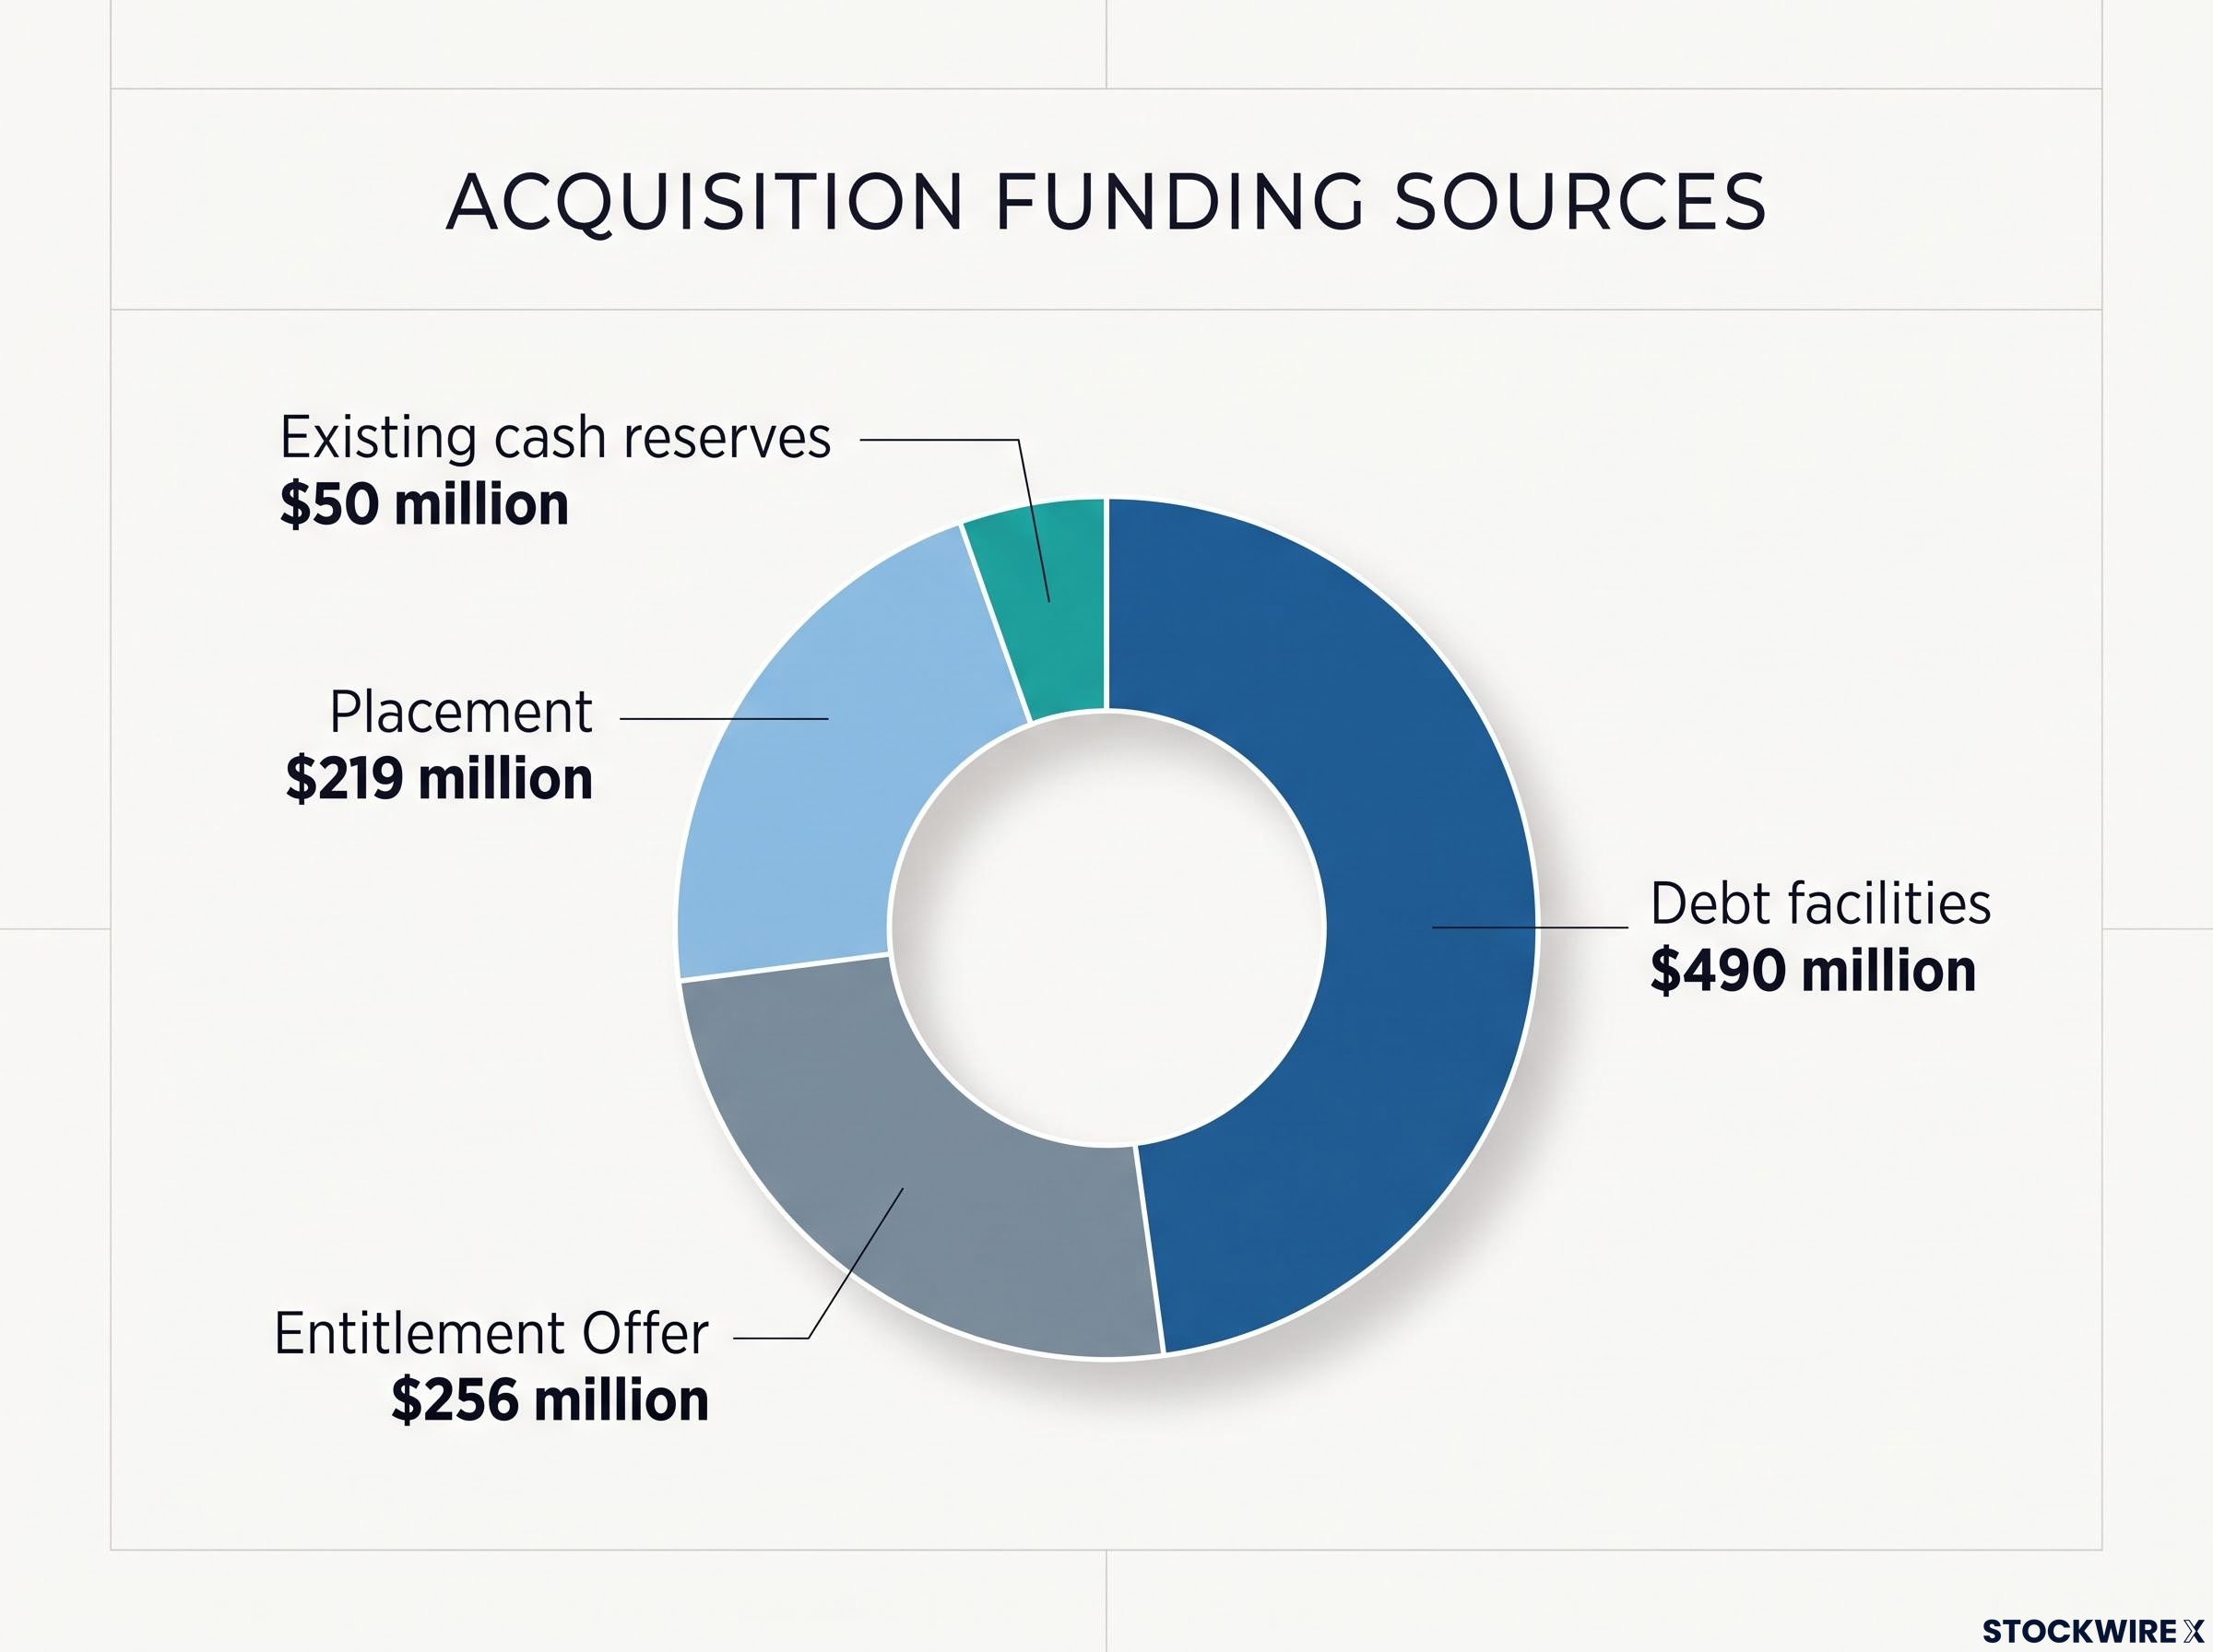
The Acquisition and associated transaction costs will be funded as follows:
| Source | Amount | Detail |
|---|---|---|
| Placement | $219 million | Fully underwritten institutional placement |
| Entitlement Offer | $256 million | Fully underwritten 1 for 4.9 pro rata accelerated non-renounceable offer |
| Debt facilities | $490 million | Existing facilities increased from $395 million to $895 million |
| Existing cash reserves | $50 million | n/a |
Service Stream also reaffirmed that FY27 is expected to deliver a step change in revenue and earnings growth on FY26 across existing operations. It reported a solid start in Q1 FY27, with utility operations on track to deliver incremental margin improvement over the full year and defence operations providing increased confidence of the same.
How the $475 million equity raising works
All shares under the Offer will be issued at $2.03, a 5.7% discount to the theoretical ex-rights price (TERP) of $2.15 and a 7.7% discount to the last closing price of $2.20 on 6 November 2026. About 234 million New Shares will be issued, equivalent to approximately 37.8% of existing ordinary shares, and they will rank equally with existing fully paid ordinary shares from their date of issue.
The fully underwritten Placement of approximately $219 million is offered to sophisticated and professional investors by way of a bookbuild on 9 November 2026, with approximately 108 million New Shares to be issued.
The fully underwritten Entitlement Offer of approximately $256 million is a 1 for 4.9 pro rata accelerated non-renounceable offer, with a Record Date of 7pm on Wednesday 11 November 2026. Entitlements are not tradeable on the ASX or otherwise transferable, and shareholders who do not take up their full entitlement receive no payment or value for them and will have their percentage equity interest diluted.
Retail details:
- Eligible retail shareholders must have a registered address in Australia or New Zealand on the Record Date
- Those who take up their full entitlement may apply for additional New Shares under a Top-up Facility, up to a maximum of 100% of their entitlement
- Allocation under the Top-up Facility is at Service Stream’s discretion
All eligible Director shareholders and Key Management Personnel shareholders intend to participate in the Entitlement Offer. UBS Securities Australia Limited is sole lead manager, bookrunner and underwriter.
Key dates for shareholders
The timetable is indicative only and subject to change without notice.
- Monday 9 November 2026: webcast briefing at 10:30am (AEDT); trading halt, and Placement and Institutional Entitlement Offer open
- Tuesday 10 November 2026: Placement and Institutional Entitlement Offer close, results announced, and trading halt lifted with shares recommencing trading on an “ex-entitlement” basis
- Wednesday 11 November 2026: Record Date for Entitlement Offer
- Monday 16 November 2026: Retail Information Booklet dispatched and Retail Entitlement Offer opens (9am)
- Wednesday 18 November 2026: settlement of Placement and Institutional Entitlement Offer
- Thursday 19 November 2026: allotment and normal trading of New Shares under the Placement and Institutional Entitlement Offer
- Friday 27 November 2026: Retail Entitlement Offer closes (5pm AEDT)
- Wednesday 2 December 2026: results of Retail Entitlement Offer announced
- Thursday 3 December 2026: settlement of New Shares under the Retail Entitlement Offer
- Friday 4 December 2026: allotment of New Shares under the Retail Entitlement Offer
- Monday 7 December 2026: normal trading of New Shares issued under the Retail Entitlement Offer
- Tuesday 8 December 2026: dispatch of holding statements for New Shares issued under the Retail Entitlement Offer
- On or around 1 March 2027: Completion of the Acquisition, subject to receipt of ACCC approval and other customary closing conditions
Don’t Miss the Next Industrials Deal Before the Market Moves
Join 20,000+ investors getting FREE breaking ASX news delivered to their inbox within minutes of release, complete with in-depth analysis. Click the “Free Alerts” button at Big News Blast to receive the full announcement and expert coverage the moment market-moving news breaks.