Sterling has been one of the better-performing major currencies in October, gaining nearly 2% against the euro and reaching a 17-month high against it. Yet by 28 October, GBP/USD had slipped to about $1.3298, even though a Bank of England (BoE) rate hike on 5 November is close to certain.
That gap is the key to the pound sterling outlook. A near-certain hike should, in theory, keep lifting the currency. It has not, and the reason matters more than the hike itself.
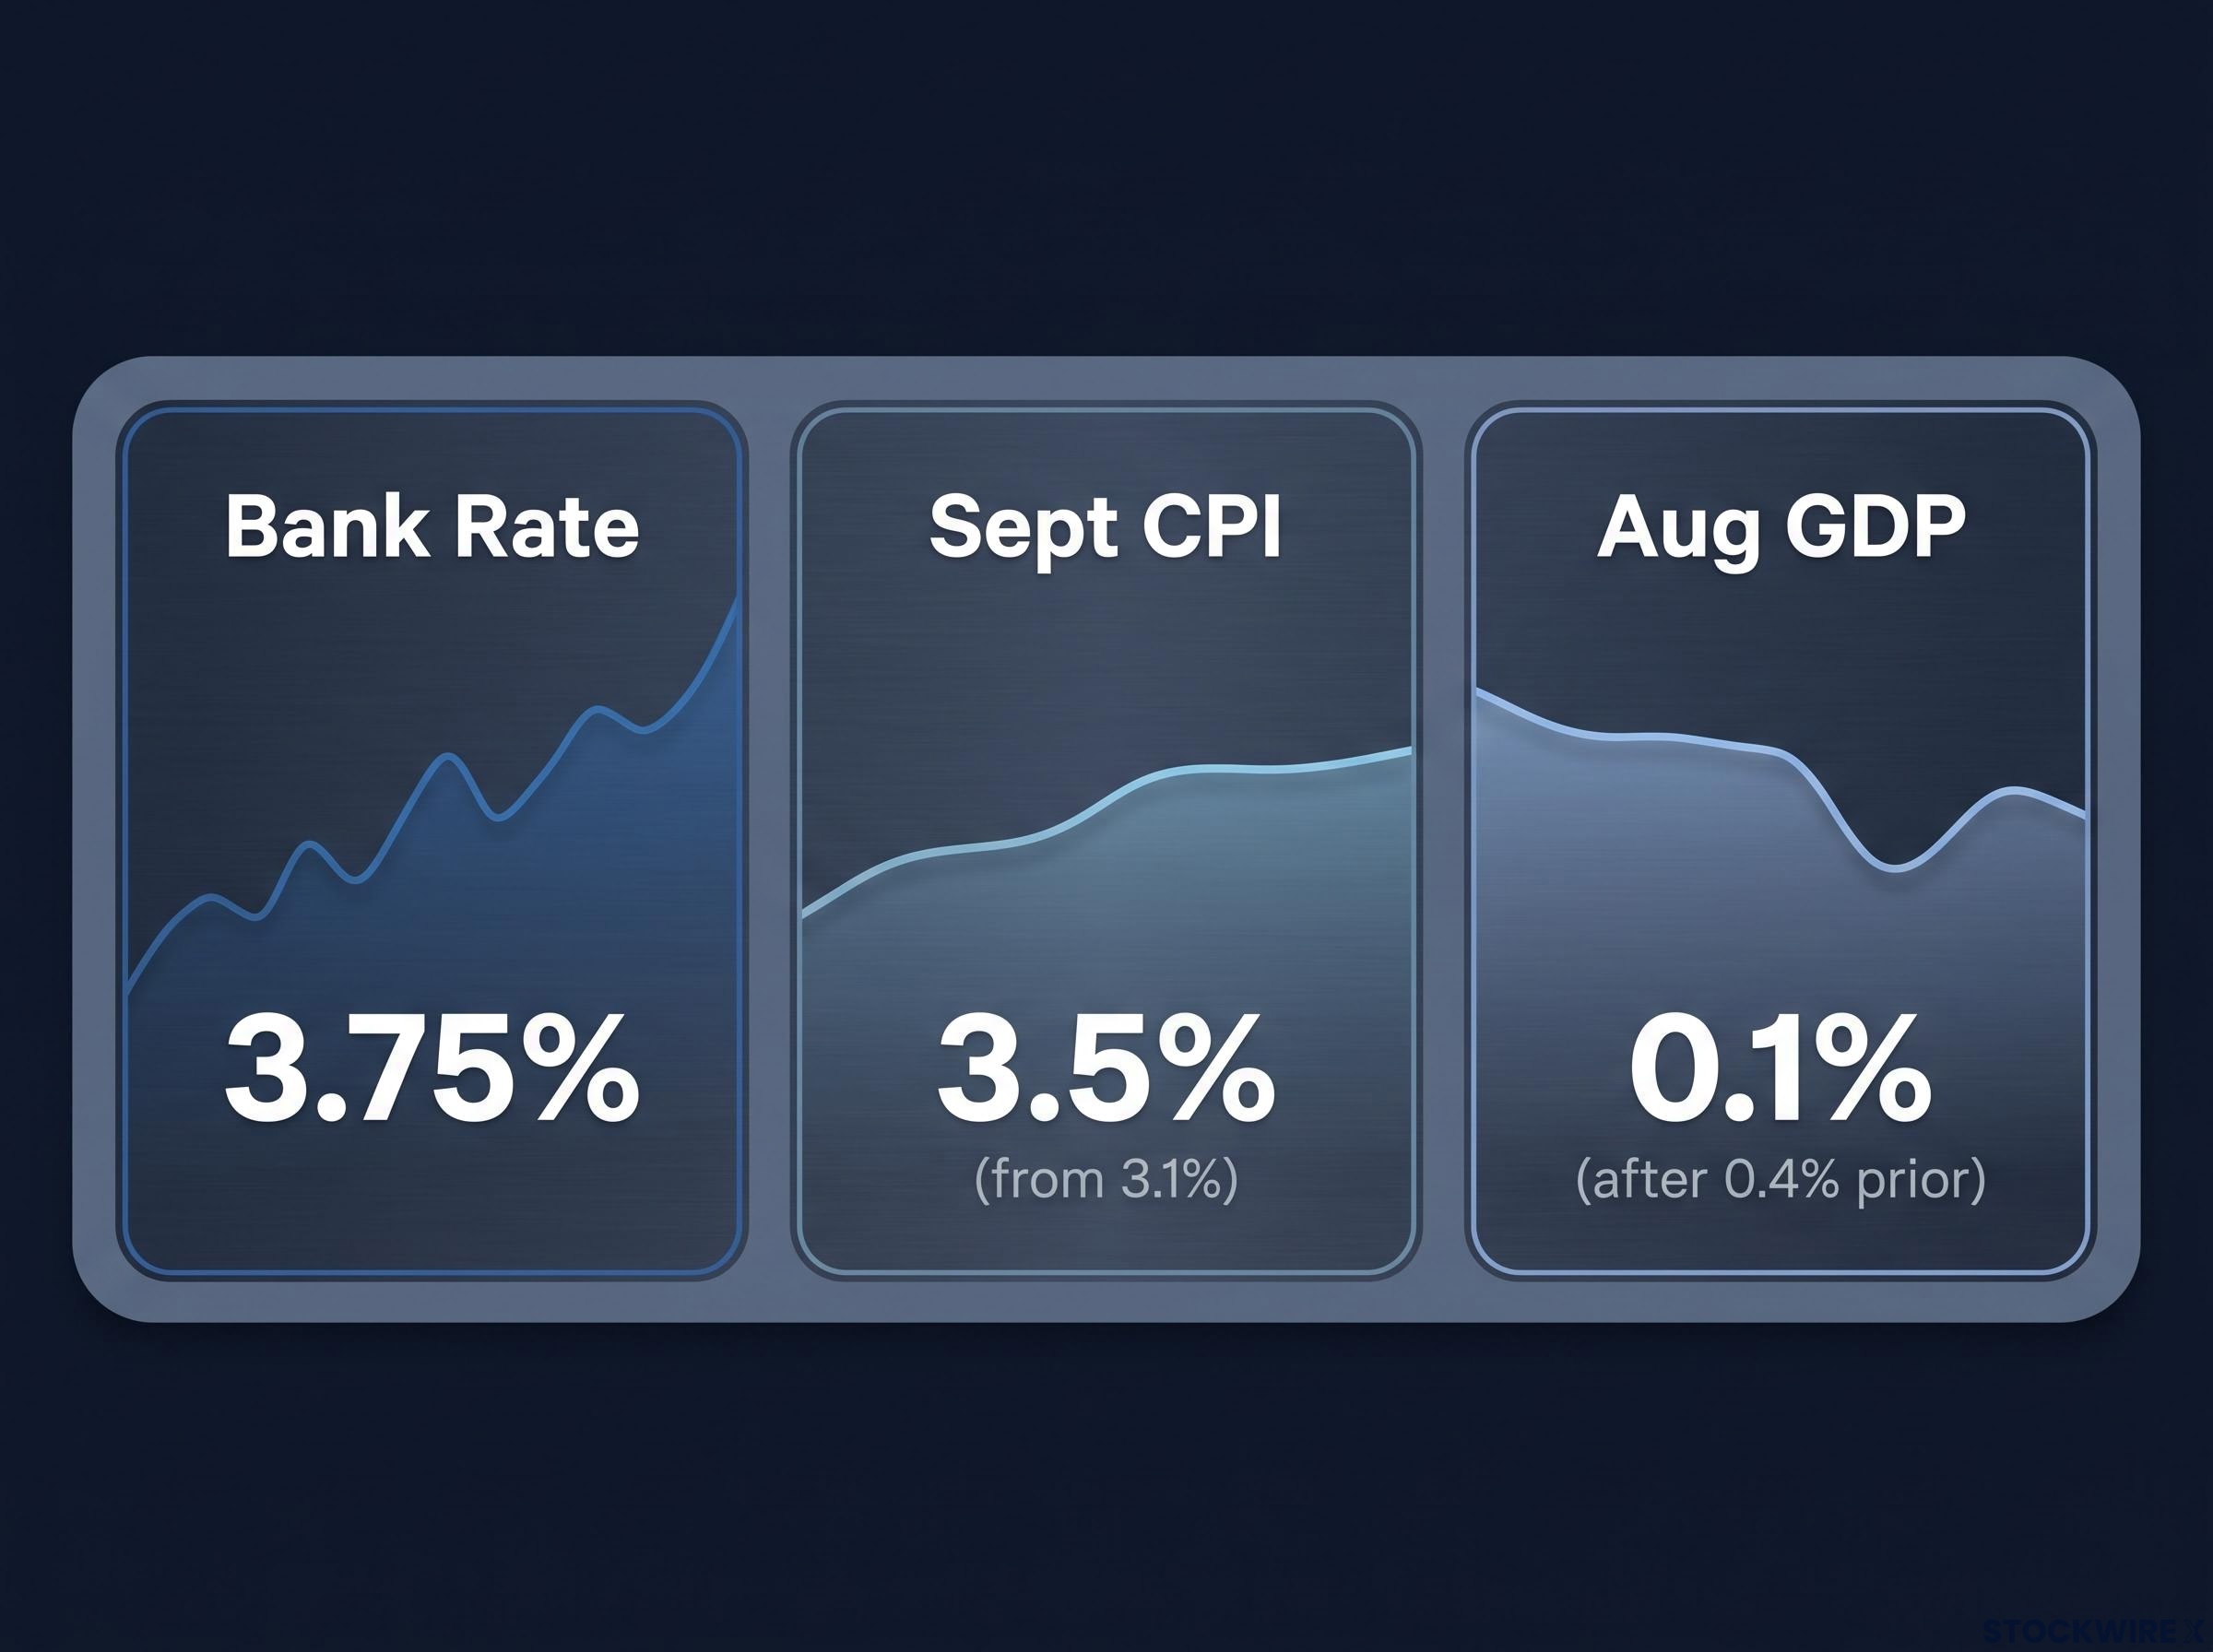
Bank Rate sits at 3.75% after a 6-3 Monetary Policy Committee (MPC) hold, with three members voting to raise it. The Budget kept to the government’s fiscal rules. OCBC strategists Sim Moh Siong and Christopher Wong argue that fiscal and political support for the Pound is genuine, but that a heavy tightening cycle is already in the price.
After reading this, you will know what markets have already priced, what would need to surprise for sterling to climb further, and which signals deserve your attention over the coming weeks.
Why is the Pound holding up when the easy gains look spent?
The case for sterling starts with discipline. OCBC points to contained fiscal risks, a stable political backdrop and growth that held up better than expected. Sterling has done well even though higher energy costs, linked to the Middle East conflict, are straining public finances.
The data has backed that up. September CPI inflation, the official measure of how fast consumer prices are rising, jumped to 3.5% from 3.1%. Monthly GDP grew 0.1% in August after 0.4% gains in each of the two prior months, a slowdown but not a stall.
The strength is also relative. Sterling has risen about 1.8% against the euro year-to-date, helped by a euro weighed down by French fiscal and political concerns. Against the dollar, the picture is more two-sided.
| Pair | Latest level (28 Oct) | October move | Key driver |
|---|---|---|---|
| EUR/GBP | 0.8372 | Sterling up nearly 2% | French fiscal worries, wider UK rate advantage |
| GBP/USD | $1.3298 | Sterling up about 1% | BoE hike expectations, offset by profit-taking |
Then comes the turn. Every one of those positives is already visible on the screen.
OCBC’s core view Sterling’s support is real, but a substantial BoE tightening cycle is already priced, so further gains need supportive data and actual BoE follow-through.
That is why OCBC moved its end-2026 EUR/GBP forecast from 0.89 to 0.87, shifting from bearish to neutral rather than outright bullish. Bloomberg-reported strategists go further, eyeing GBP/USD near $1.30 by year-end. What this tells you is that the good news is no longer a surprise; holding or adding sterling exposure now depends on new information, not the story you already know.
When big ASX news breaks, our subscribers know first
How do priced-in rate hikes cap a currency’s upside?
Picture a trader’s screen on decision day. The central bank raises rates exactly as forecast, and the currency barely moves, or even falls. Nothing went wrong. The move simply happened weeks earlier.
How markets price a hike before it happens
Currency traders do not wait for central banks to act. They use forward contracts and overnight index swap (OIS) curves, which are market instruments showing where traders expect interest rates to be on future dates. The spot exchange rate absorbs that expected path in advance.
Right now, markets price a near-certain 25 basis point hike in November, taking Bank Rate to about 4.00% (a basis point is one-hundredth of a percentage point). According to Reuters, they also price roughly three to four hikes by April to mid-2027, against about two from the European Central Bank. That widening gap in expected rates is what attracted money into sterling through October.
The market versus economist split on the November decision explains why pricing is so sensitive to guidance: traders lean on headline inflation, while many forecasters point to stable core readings as a reason to wait.
Once a move is fully expected, the old trading maxim applies: buy the rumour, sell the fact. Traders who bought sterling ahead of November may take profits when the hike lands as forecast.
The pricing rule Sterling’s reaction has depended on the gap between actual policy and prior expectations, not on whether rates are rising or falling.
One caveat on sources: the BoE’s own Market Participants Survey showed a median 3.75% expectation for 5 November, but it predates the stronger inflation and jobs data. Current market pricing is the better guide.
Why the terminal rate matters more than November
The terminal rate is the peak level a tightening cycle is expected to reach. If the BoE hikes but signals a cautious path beyond, later hikes come out of the curve and sterling can weaken despite a higher Bank Rate.
There are already cautious voices. BoE Chief Economist Huw Pill has been more sceptical than markets about four hikes, and ING argues that roughly 100 basis points of tightening by June may be too aggressive. With hikes priced, sterling needs one of four things to extend gains:
- A more hawkish BoE path than the curve implies
- Stronger UK data
- Falling rate expectations abroad
- A lower UK risk premium
For you, a hike that matches expectations is a neutral event. The real test is whether the path beyond November turns out steeper or shallower than priced.
What do fiscal headroom and growth forecasts tell you about sterling’s support?
If rate pricing sets the ceiling, fiscal credibility shapes the floor. Fiscal headroom is the margin by which the government is forecast to meet its own borrowing rules. Bond investors watch it because a thin margin raises the risk of extra borrowing, and currency traders follow the bond market.
The Office for Budget Responsibility (OBR) figures show a buffer that exists but has shrunk.
| Indicator | Latest | Previous | Why it matters |
|---|---|---|---|
| Headroom (2029/30) | £15bn | £23.6bn (March) | Smaller cushion against shocks |
| OBR 2026 growth | 1.2% | 1.1% | Supports near-term hikes |
| OBR 2027 growth | 1.0% | 1.6% | Limits how far the BoE can go |
| September borrowing | £24.5bn | Above expectations | Pressure on the buffer |
Headroom rises to £22bn in 2030/31, but the near-term figure is the one markets will test. The 30-year gilt yield briefly touched about 6% in early October, its highest since 1998, and debt-interest costs reached £10.9bn in September.
The long average debt maturity buffer means yield spikes feed through to the government’s actual interest bill slowly, which helps explain why a brief move in the 30-year gilt does not automatically force fiscal action.
The growth split cuts both ways. Better 2026 growth justifies hikes now, while a weaker 2027 suggests the BoE may struggle to deliver the full cycle priced. Fiscal credibility is an asset sterling holds but cannot afford to spend; a gilt sell-off or talk of unfunded policy could reopen a risk premium quickly.
The UK-EU channel: real, but slow
Closer UK-EU ties offer a medium-term tailwind through four channels:
- Trade and regulatory cooperation that could lift growth potential
- Less uncertainty to encourage foreign investment
- Lower political and trade friction, trimming the UK risk premium
- Improved confidence that supports gilts as well as sterling
Societe Generale argues that if inflation is controlled, a successful EU reset alongside rapid fiscal consolidation could make investors more positive on UK bonds and the Pound. The timing is the catch. This is a slow structural shift, not a substitute for near-term rate repricing.
What would GBP bulls need, and what could go wrong?
The fiscal picture leaves sterling supported but exposed. That turns the outlook into a checklist.
What bulls need to see
- BoE guidance on 5 November that signals follow-through beyond one hike
- Continued resilience in inflation and labour data
- A protected fiscal buffer, with gilt yields contained
- Ongoing progress in UK-EU relations
ING sees EUR/GBP moving toward 0.84-0.85. Against the dollar, Societe Generale identifies support near 1.3250 and resistance near 1.3430, levels you can use to gauge whether a post-decision move is gaining traction.
Where the thesis could break
The risks cluster around the decision itself and the economy beneath it. Petrol and diesel were the largest upward contributors to September’s 3.5% inflation, which pushes the BoE to act but also squeezes households. Berenberg’s Andrew Wishart has flagged weaker retail sales and consumer confidence as possible early signs of that squeeze.
Services inflation, private rents and catering prices have all re-accelerated independently of energy costs, which weakens the argument that the BoE can simply look through the fuel-driven rise in headline CPI.
| Scenario | BoE outcome | Likely GBP reaction | Why |
|---|---|---|---|
| Hawkish follow-through | Hike plus firm guidance | Supportive | Path steeper than priced |
| Hawkish disappointment | Hike, shallow guidance | Weaker | Later hikes priced out |
| Dovish surprise | Hold or soft vote | Sharply weaker | Near-certain move denied |
| Gilt stress | Any | Weaker | Fiscal risk premium returns |
The vote split is a live variable. Pill, Megan Greene and Catherine Mann already favoured a hike at the 6-3 hold, so a narrower majority for tightening in November would read as soft. Treat 5 November as the start of the test: the guidance and vote split matter more than the rate decision.
The research points to a modestly constructive near-term view against the euro and a more two-sided picture against the dollar. Gains into 2027 depend on more tightening than priced or a lower UK risk premium. These assessments are speculative and subject to change as data and policy develop.
What the priced-in cycle changes for sterling, and what it does not
Sterling’s fiscal, political and growth support has not gone anywhere. What has changed is the bar. With the tightening cycle largely in the price, good news needs to be better than expected to move the currency.
The near-term read remains modestly constructive against the euro and balanced against the dollar. Into 2027, the Pound needs either a steeper BoE path than markets assume or a meaningful fall in the UK risk premium.
Three signals will tell you which way it breaks:
- The 5 November vote split and forward guidance
- The next CPI and labour market releases
- Gilt yields measured against the £15bn headroom
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors.