Most pre-Budget commentary assumed the domestic lenders would escape the worst of any bank tax rise. The numbers now point the other way. Lloyds and NatWest, the two banks most tied to the UK economy, face the largest hit from the UK bank tax surcharge, and the Budget has now fixed how big that hit will be.
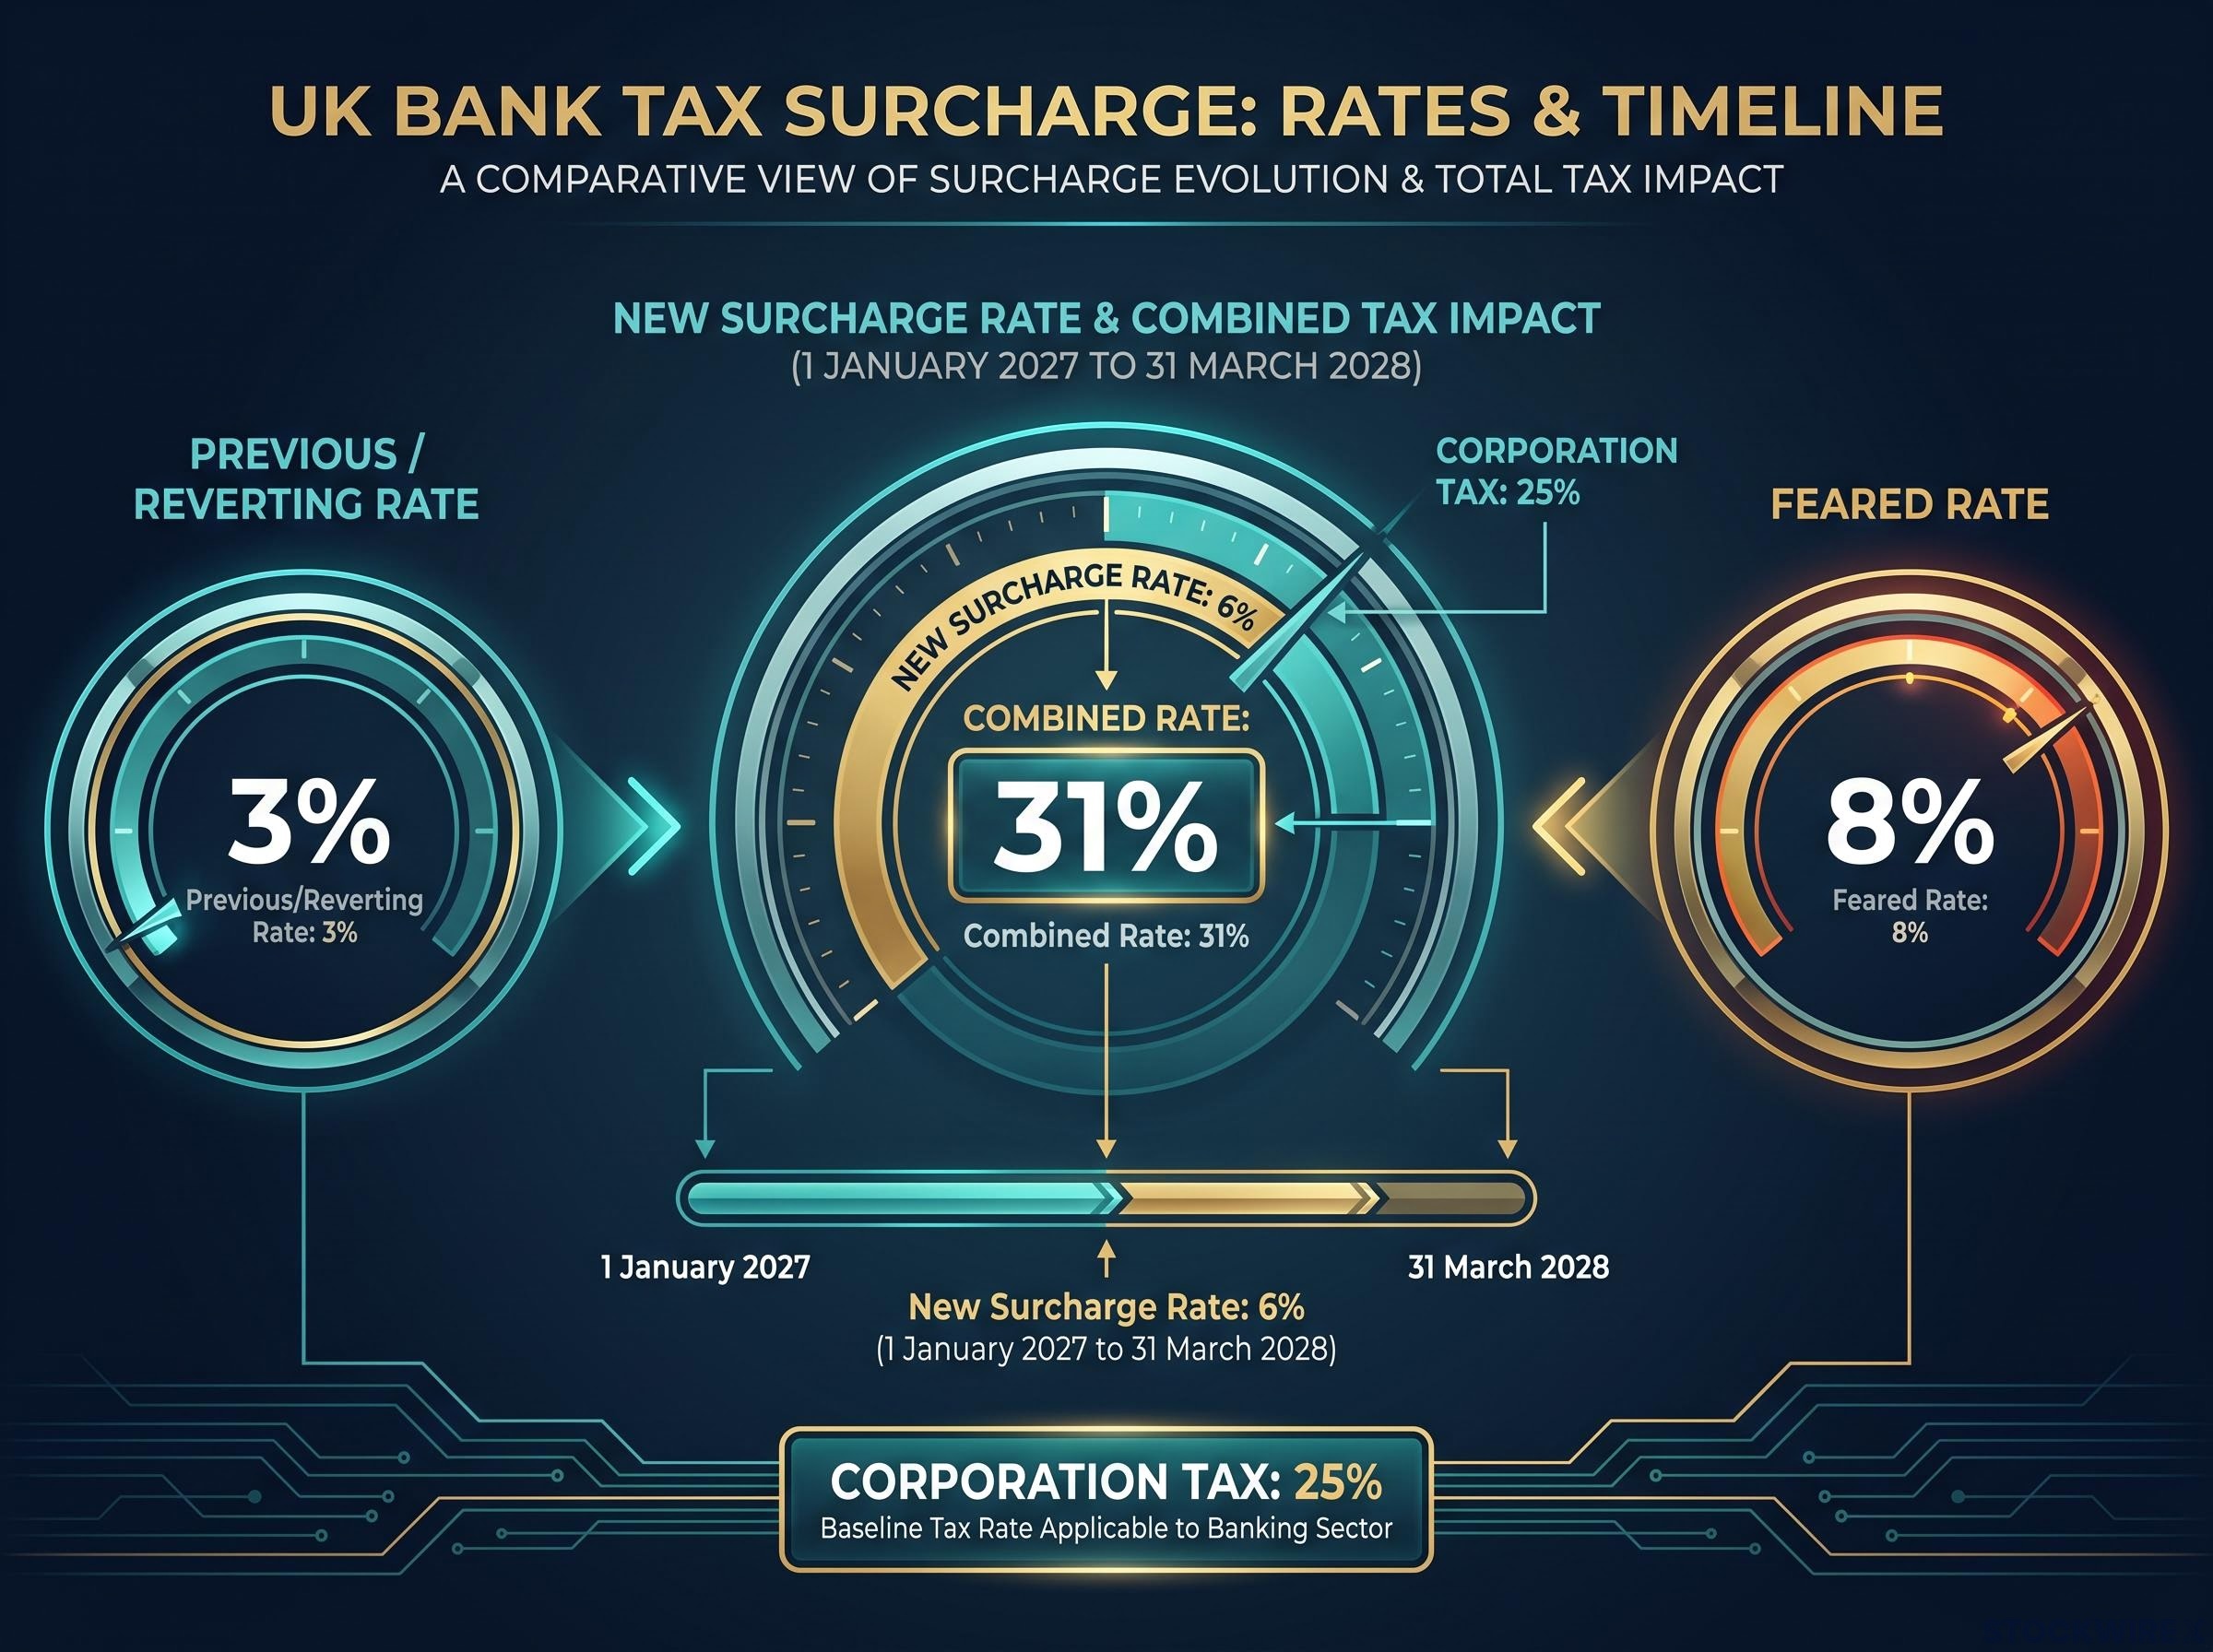
On 28 October 2026, Chancellor John Healey announced a temporary rise in the surcharge from 3% to 6%, running from 1 January 2027 to 31 March 2028. That is well short of the permanent return to 8% that markets had feared for most of October.
The outcome also tests an earlier view. Before the Budget, Filippo Alloatti of Federated Hermes argued that UK bank fundamentals and liquidity looked stable and that fiscal policy was the main risk. The fiscal question has now been answered, and the answer is mixed.
After reading this, you will be able to judge three things: who actually bears the cost, how far higher interest rates can offset it, and whether capital buffers turn this into a solvency issue. They do not.
What the 6% rate means: from feared 8% to a 15-month rise
The relief was immediate. Bloomberg reported NatWest up 4.1%, Lloyds up 3.8% and Barclays up 3.4% after the announcement. Those gains reversed much of an October sell-off in which major UK bank shares had fallen roughly 3-5%, according to Reuters on 16 October.
Market read Reuters attributed the rally to an increase that came in milder than investors had braced for.
Here are the settled terms:
- Rate: surcharge rises from 3% to 6% on UK banking profits above £100 million
- Start: 1 January 2027
- End: reverts to 3% on 1 April 2028, giving a 15-month window
- Combined rate: 31% including the 25% corporation tax
- Yield: about £1.5 billion over the period, including about £1 billion in 2027-28
This is enacted policy, not a consultation. The temporary design caps the cumulative cost, which is what separates it from a permanent return to 8%.
The Budget 2026 documentation confirms the surcharge rises to 6% for 15 months from 1 January 2027, with the £100 million allowance unchanged, so the cost is capped by design and reverts to 3% on 1 April 2028.
Less bad is not the same as harmless, though. Three extra percentage points on UK profits still cut earnings, and the rally tells you the market had priced a worse result. Read the 6% rate as the removal of a tail risk, not as good news for earnings.
How the rise compares with 2015 and 2023
The 8% surcharge arrived in July 2015 under a Conservative government. It was cut to 3% in April 2023, when corporation tax rose to 25%, which left the overall bank rate at 28%. The new 31% sits between those two regimes, and it has an expiry date built in.
When big ASX news breaks, our subscribers know first
Why Lloyds and NatWest carry the heaviest load
Start with how the tax is calculated. The surcharge applies only to UK banking profits above the threshold, not to a group’s worldwide earnings. A bank that earns most of its money abroad pays the surcharge on a smaller slice of its profits.
Now look at the slices. Analysis reported on 28 October puts the eligible share at about 85% of group profits at both Lloyds and NatWest, against 33% at Barclays, 20% at HSBC and 20-25% at Santander UK.
The earnings estimates follow that pattern. RBC Capital Markets analysts Benjamin Toms and Pablo de la Torre Cuevas modelled the 3% to 6% move for FY2027. The per-point column below divides their figures by three, because no public source gives exact per-point sensitivities.
| Bank | Share of profits eligible | RBC FY2027 profit reduction | Approx. per 1 percentage point |
|---|---|---|---|
| NatWest | 85% | 4.0% | ~1.33% |
| Lloyds | 85% | 3.8% | ~1.27% |
| Barclays | 33% | 1.8% | ~0.60% |
| HSBC | 20% | 0.8% | ~0.27% |
| Santander UK | 20-25% | 0.5% | ~0.17% |
RBC’s finding The largest profit effects fall on NatWest and Lloyds, because most of their earnings sit inside the charge.
UBS reached a similar view, estimating sector profits could fall by up to 4%, with NatWest facing about £263 million a year. For comparison, Gary Greenwood of Shore Capital had modelled an 8% rate cutting earnings about 6% at Lloyds and NatWest, 2% at Barclays and 1% at HSBC. KBW put the overall effect at about 6%.
Three reasons exposure differs
- Profit geography: Lloyds and NatWest earn most of their profits in the UK, while HSBC earns far more abroad.
- Threshold structure: more of a domestic bank’s profit base falls above the £100 million line, so more of it is taxed.
- Business mix: Barclays’ investment bank dilutes its exposure, while Lloyds’ insurance, cards and wealth arms offer only partial relief from a heavily domestic core.
If you hold or are weighing UK-focused lenders, the surcharge feeds directly into your earnings estimates. For the internationally diversified groups, it is a modest drag.
Can higher rates offset the bill? Margins, deposits and pass-through
There is a hopeful case. Bank Rate, the Bank of England’s main policy rate, sits at 3.75% after a 6-3 vote in September, with three members backing a rise to 4%. On 1 October, Monetary Policy Committee member Catherine Mann said rate rises may need to follow, and the overnight index swap (OIS) curve, which tracks market expectations for policy rates, implied about 75bp of tightening over 12 months (1bp is one hundredth of a percentage point).
Higher rates generally lift the yield banks earn on loans and on reinvested hedges. Lloyds’ results show that effect, and also its limits.
Bank of England policy decisions feed through to bank earnings as much as to sterling, because the 3.75% Bank Rate and the 6-3 September split shape the yield banks earn on loans and reinvested hedges.
Lloyds’ live test Banking net interest margin reached 3.25% in Q3, up from 3.22% in Q2, with 3.21% for nine months against 3.04% a year earlier. Management flagged mortgage-margin compression and deposit competition as offsets.
Net interest margin (NIM) is the gap between what a bank earns on loans and pays on deposits, as a share of its lending assets. Lloyds also lost £3.7bn of retail deposits while commercial deposits rose £9.6bn.
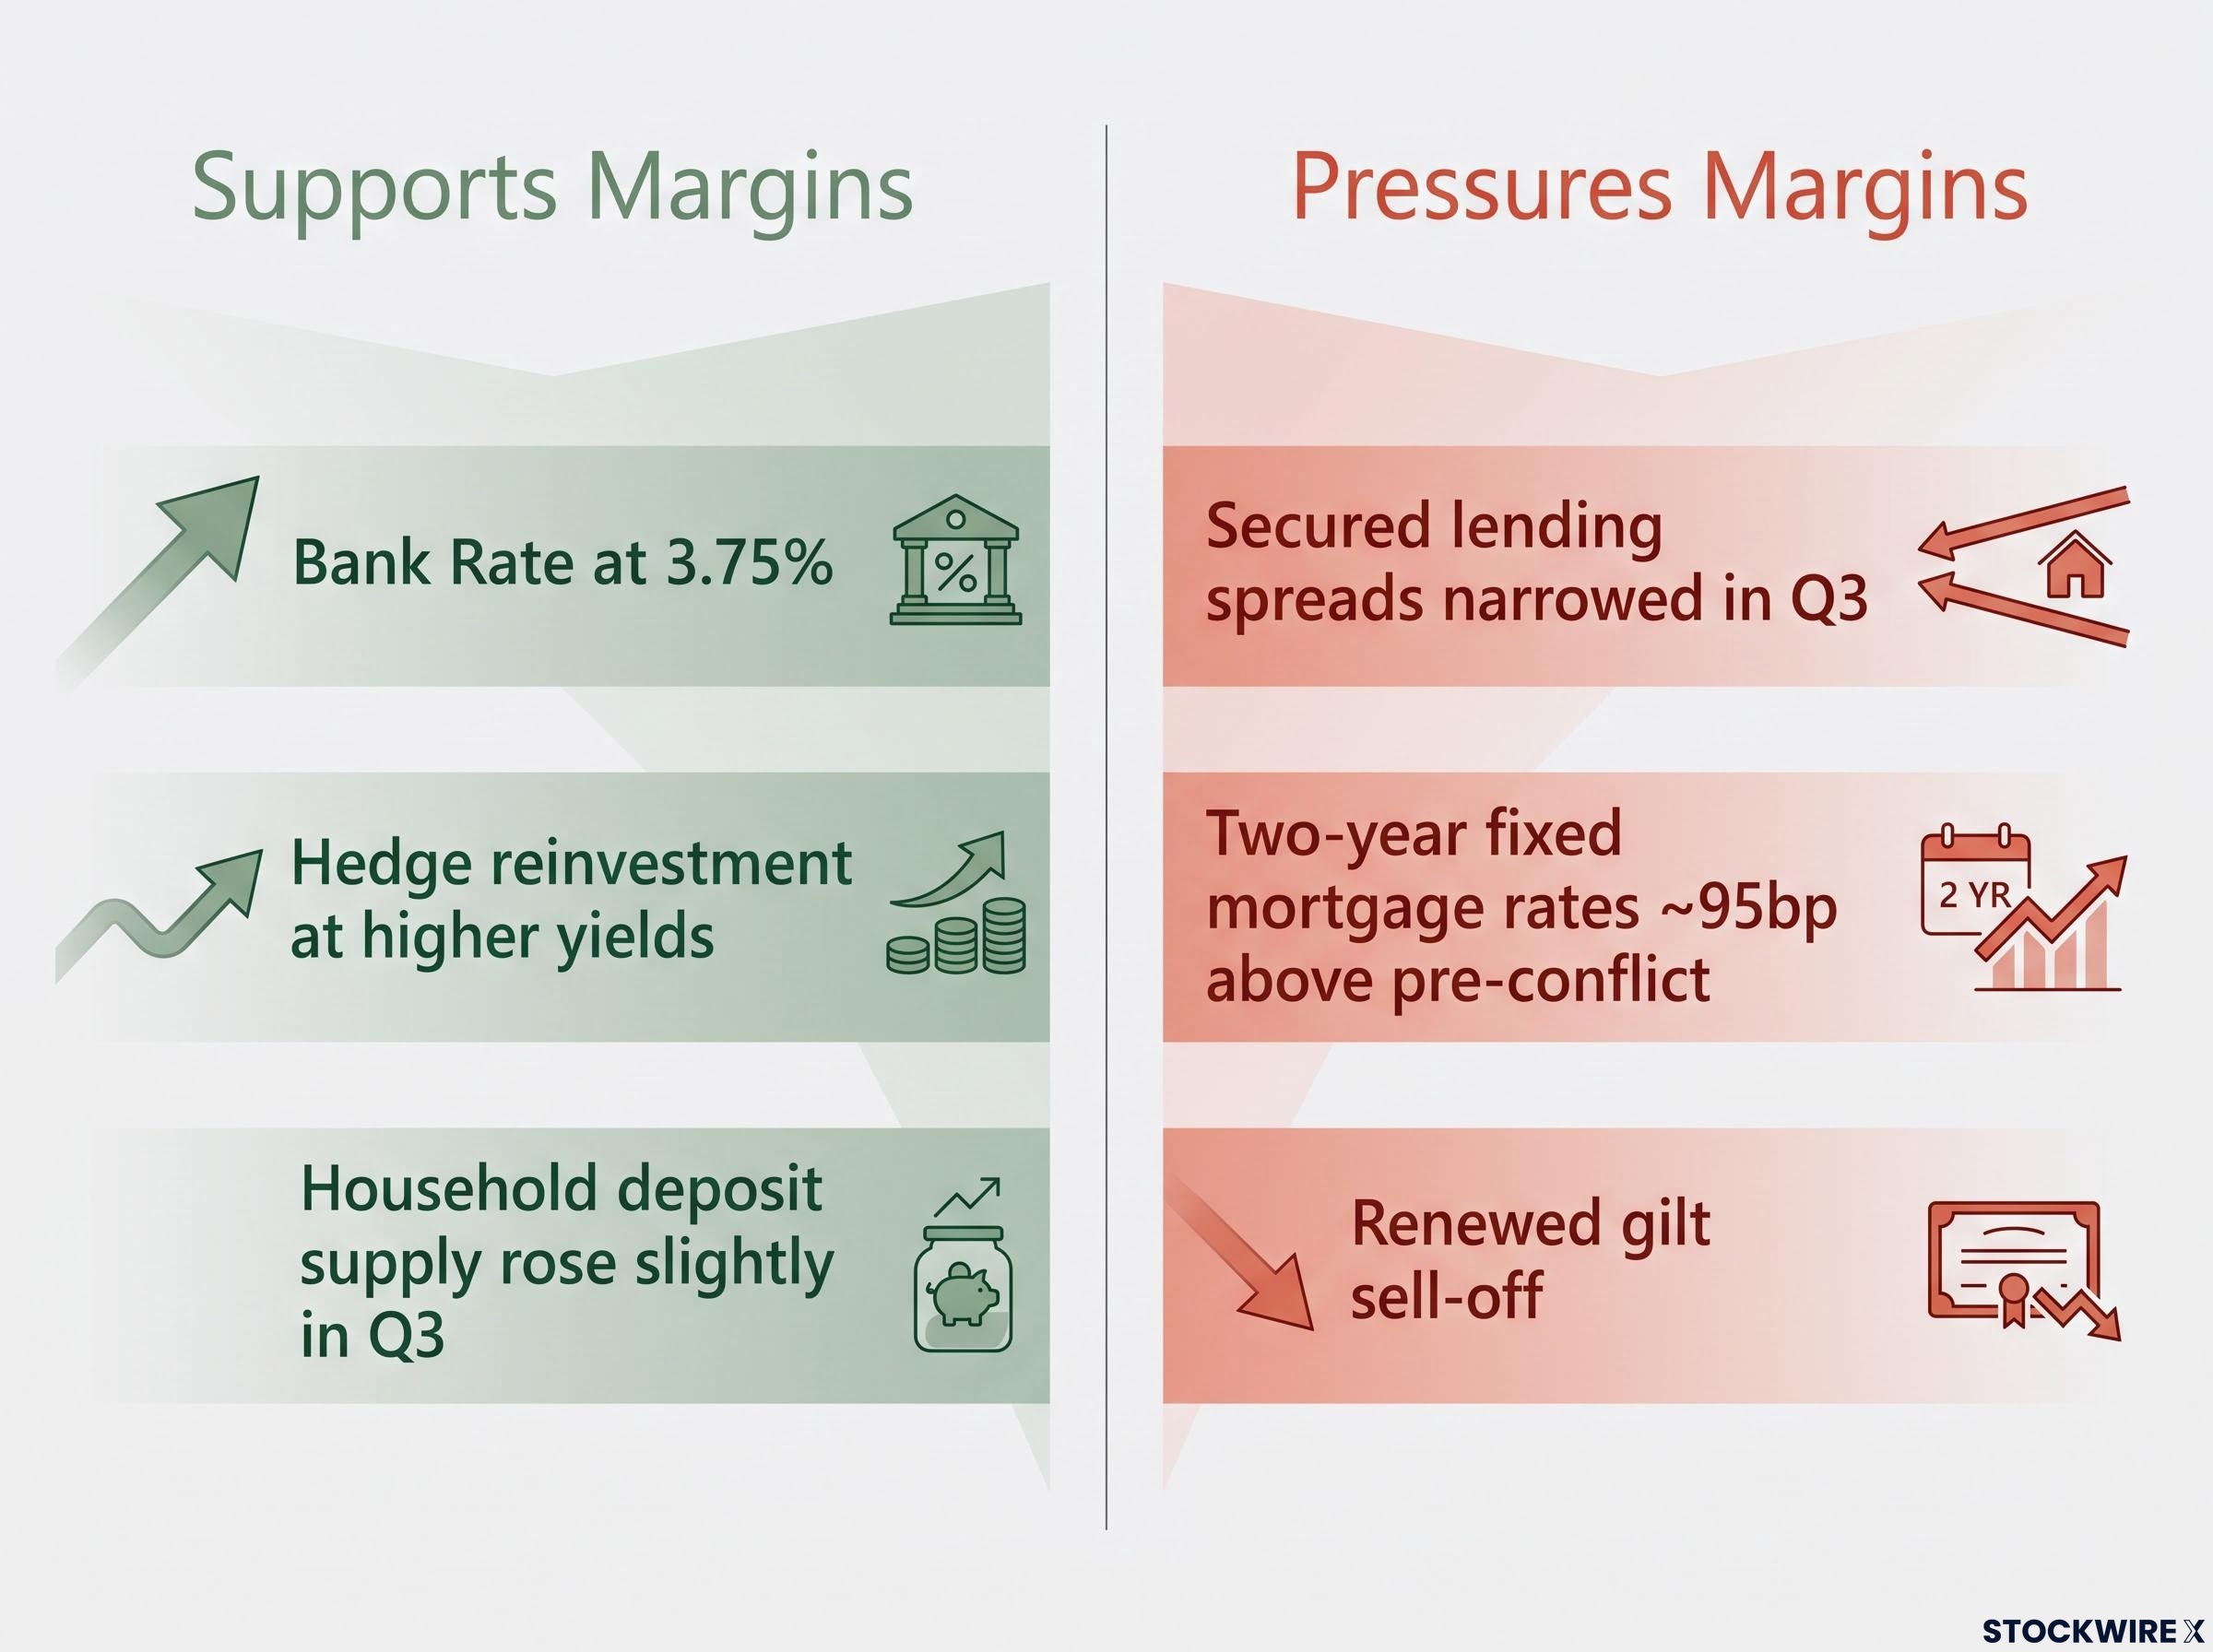
The forces pull in both directions:
Supports margins
- Bank Rate at 3.75% with further tightening priced
- Hedge reinvestment at higher yields
- Household deposit supply rose slightly in Q3, according to the Bank of England
- Alloatti does not expect a fight over deposits, judging liquidity steady even where some lenders compete harder
Pressures margins
- Secured lending spreads narrowed in Q3 and were expected to narrow again
- Two-year fixed mortgage rates sit about 95bp above pre-conflict levels, which can weigh on demand
- A renewed gilt sell-off could raise wholesale funding costs
The read for you: treat rate support as a partial offset to the surcharge, not a full cushion.
The pass-through risk
RBC and UBS both suggest banks could pass part of the tax to customers through higher mortgage rates or lower deposit rates. That protects margins in the short run but could reduce loan demand and weigh on growth.
UK Finance argues that higher bank taxes weaken competitiveness, investment and jobs. The counter-argument is that banks have benefited from higher rates and remain highly profitable.
Capital strength and the unconfirmed 40bp CET1 boost
On capital, the picture is comfortable. Common Equity Tier 1 (CET1) is a bank’s highest-quality capital, mainly shareholders’ equity, measured against its risk-weighted assets.
Capital headroom UK Finance’s 2026 submission reported average domestic-bank CET1 of 14.8% against an average minimum requirement of 12.3%.
That gap matters for how you frame the surcharge. It is an earnings and returns question, not a solvency question.
The 40bp claim needs more caution. Alloatti suggested possible changes to the treatment of intangible assets, such as software, could add around 40bp to CET1. The Prudential Regulation Authority (PRA) Rulebook, under CRR Articles 36(1)(b) and 37, still requires intangibles to be deducted, and no PRA publication confirming the uplift was found.
- Confirmed: CET1 of 14.8% against 12.3%; intangibles still deducted under current rules
- Unconfirmed: a roughly 40bp CET1 benefit, which is best treated as an analyst or industry estimate
The industry’s wider warnings are a different matter. UK Finance chief executive David Postings said an 8% surcharge could forgo about £6bn of UK output over five years, rising to nearly £20bn over ten, a scenario the Budget did not adopt. The IMF’s 2026 Article IV report noted banks remain important to financing, but that some growth constraints, such as weak equity funding for high-growth firms, lie outside banking.
Leave the 40bp out of your capital assumptions. Choose at the level of each bank and its balance sheet, with sovereign volatility as the remaining condition to watch.
What the surcharge changes for UK bank earnings, and what it does not
The temporary 6% rate caps the damage. The cost falls mostly on Lloyds and NatWest, margins offer only partial relief, and capital is not the constraint.
Your decision frame from here:
- NIM and deposit trends in upcoming results
- Any PRA statement on intangibles
- Gilt market stability
- Whether the surcharge reverts to 3% on 1 April 2028 as scheduled
Tracking MPC dissent and forward guidance matters for bank earnings too, since three members already favouring 4% suggests the rate support for margins could strengthen before the surcharge reverts in April 2028.
Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors. These statements are speculative and subject to change based on market developments and company performance.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
—