
Q3 2026 highlights: YTD revenue up 11.3% to $58.0M, EBITDA more than triples
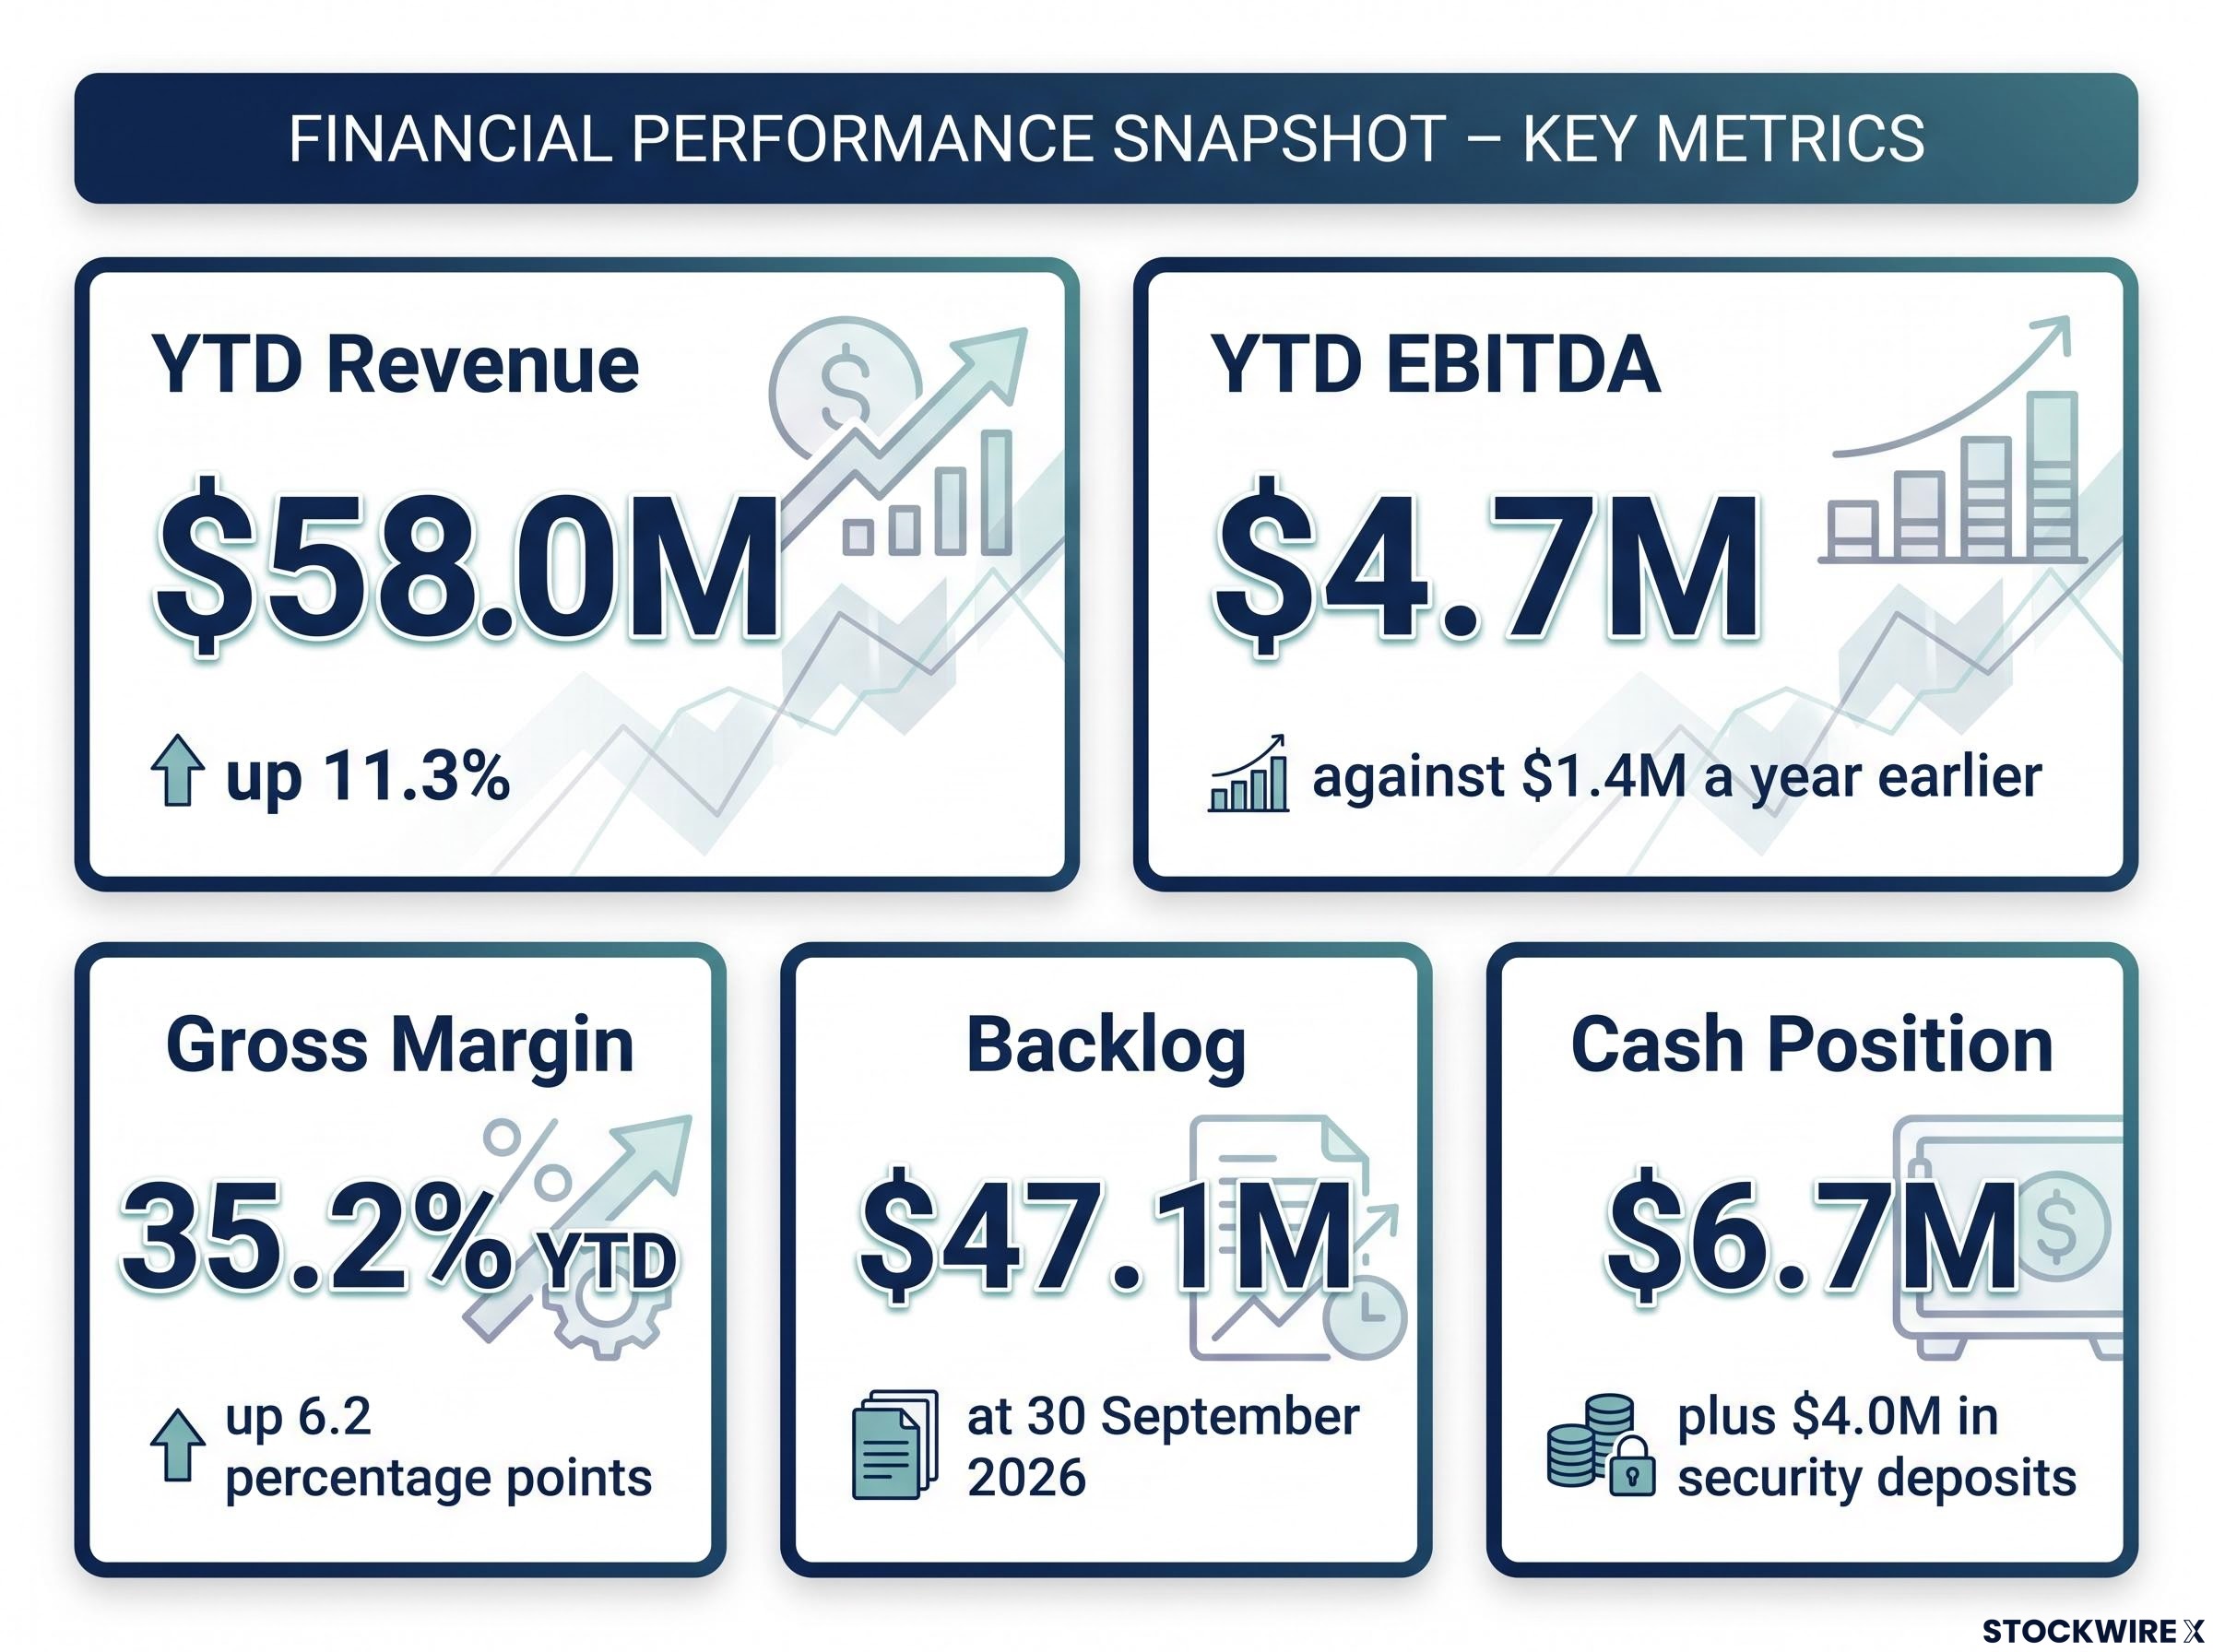
In its Q3 2026 quarterly activities report (quarter ended 30 September 2026), Fluence Corporation (ASX:FLC) recorded year-to-date revenue of $58.0M, up 11.3% on the prior year. EBITDA reached $4.7M against $1.4M a year earlier, already above the $4.1M delivered in FY2025.
Q3 2026 revenue was $20.4M, an increase of 5.8% on Q3 2025. Q3 2026 EBITDA of $1.3M marked 8 straight quarters of positive EBITDA dating back to Q4 2024. EBITDA is the company’s measure and excludes Other Gains and Losses. All figures are in US dollars and unaudited.
Headline metrics from the report:
- Gross margin: 35.2% YTD, up 6.2 percentage points
- Backlog: $47.1M at 30 September 2026
- Cash: $6.7M, plus $4.0M in security deposits
| Metric | YTD Q3 2026 | YTD Q3 2025 | Change |
|---|---|---|---|
| Revenue | $58.0M | Not stated | +$5.9M (11.3%) |
| EBITDA | $4.7M | $1.4M | +$3.3M |
| Gross margin | 35.2% | Not stated | +6.2 percentage points |
CEO and Managing Director Ben Fash said:
Ben Fash, CEO and Managing Director
“Fluence delivered another quarter of solid financial performance, with YTD revenue growth across our core business units of 23.0% and recurring revenue showing exceptional growth of more than 50%…”
Ben Fash also stated that “another year of significant profitable growth is expected in FY2026.” Higher revenue combined with wider margins produced the EBITDA step-up.
The Q3 step-up builds on H1 2026 results that already showed EBITDA at a five-year high, with revenue up 14.7% and the mix shifting steadily toward higher-margin recurring revenue.
When big ASX news breaks, our subscribers know first
Segment performance and the shift to higher-margin revenue
SPS and recurring revenue driving margins
Smart Product Solutions (SPS) plus Recurring Revenue (RR) grew 38.5% year to date, an increase of $12.5M, and 44.6% in Q3 2026. The core business units combined to grow revenue by 23.0% YTD and 35.0% in Q3 2026.
SPS and RR represented 98.2% of backlog at 30 September 2026, compared with 72.8% a year earlier. Fluence attributed margin expansion to improved revenue mix and strong project execution.
Business unit scorecard
YTD Q3 2025 figures are restated to exclude IWS (Egypt), which is reported as a discontinued operation.
| Unit | Revenue change | EBITDA change | Gross margin | Driver |
|---|---|---|---|---|
| IWB | +$3.6M (42.3%) | Doubled to $1.6M (+$0.8M) | n/a | Higher project volumes and growth in higher-margin SPS solutions |
| SEA & China | +$1.8M (45.9%) | +$0.7M to $0.3M | 30.7% vs 22.5% | Higher revenue and expanding gross margins |
| MWW | +$1.8M (23.1%) | Down $0.7M | n/a | One-time benefits in YTD Q3 2025 |
| IWR | Modest increase | Down $1.0M | 31.8% vs 37.9% | Lower gross margins and investment in SG&A |
| IVC | Down $1.8M | $6.5M (+$3.9M) | 40.0% vs 14.9% | Contract price escalation adjustments and RR maintenance fees |
IWR revenue rose modestly YTD, primarily due to order delays, though Q3 2026 revenue increased 27.0% on Q3 2025. Fluence said its 31.8% margin remains within management’s expectations.
For readers wanting the longer-term strategic backdrop, our deep-dive into Fluence’s double-digit EBITDA margins target explains how the pivot to Smart Product Solutions and Recurring Revenue is meant to get there, including the MABR cost advantage and SG&A reductions.
Orders, backlog and the Ivory Coast project
Q3 2026 new orders were $8.0M, bringing YTD new orders to $31.6M, a decrease of $8.0M (20.3%). Fluence said intake was below management’s expectations, reflecting the timing of customer investment decisions and delays in the award of several larger projects, with most “delayed but not lost.”
Q4 2026 is expected to be the strongest quarter for new orders in FY2026. However, due to the order delays, the company no longer expects FY2026 new orders to exceed FY2025.
Key wins in Q3 2026 and October 2026:
- Qurayyah ETP (Saudi Arabia): $2.3M NIROBOX effluent treatment plant, from a repeat customer
- iTest (SEA & China): $2.0M Aspiral MABR WWTPs, from a repeat customer
- IVC O&M maintenance services: $1.3M
- Red Bluffs (IWR USA): $0.6M BWRO
- Climax Molybdenum (IWB USA): $0.2M WWTP
- South Platte (MWW USA): Aspiral MABR pilot, described as a key strategic win in Colorado
RR new orders rose 93.5% to $3.3M in Q3 2026. Backlog was $47.1M at 30 September 2026 against $59.8M at 30 June 2026, reflecting revenue recognised during the quarter, including continued execution of the IVC Addendum project.
On the Ivory Coast Addendum, Fluence has collected seven milestone payments totalling €42.4M, approximately 87.6% of total contract value. Milestones 8 and 9, with a combined value of approximately €6.0M, are expected to be collected during Q4 2026 and Q1 2027.
Middle East conflict: how Fluence is positioning for volatility
Fluence said the continuing Middle East conflict has increased volatility in energy markets and supply chains, particularly through the Strait of Hormuz, through which approximately 20% of global oil supply typically ships. Higher energy prices are starting to feed into inflation and input costs, which in turn is leading to higher interest rates as central banks try to contain inflation.
For a project-based water infrastructure business, customers’ capital spending decisions are sensitive to borrowing costs and market risk. The company has not experienced any significant negative impact on its supply chain or any direct project or order cancellations, though some customers have delayed investment decisions. It is not projecting a material financial impact from the conflict in FY2026, although the environment remains volatile and subject to change.
Demand risks Fluence is beginning to see include:
- Delayed customer capital investments
- Higher costs of borrowing, particularly for project and working capital financing
- Greater returns required on capital projects to address increased market risks
- Weaker sentiment and planned capital spending by customers exposed to energy, freight and demand pressures
Management believes current disruptions are “sowing the seeds of future demand,” including requiring energy-efficient treatment solutions and the need to secure water resources.
Cash position and what comes next
Cash and cash equivalents fell from $10.9M at 30 June 2026 to $6.7M. Net cash used in operating activities was $4.3M, with lower receipts primarily driven by a delay in 2 large payments totalling more than $5.5M (Ivory Coast 2025 maintenance fees and the Qurayyah WTP project), both expected to be received imminently.
Receipts from customers totalled $12.6M in Q3 2026. Investing outflows were $0.5M, and net financing inflows were $0.7M, comprising $0.8M from a short-term loan facility in Argentina less $0.1M of lease liability repayments. Of the $4.0M in deposits, approximately $3.7M is held as collateral supporting bank guarantees for the Ivory Coast Main Works project.
In Egypt, the company formally took steps to suspend IWS operations on 12 October 2026. Fluence will continue to report IWS as a discontinued operation.
What happens next for Fluence
Events and timing stated in the report:
- Q4 2026: positive EBITDA is forecast, which would represent 9 straight quarters of positive EBITDA.
- Q4 2026: operating cash flow is expected to be positive, albeit less positive than originally forecast, supported by the expected receipt of IVC Addendum milestone 8 and several other large customer receipts.
- Imminent: receipt of approximately $3.5M for 2025 Ivory Coast maintenance services, and the Qurayyah WTP payment, both expected imminently.
- Q4 2026: the strongest order bookings of FY2026 are expected.
- End of October 2026: the majority of pipeline installation and access road works are expected to be completed.
- December 2026: the IVC Addendum project is forecast to complete, including remaining bridge and swamp stabilisation works.
- Q4 2026 and Q1 2027: milestones 8 and 9, combined approximately €6.0M, are expected to be collected.
- Ongoing: negotiation of the long-term Ivory Coast O&M contract continues, and an invoice of approximately $1.3M for first half 2026 maintenance services has been submitted.
Don’t Miss the Next Water Technology Winner
Join 20,000+ investors getting FREE breaking ASX news within minutes of release, complete with in-depth analysis already done. Click the “Free Alerts” button at Big News Blast to get market-moving announcements in your inbox the moment they break, and stay ahead of the market.