The Australian dollar climbed to its strongest level against the New Zealand dollar since March 2013 on Wednesday, 28 October. Two developments drove the move: hotter-than-expected Australian inflation and a surprise decision by the Reserve Bank of New Zealand (RBNZ) to hold its cash rate at 2.75% on a 4-3 vote. According to FXStreet, AUD/NZD gained nearly 1.5% on the day.
The gap behind the move is simple. One central bank edged closer to another rate hike while its neighbour delayed one, and AUD/NZD trades on exactly that difference.
If you hold either currency, the size of that gap now affects your returns.
The sections below cover why the pair moved, how to read inflation surprises and split votes, and which dated events could extend or reverse the rally.
How far did AUD/NZD actually move, and which price levels can you trust?
By any measure, the move was large. FXStreet reported an intraday peak near 1.2600, with spot trading around 1.2550. The Australian dollar was up about 1.55% against its New Zealand counterpart.
The weakness sat on one side of the pair. FXStreet’s heat map showed the New Zealand dollar as the weakest currency against every major listed, down roughly 1.32% to 1.47%. The Australian dollar barely moved against those same currencies. This was a story about the kiwi falling and the relative value between the two, rather than broad strength in the Australian dollar.
Rate guidance is only one of the forces that move the kiwi; Chinese activity data, dairy auctions and global risk sentiment can all amplify or override an RBNZ signal.
The exact levels are less certain.
| Source | Level reported | Measure | Attribution note |
|---|---|---|---|
| FXStreet | 1.2600 / 1.2550 | Intraday peak / spot | Not independently confirmed |
| PoundsterlingLive | 1.2339 | Reported rate, 28 October | Market-data report |
| Twelve Data | 1.2364 | Close | High recorded at 1.2366 |
Why the sources differ
Other market-data reports for the same date place the pair near 1.234-1.237. A Reuters-syndicated report supports the 13-year-high context but does not confirm the 1.2600 figure. The direction of the move and its historical significance hold up across sources. Before you use any specific level as a reference price, check it against your own platform.
When big ASX news breaks, our subscribers know first
Why did hot Australian inflation and an RBNZ hold push the pair higher together?
The answer starts with expectations about where interest rates are heading.
The Australian side
The Australian Bureau of Statistics (ABS) reported that annual headline inflation rose to 4.3% in September, up from 4.0%. Trimmed mean inflation, a measure that strips out the most extreme price moves to show the underlying trend, reached 3.6%. Some quarterly coverage cites 3.7% against a 3.6% consensus, but the ABS figure is the primary source.
Trimmed mean inflation has been climbing above the top of the RBA’s 2-3% target band, which is why a measure that strips out extreme price moves carries more weight with policymakers than the headline figure.
A consensus is the average forecast economists make before a release. A surprise is how far the actual number lands from that forecast. On Wednesday, the numbers came in hot.
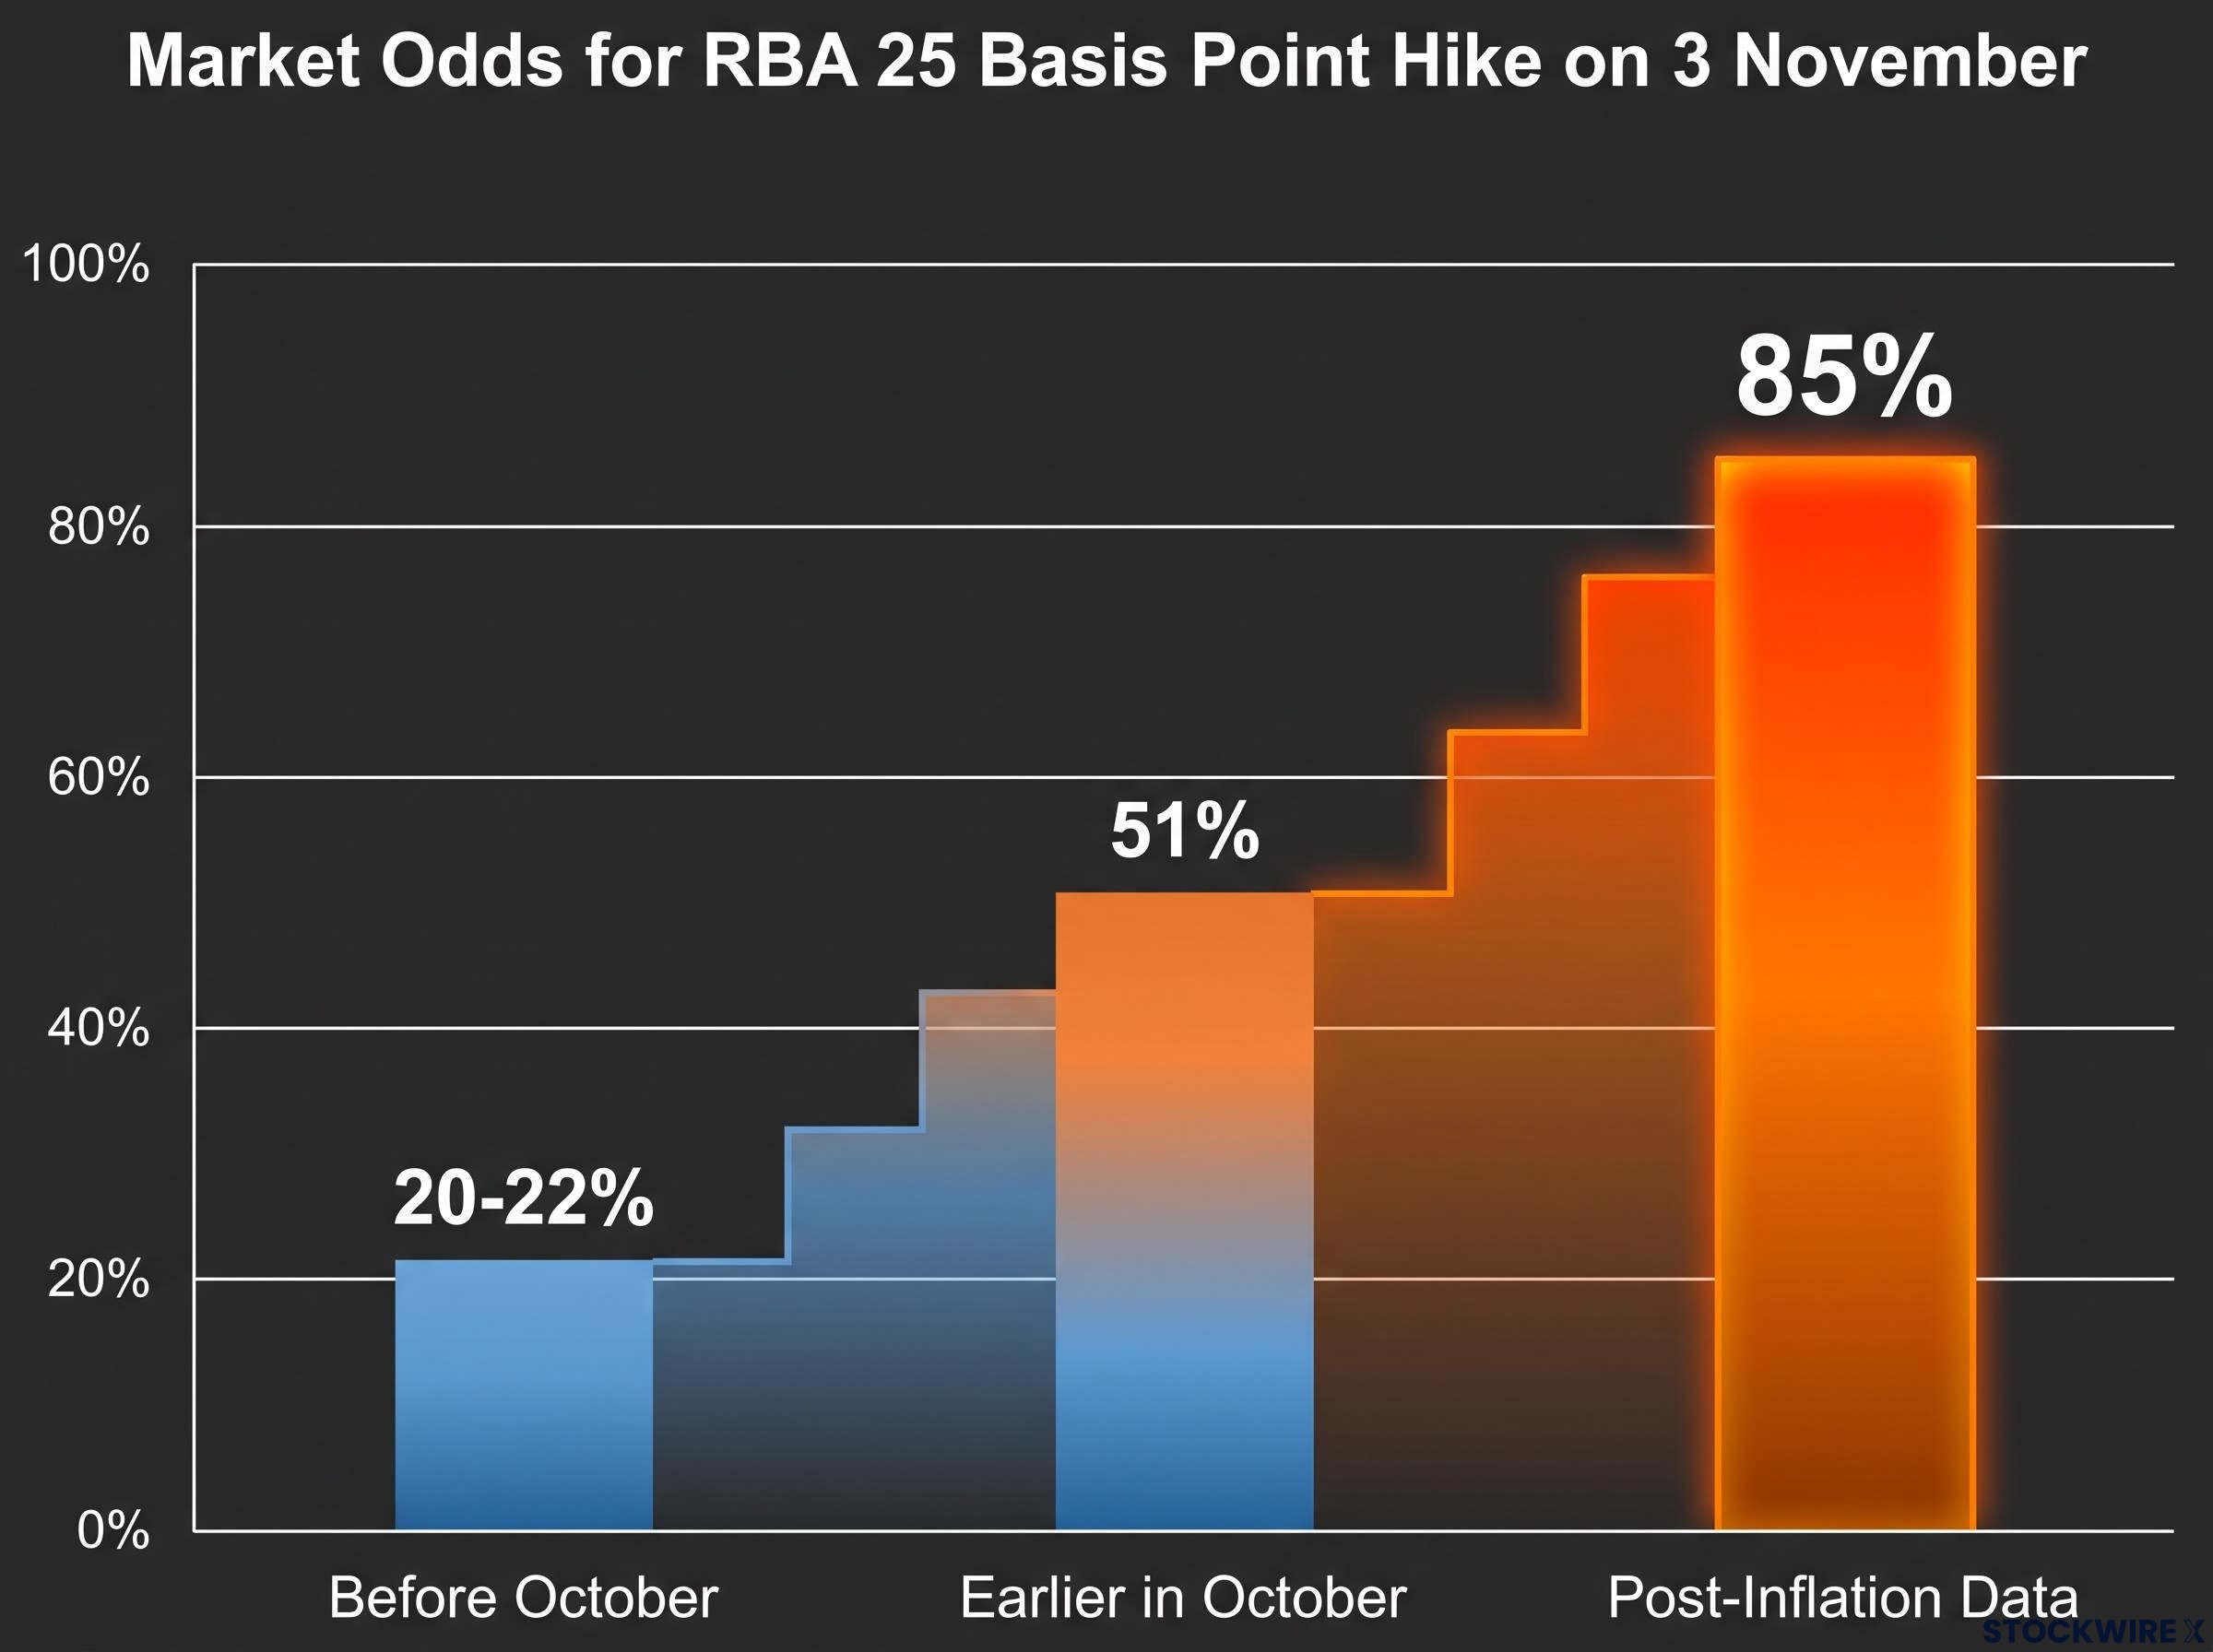
Governor Michele Bullock called inflation “far too high” and said it was difficult to look completely through energy-driven supply shocks. According to ABC, citing Bloomberg data, markets then priced roughly 85% odds of a 25 basis point hike on 3 November. That compares with about 51% earlier in October and around 20-22% before that.
The New Zealand side
The RBNZ, which had raised its cash rate to 2.75% on 2 September, held this time. Three of the seven committee members wanted a hike to 3.00%. Coverage pointed to subdued wages and fragile growth as reasons for caution.
RBNZ guidance “Tighter monetary policy is likely to be required but remains conditional on the economic outlook.”
A split vote reads both ways. It is dovish because there was no hike now, and hawkish because the committee came within one vote of one. The guidance did not support the kiwi.
The chain worked in five steps:
- The CPI surprise raised the expected path of Australian rates.
- A higher expected Reserve Bank of Australia (RBA) path lifted Australian yields.
- Higher yields improved the prospective returns on holding Australian dollars.
- The RBNZ hold lowered near-term New Zealand rate expectations.
- The wider expected gap between the two countries’ rates lifted the pair.
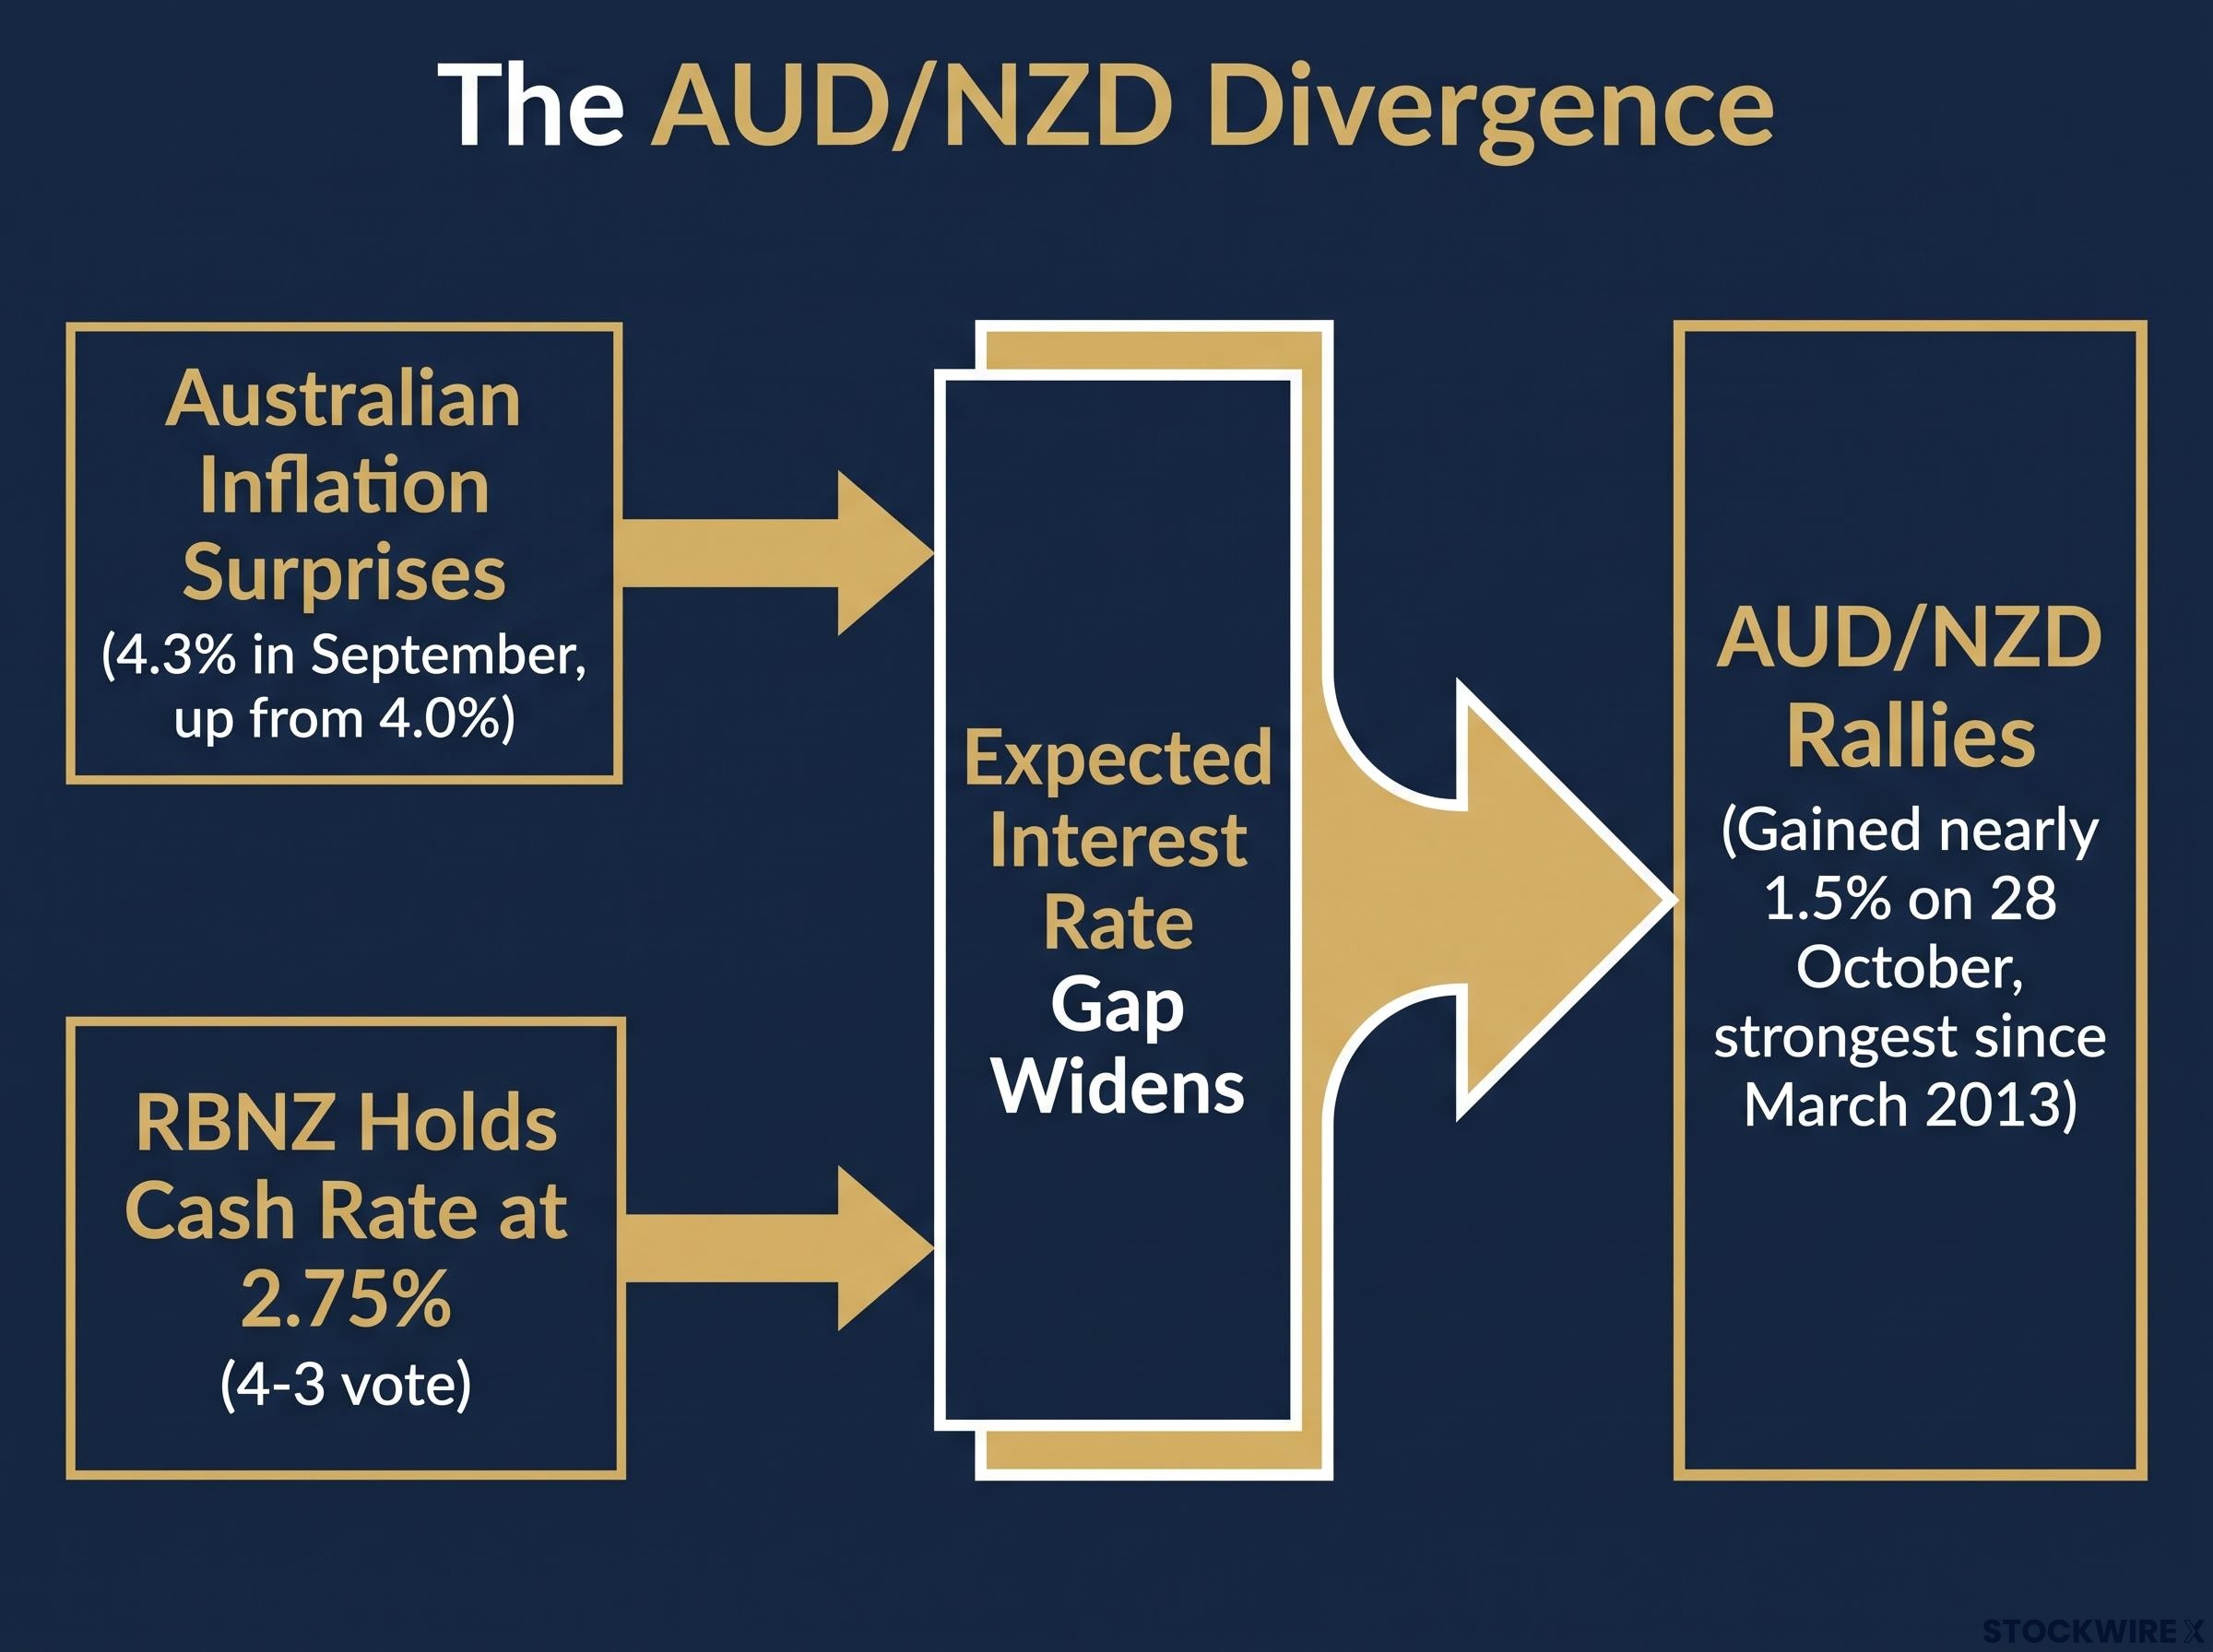
Each event made the other more powerful. A cross like AUD/NZD responds to the gap between two rate paths, so a surprise on one side and a delay on the other compound each other. You can apply the same chain to any future inflation print or vote split.
Is the move overextended? The case for the RBA holding and the pair reversing
For now, the case for a hike feels close to settled. The major banks are not agreed.
| Institution | RBA November call | Key reasoning |
|---|---|---|
| ANZ | Hike | Base case for November |
| Westpac | Hike | Luci Ellis said the RBA’s earlier unanimous decision lowered the hurdle for a follow-up hike |
| UBS | Hike | George Tharenou described earlier RBA communication as hawkish |
| CBA | Hold | Called the decision finely balanced, with rising hike risk |
| NAB | Hold | Weaker activity and a possibly temporary energy shock |
The risks to the rally are specific:
- A softer weighted-median inflation measure, according to InvestingLive, gave the RBA room to wait.
- Some forecasters see activity, consumption and the labour market softening.
- Westpac said the bar for hikes beyond November rises sharply if energy prices fall.
- Much of the RBA repricing happened straight after the CPI release, which leaves room for profit-taking.
- Australia’s commodity exposure cuts both ways. Energy supports the hike case, but weaker global growth or risk aversion could hit the Australian dollar.
There is a precedent. After the earlier 13-year high, the pair fell 1.3% overnight to 1.2295 when Australian data weakened and expectations of an RBNZ hike rose.
With roughly 85% of a hike already priced in, the risk is lopsided. A hike would mostly confirm what the market expects. A hold or softer guidance on 3 November could unwind the gains much faster.
What should traders watch next for AUD/NZD?
The checkpoints are dated, and each points the pair in a particular direction:
- RBA decision, 3 November (the meeting runs 2-3 November). A hike would validate the move. A hold would challenge it. A hawkish hold, meaning no move paired with strong warnings about inflation, would leave the question open.
- Bullock’s language. Watch whether she keeps her limited-look-through stance.
- Trimmed mean inflation. Watch whether it stays elevated once energy effects fade.
- The RBNZ dissenters. Watch whether the three members who wanted a hike win a majority at the next meeting. NZ non-tradable inflation (price growth in goods and services not exposed to foreign competition), wages and domestic demand will shape that outcome.
- Energy prices and Middle East developments. These feed directly into the RBA’s inflation outlook.
- Australia-NZ two-year swap rate differentials. Swap rates show where markets expect short-term rates to settle. The gap between the two countries’ rates is the market’s real-time gauge of policy divergence.
Michele Bullock, Governor, RBA Inflation is “far too high,” and supply shocks are difficult to look through completely.
Two signals matter most. If the RBA hikes and the swap differential keeps widening, the divergence story holds. If either one falters, you should question the rally.
For readers wanting to apply the same logic elsewhere, our full explainer on rate gaps in currency pairs shows how a policy differential turns inflation prints into predictable signals.
What the surge settles, and what it leaves open
The policy signal clearly favoured AUD/NZD. Australian inflation strengthened the case for an RBA hike, while the RBNZ held back, even if only by one vote. That signal still rests on expectations, and the decision on 3 November has to confirm them.
The price levels need care too. The 1.2550 and 1.2600 figures come from FXStreet, and other market data place the pair nearer 1.234-1.237.
The pair’s next move depends on two outcomes: what the RBA decides, and whether the RBNZ’s dissenters gain ground. Past performance does not guarantee future results. These statements are speculative and subject to change based on market developments.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.