In April 2012, a company announced it would bid for a resort membership business. On 27 October 2026, more than 14 years later, that company is listed to be sentenced for never making the offers. If you have ever assumed a takeover announcement is just talk until paperwork arrives, the section 631 takeover bid rule says otherwise.
Palmer Leisure Coolum Pty Ltd (PLC) pleaded guilty on 8 June 2026 to contravening section 631(1) of the Corporations Act 2001. Sentencing is listed for today in the District Court of Queensland.
At the time of writing, no sentencing outcome had been reported. Any figure you see attached to this case should come from the court or the Australian Securities and Investments Commission (ASIC), not from speculation.
Here is what the two-month rule asks of a bidder, whom it protects, how a case like this travels from regulator to courtroom, and what it signals for you the next time a bid hits the market.
What does the two-month rule actually require of a bidder?
Say you publicly announce that you plan to bid for a company. From that moment, a clock starts. Under section 631(1), you have two months to make formal takeover offers, and those offers must be on terms the same as, or not substantially less favourable than, the ones you announced.
The core rule: If you publicly propose a takeover bid, you must make matching offers within two months, or you may commit an offence.
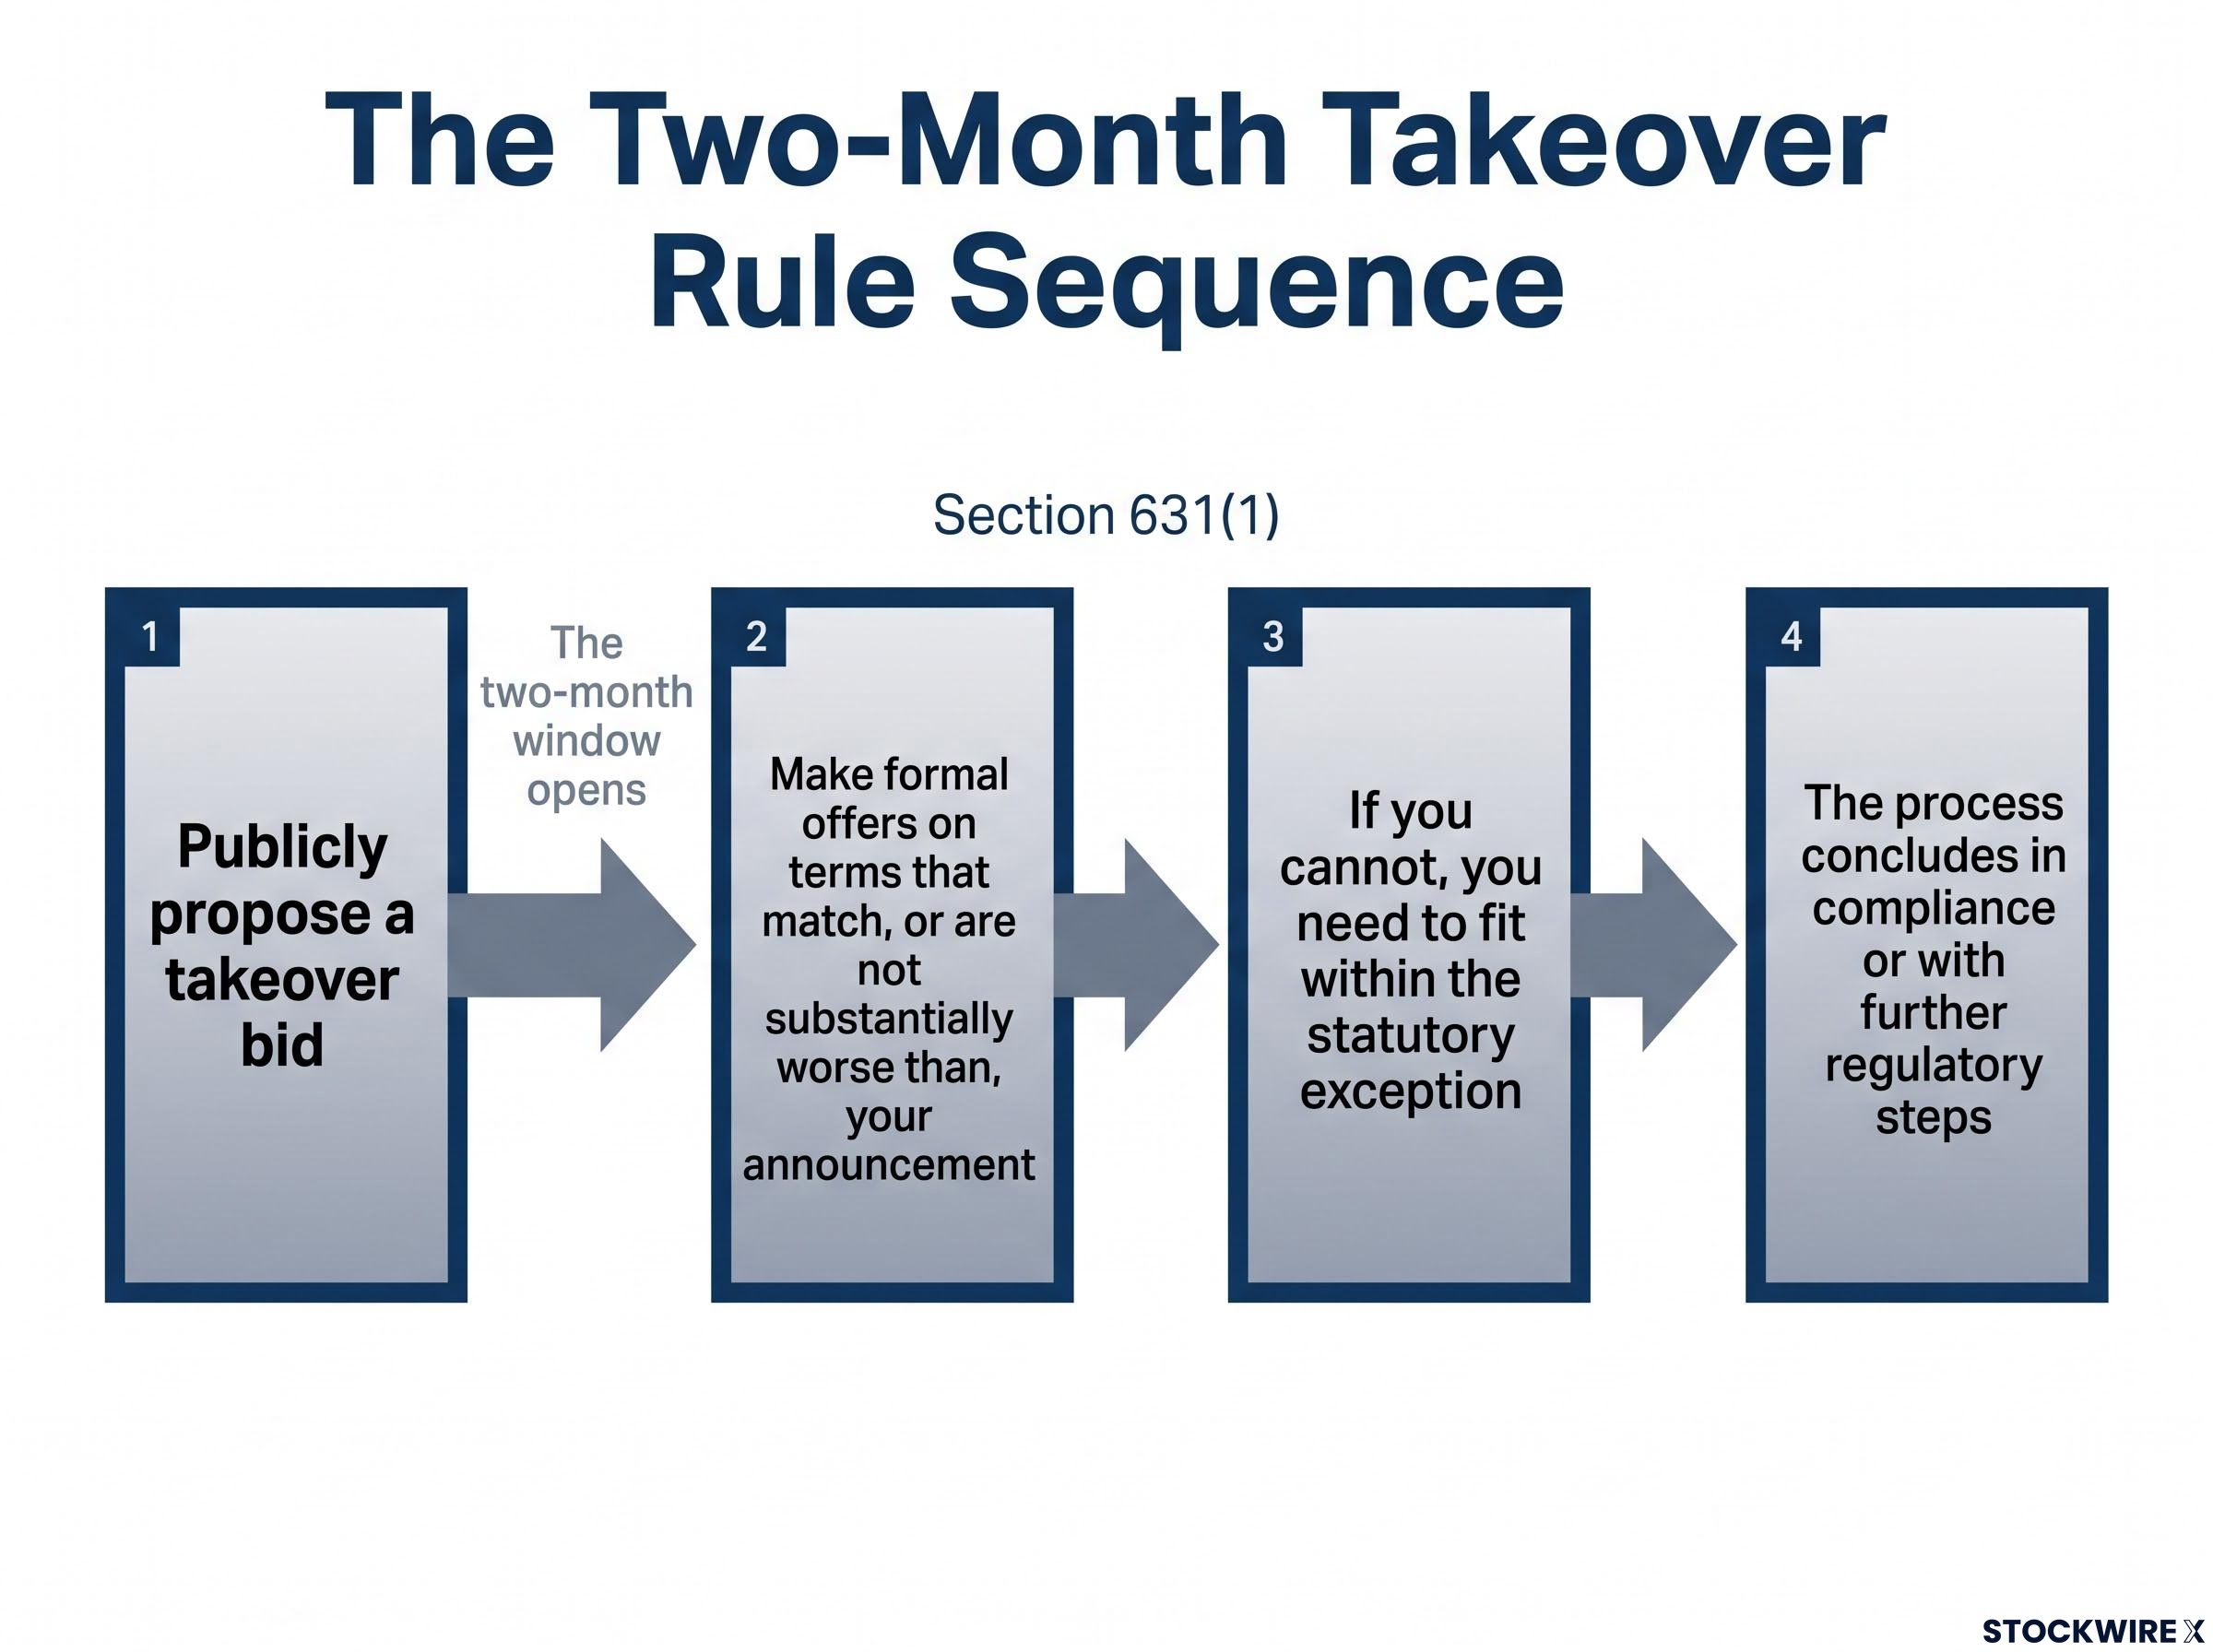
The sequence looks like this:
- You publicly propose a takeover bid.
- The two-month window opens.
- You make formal offers on terms that match, or are not substantially worse than, your announcement.
- If you cannot, you need to fit within the statutory exception.
The Takeovers Panel, the body that resolves takeover disputes in Australia, describes failing this rule as an offence. That matters because exposure does not depend on formal offer documents having been sent. The public statement alone can trigger it.
The gap between binding and non-binding proposals matters here: an indicative approach carries no obligation to proceed, while a publicly proposed takeover bid starts the two-month clock, so you should check which one you are looking at.
In PLC’s case, the company, then called Queensland North Australia Pty Ltd, lodged a bidder’s statement with ASIC on 12 April 2012 for The President’s Club Ltd (TPC). A bidder’s statement is the formal document setting out who the bidder is and what it proposes to offer. ASIC alleges no offers followed within two months.
For you as an investor or adviser, the takeaway is simple. A bid announcement is a legal commitment with a clock attached, not a statement of interest that can be quietly dropped.
The exception bidders can rely on
The rule has an exit, but it is narrow. A bidder is excused only where it could not reasonably be required to proceed as announced because of events that happened, or information disclosed, after the announcement.
Second thoughts do not qualify. The Panel’s decision in SSH Medical Limited [2003] ATP 32 discusses both the “not substantially less favourable” test and this exception, and the practical message is that any bidder relying on it should keep a documented record showing exactly what changed and when.
When big ASX news breaks, our subscribers know first
Why does Australia penalise an announced bid that never arrives?
Imagine you hold shares in a company that has just received a public bid proposal. The share price may lift. You start weighing whether to sell now or wait for the offer. Then weeks pass and nothing arrives.
You are left holding a stock priced partly on a deal that may never happen. That is the harm section 631 is designed to prevent.
The stated purpose: According to the Australian Treasury’s takeovers scoping paper, section 631 exists so that announced takeovers are followed through and offers are actually made.
The Takeovers Panel puts it in similar terms: the formal offer cannot be materially less favourable than the public proposal. Together, these protect you as a target shareholder by:
- stopping you being left indefinitely with an announced but incomplete transaction
- limiting how long the market has to price an uncertain proposal
- reducing the risk that an announcement distorts the target’s share price or trading expectations
- preventing a bidder from capturing the strategic or market benefit of an announcement and then walking away
The rule ties into a wider principle in section 602(a) of the Act: that control of Australian companies should change hands in an efficient, competitive and informed market. A bid that is announced but never made damages all three.
No source quantifies any price effect on TPC shares, so this case cannot tell you how much a stalled bid cost anyone. The principle still holds. If you own a target, an announcement can move the price and your expectations before any formal offer or target’s statement exists, so treat it as unconfirmed until offers are on the table.
How does a 2012 announcement become a 2026 sentencing?
The gap looks extraordinary. It makes more sense once you see the steps in order, although the public record does not explain every year of it.
| Date | Event | Source |
|---|---|---|
| 12 April 2012 | Bidder’s statement lodged for TPC; ASIC alleges no offers followed within two months | ASIC 18-095MR |
| 6 April 2018 | Charges announced against PLC (s 631(1)) and Clive Palmer (Criminal Code s 11.2) | ASIC 18-095MR |
| 2018 to 2025 | Pre-committal litigation by the defendants, including abuse-of-process challenges | Queensland Court of Appeal |
| 8 June 2026 | PLC pleads guilty in Brisbane Magistrates Court; committed to District Court | ASIC 26-113MR |
| 6 July 2026 | Indictment presented in the District Court of Queensland | ASIC 18-095MR |
| 27 October 2026 | PLC sentencing listed | ASIC 18-095MR |
The clearest documented reason for the delay is procedural. A Queensland Court of Appeal judgment recorded that the charges remained at the pre-committal stage because of proceedings brought by PLC and Palmer. Pre-committal is the phase before a case is sent to a higher court for trial or sentence.
The 2012-2018 gap is a different matter. The sources reviewed do not explain it, and none attributes the full 14 years to ASIC or the prosecutor.
Who does what: ASIC and the CDPP
ASIC investigates suspected breaches and refers cases. The Commonwealth Director of Public Prosecutions (CDPP) decides whether to prosecute and runs the case in court. Here, ASIC investigated and referred, and the CDPP prosecuted.
The ASIC and CDPP pipeline can move quickly when resourced: in the Forrest insider trading matter, investigation through to sentence took about a year, a sharp contrast with the 14-year path in the PLC case.
Palmer’s matter is separate. He is alleged to have aided, abetted, counselled or procured PLC’s offence, and that charge is listed for mention on 2 November 2026. PLC’s plea says nothing about the outcome of his case.
You should read the delay as a lesson in how far procedural defence can stretch a prosecution, not as proof of regulatory inaction. Still, a penalty arriving 14 years after the conduct sends a weaker signal than one arriving in 14 months.
Is a $55,000 maximum penalty enough, and what should bidders and shareholders take away?
Set the corporate maximum against the size of a typical takeover and the numbers feel mismatched.
| Offender | Maximum penalty | Source |
|---|---|---|
| Corporation | $55,000 fine | ASIC 18-095MR; confirmed in 26-113MR |
| Individual | Two years’ imprisonment and an $11,000 fine | ASIC 18-095MR |
These limits flow from sections 1311B and 1311C of the Act. Critics could argue that a fixed $55,000 fine is small beside a deal’s value, that a company might treat it as a cost of doing business, and that a penalty arriving years later deters little. These are evaluative concerns, not findings by any court.
The other side carries weight too. The offence brings reputational and legal costs well beyond the fine, individuals face possible imprisonment, and the case shows ASIC and the CDPP will pursue a bid that was never made, even years on.
The maximum also does not set the sentence. Courts weigh objective seriousness, culpability, the guilty plea, delay, comparable sentences and the offender’s circumstances. No comparable final sentence under section 631(1) was located, so there is no clear benchmark for today’s outcome.
What you can take from this is that the fine is the smaller part of the exposure. Reputation, litigation cost and personal liability weigh more than the headline figure.
For bidders
- Announce only once your intention to bid is settled and you can make offers within two months.
- Keep formal terms the same as, or not substantially less favourable than, the announcement.
- Communicate any conditions, such as due diligence, accurately rather than presenting a possible bid as definite.
- Take advice before any public statement that could read as a proposal to bid.
For target shareholders
- Treat an announcement as a proposal, not guaranteed consideration.
- Wait for formal offers and the target’s statement before relying on any terms.
- Remember the premium can reverse if the bidder does not proceed.
Investors exploring what happens when a bid collapses can read our deep-dive into takeover speculation risks, which shows how PayPal shares lost their entire takeover premium after a consortium walked away.
What the PLC case settles, and what it leaves open
The core point is now beyond argument for PLC: a public takeover announcement carries a statutory duty to make matching offers within two months, unless the narrow post-announcement exception applies.
Plenty remains unsettled. The sentence had not been reported at the time of writing, no comparable section 631(1) sentencing precedent was located, and Palmer’s separate matter returns to court on 2 November 2026.
Your decision point arrives with the next bid. When a proposal is announced, check whether formal offers follow within two months, and treat the announcement as unconfirmed until they do.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Commentary on possible sentencing outcomes is speculative and subject to change based on court developments.