Most of the commentary after SpaceX’s results has tracked the share price. Shares rose about 7-8% on the numbers, then fell 9.1% on Thursday. The more telling figure is that quarterly AI capex of roughly US$16.4 billion was more than double AI revenue of about US$7.56 billion, and the infrastructure needed to keep funding that gap is where the call’s real content sits.
The earnings call set out what the SpaceX AI infrastructure buildout will need over the next two to five years across compute, power and bandwidth. Management’s ambitions sit far above its own guidance, and further above analyst models.
This is not only a US story. Australian data-centre projects face the same physical limits on grid capacity and the same financing questions.
This gives you a portable test for any capital-hungry AI project: where the physical bottleneck sits, who pays to clear it, and how much of the promised revenue is actually contracted.
What did the call actually commit SpaceX to building?
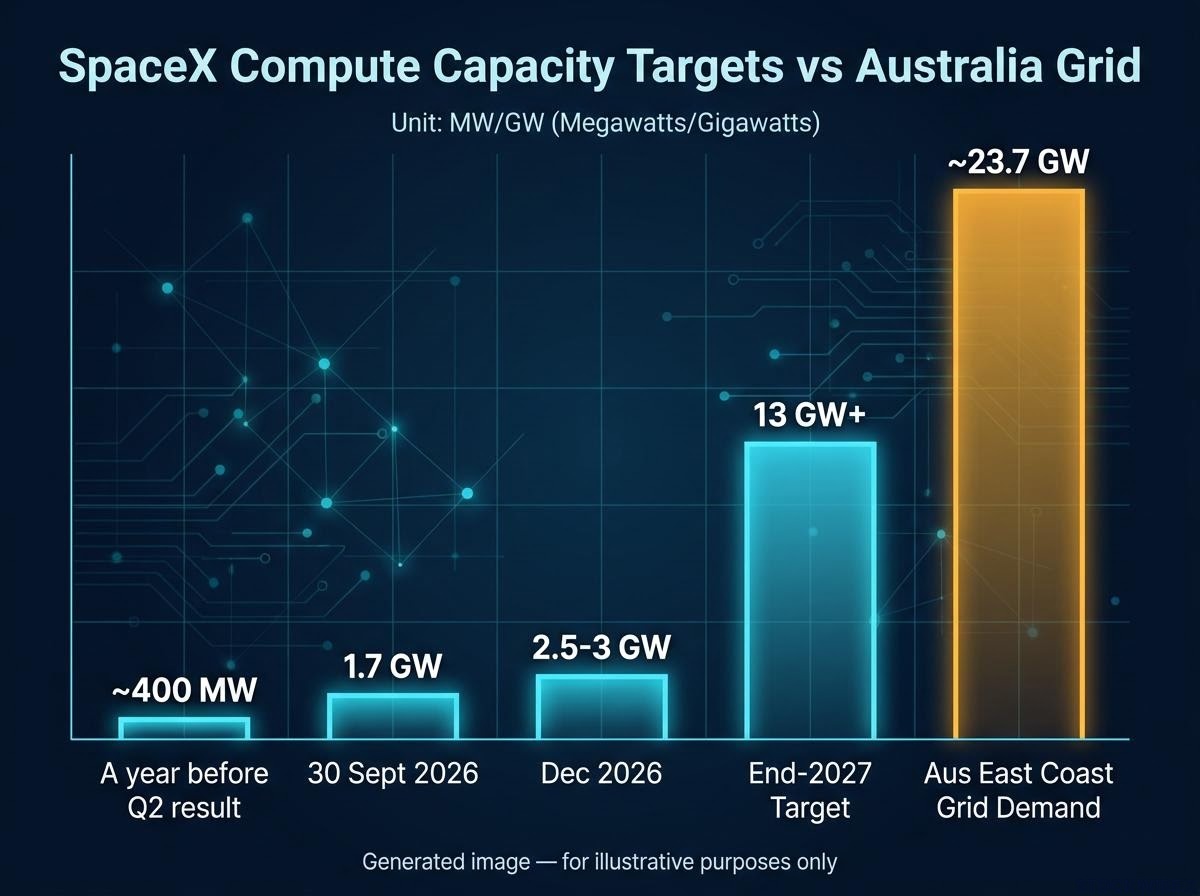
A year before its June-quarter result, SpaceX ran about 400 MW of compute. By 30 September 2026 it had 1.7 GW of nameplate capacity, which is the maximum rated output. Management expects 2.5-3 GW by December.
Then the target jumps to at least 13 GW by the end of 2027. Management said it is “highly confident” of adding 10 GW in 2027 alone. In August, the end-2027 guidance sat nearer 10 GW, so the goal was raised within a single quarter.
Elon Musk, Chief Executive Officer Musk said he would be surprised if capacity at the end of 2027 came in below 13 GW.
Chasing that number costs money at a matching pace. Capex was US$19.6 billion in the September quarter, and Chief Financial Officer Bret Johnsen guided to US$35-40 billion for the December quarter.
| Metric | Figure | Timing |
|---|---|---|
| Compute | ~400 MW | A year before the Q2 result |
| Compute (nameplate) | 1.7 GW | 30 September 2026 |
| Compute (expected) | 2.5-3 GW | December 2026 |
| Compute target | 13 GW+ | End-2027 |
| Total capex | US$19.6B (~US$16.4B AI) | September quarter |
| Capex guidance | US$35-40B | December quarter |
Cash stood at US$51.3 billion at 30 September. The original source reported a fall of about US$10 billion in the quarter, but no published prior-quarter balance corroborates that figure. The backlog adds context:
- US$63 billion total backlog
- US$42 billion expected to convert within 12 months
- US$17.5 billion in deferred revenue
Backlog is not the same as fully contracted, monetisable revenue, and much of the growth remains uncontracted. A first profit of about US$4.4 billion on revenue of US$14.6 billion, against US$12.7 billion consensus, shows demand is real. It does not show the economics are settled. Treat it as proof of demand, not proof that the funding question has been answered.
SpaceX reports four distinct revenue segments at very different maturity stages, so the AI compute line that is driving capex sits alongside mature launch and scaled Starlink broadband that already generate cash.
When big ASX news breaks, our subscribers know first
Why is power, not chips, the constraint on any AI buildout?
Most people assume the scarce input in AI is the chip. Musk told the call otherwise: power and cooling constrain deployment more than GPUs do. GPUs are the processors that run AI workloads.
The physics of the constraint
A finished data hall earns nothing until electricity reaches it and cooling is running. Moody’s identified the gap between physical completion and energisation as the key financing risk. Energisation means the power is switched on and the facility can operate, and lenders must verify that delivered power rather than trust construction milestones.
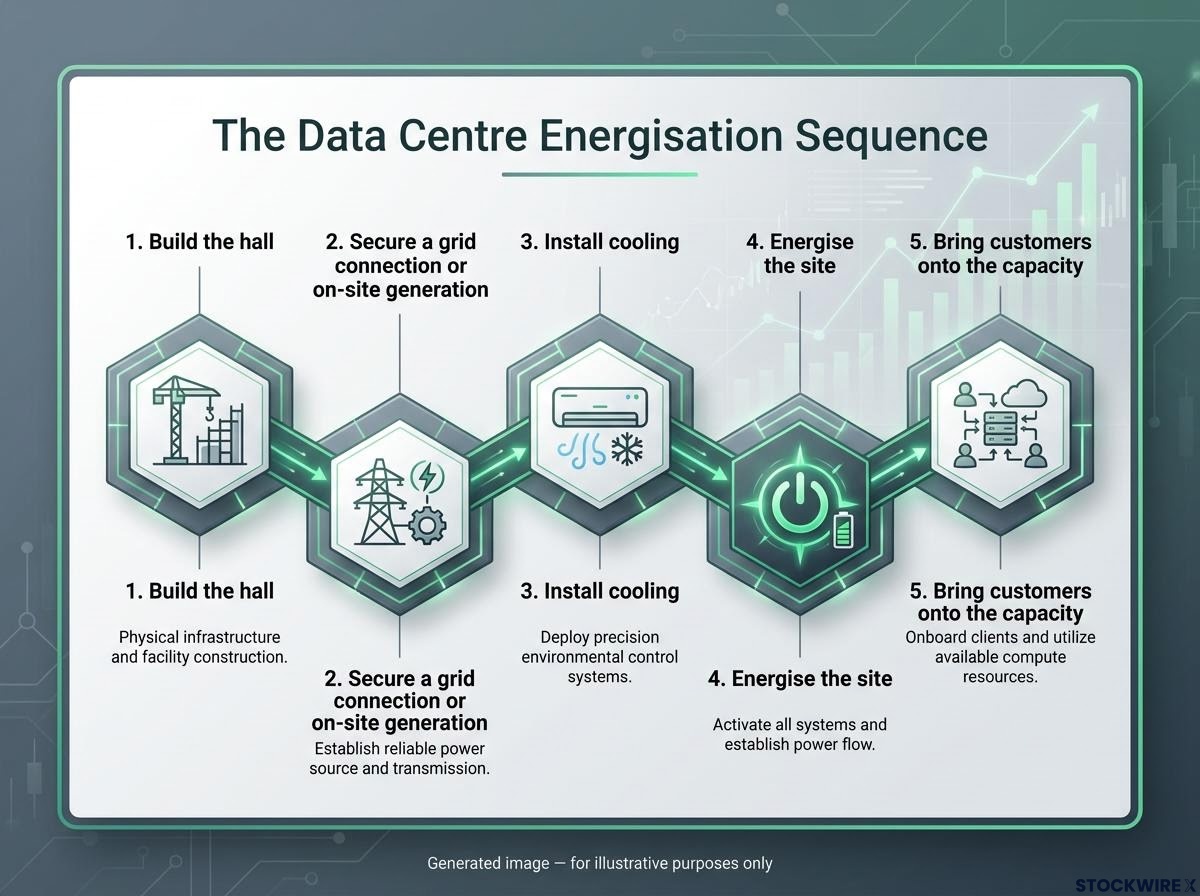
Before a facility earns revenue, it has to clear a sequence:
- Build the hall
- Secure a grid connection or on-site generation
- Install cooling
- Energise the site
- Bring customers onto the capacity
SpaceX’s response shows how seriously it takes this. It plans to add 20 GW of power and cooling in 2027, more than its GPUs need. According to suppliers, turbine blades and vanes arrive 12-18 months after the other turbine components, which is why SpaceX now produces its own castings at the foundry set up for its rocket engines.
The International Energy Agency (IEA) said in September 2026 that data-centre electricity use is expected to double by 2030, with AI-focused use tripling, as turbine, transformer and chip supply tightens. In August, it noted that data centres can go up in one to two years, while electricity infrastructure takes much longer.
What this looks like in Australia
Scale check Australia’s east coast grid has an average demand record of about 23.7 GW. SpaceX plans 20 GW of power and cooling additions in 2027.
Local limits are already visible. In October 2026, AusNet, Jemena and Powercor said proposed data-centre loads exceed available grid capacity in parts of Melbourne’s west. Research also points to a federal framework proposed in September with a higher tier for facilities of 100 MW or more, though that detail has not been independently confirmed.
Locally, grid access is the binding limit: roughly 300 live data-centre projects are already straining connection processes, which is why headline pipeline figures overstate what can actually be energised.
Australia has land, renewable potential and subsea links. Firm electricity, transmission access, cooling water and timely approvals are the scarce inputs. For you, the useful question about any AI project is not whether it has chips, but when its power is actually switched on, and who has verified it.
Can demand, pricing and bandwidth justify a buildout this large?
If power sets the pace, demand sets the reward, and the bull case here carries real force. Compute demand outstrips supply, renewals of short-term contracts are landing at higher prices, and used chips now command higher rents than they did brand new. SpaceX says hyperscalers, the largest cloud providers, press it constantly for capacity.
- Scarcity pricing: above the earlier US$30-50 per watt range, or US$30-50 billion of revenue per GW
- Fast payback: under one year at current prices, with Musk raising six months in 2027
- Demand breadth: incremental Super Intelligence revenue up US$6.7 billion year-on-year across models, agents, cloud and Starlink distribution
- Vertical integration: in-house turbine casting and a chip fab targeting a test chip in mid-2027 and volume production in the second half of 2028
Anthony Valentini, Barclays Valentini said SpaceX was demonstrating the durability of its AI revenue growth and its capacity to hit ambitious deployment timelines.
Agents and bandwidth as the demand story
Grok Bot, an agentic assistant that carries out tasks rather than just answering questions, hit 800,000 paid weekly users in early October, which is over twice the figure a month earlier. Business customers are growing fastest.
Agents also tie the compute story to Starlink. Broadband subscribers reached 13.6 million, up from 7.2 million a year earlier, and connectivity revenue hit US$5.25 billion, up 69%. Starlink Mobile has 22 million monthly users and 12,000 aircraft are contracted.
Each Starship flight carries 26 V3 satellites, about 10 times Falcon 9’s downlink capacity. SpaceX targets 100x constellation bandwidth in about three years, and Musk expects 1,000x bandwidth demand in 3-5 years because agents use more bandwidth than humans. The research found no total throughput target beyond 26 Tbps per flight.
What could undercut the pricing
All of it rests on one hinge: prices and utilisation have to last.
SpaceX sells at spot rather than under long-term contracts. Revenue per megawatt may reflect acute scarcity that fades as hyperscalers add supply, and falling Starlink revenue per user could reduce cash for expansion. Read the payback claims as a snapshot of scarcity, which means the pricing that makes the build look brilliant is the first thing to go if supply catches up.
Vision, guidance and analyst models: where is the gap, and who funds it?
Reading the gap
Musk’s end-2027 recurring revenue ambition is US$500 billion to US$1 trillion. Wall Street consensus sits near US$110 billion, according to CNBC. Quarterly revenue was US$4.7 billion at the start of 2026, and guidance for the March 2027 quarter is US$33-37 billion, against roughly US$22 billion modelled.
| Source | Metric | Figure | Basis |
|---|---|---|---|
| Musk | End-2027 recurring revenue | US$500B-US$1T | Management ambition |
| SpaceX guidance | March 2027 quarter revenue | US$33-37B | CFO guidance |
| Consensus | End-2027 recurring revenue | ~US$110B | CNBC |
| JPMorgan | End-2027 recurring revenue / 2027 capex | ~US$400B / ~US$300B | Original source only, unverified |
| KeyBanc | 2027 capex | ~US$473B (from US$68B) | Analyst model |
| UBS | End-2027 compute | 2.5-3.0 GW | Analyst model |
KeyBanc models free cash burn of about US$57 billion in 2026 and US$328 billion in 2027, with roughly US$475 billion of extra capital needed through 2028. The March 2027 quarter result is the first hard test of whether guidance or the models are closer to reality.
Where the capital and bottlenecks sit
Gaps that size get filled with debt. Morgan Stanley estimates global data-centre capex excluding power could top US$3.2 trillion through 2028, with about US$1.75 trillion via credit, including roughly US$700 billion from private credit. Moody’s flags uncertain power delivery, obsolescence and customer concentration as underwriting risks.
The original author argues, as opinion, that the better opportunities may lie in bottleneck sectors rather than the headline name. Nuveen commentary points the same way:
- Power generation: turbines, batteries and behind-the-meter plants supply power before grid upgrades
- Grid connection: substations and interconnection decide whether facilities operate
- Cooling: dense racks lift equipment and water demand
- Electrical equipment: transformers and switchgear already face supply pressure
- Fibre: distributed AI facilities need low-latency links
The core risk is a financing mismatch: long-lived loans against hardware and demand that change faster than debt can be refinanced. Locally, research attributes to the RBA’s October Financial Stability Review a warning that data-centre construction is increasingly debt-funded, with operators raising at least $35 billion (Australian dollars) in 2026, about 16% of non-financial corporate funding examined. ASIC has reportedly flagged rising retail exposure to private credit, though neither point has been independently confirmed.
For an Australian investor, the headline stock is only one route to exposure. The bigger question is whether any asset you hold is financed and valued before its power, cooling and customers are contractually secure.
For Australian investors weighing local exposure, our full explainer on who captures Australian data centre rents examines NextDC’s unbuilt order book and execution risk on power and planning.
What this framework changes, and what it does not
The call leaves you with four questions to test any AI buildout:
- Is the power secured and verified?
- Is the revenue contracted?
- Is the pricing durable?
- Who bears the financing risk?
It did not resolve whether 13 GW is achievable, with UBS sitting at 2.5-3.0 GW. December quarter capex and the March 2027 quarter result are the next checkpoints, and both will show whether spending and revenue are converging.
If you are weighing exposure through listed infrastructure, funds or private credit, remember that unlisted products can carry liquidity and disclosure risks that listed shares do not.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections and forward-looking statements are speculative and subject to change based on market conditions and company performance.