On 20 October 2026, shares of Fannie Mae (FNMA) and Freddie Mac (FMCC) each jumped about 14% after Treasury Secretary Scott Bessent discussed their ownership. By 23 October, FNMA had slipped back to about $3.58 from $3.89. Official talk of a Fannie Mae and Freddie Mac release keeps lifting these shares, while the structure underneath barely moves.
A rally driven by headlines and a workable exit are two very different things. If you hold these shares or follow US housing finance, it is easy to read each new comment as progress when it may only be sentiment.
The administration has floated selling roughly 3%-6% of the companies, raising about $30 billion, while both stay in conservatorship. Conservatorship means government control of a company to stabilise it.
This explainer covers three things: the obstacles that make a full exit unlikely, the alternatives that are actually plausible, and a simple test you can apply to the next official statement.
Why can’t Fannie Mae and Freddie Mac simply be set free?
“Just release them” sounds like flipping a switch. Each obstacle below would delay an exit on its own. Together they turn release into a restructuring that could take years.
The capital and claims problem
Start with Treasury’s senior preferred stock. This is a class of shares that must be repaid before any other shareholder gets anything. Its liquidation preference, the amount owed to Treasury first if the company is wound up, keeps growing.
According to company filings, Freddie Mac’s stood at $140.2 billion at 31 December 2025 and was expected to reach $143.0 billion by 31 March 2026. Fannie Mae’s was about $227.0 billion at year-end 2025, with about $230.5 billion expected by the end of March 2026.
Treasury also holds warrants for 79.9% of fully diluted common shares at a nominal price. A warrant is the right to buy shares later at a set price. On top of that, the Enterprise Regulatory Capital Framework (ERCF) sets minimum capital levels that the companies must hold before any conventional release. The size of the capital gap is large, although no directly comparable recent retained-capital figure for both companies has been verified.
Your view of the common shares should also account for how Fannie Mae’s quarterly earnings are built, since fair value shifts and cost cuts, not core operations, drove much of the recent profit growth and the $112.7 billion net worth.
| Item | Figure or rule | Why it blocks a clean exit |
|---|---|---|
| Senior preferred | Fannie about $230.5B, Freddie $143.0B (expected, 31 Mar 2026) | Treasury is repaid ahead of common holders |
| Treasury warrants | 79.9% of fully diluted common | Exercising them would heavily dilute existing shareholders |
| ERCF minimums | 4.5% CET1, 6.0% Tier 1, 8.0% adjusted total, 2.5% leverage | A large capital gap must be closed first |
| 2012 net-worth sweep | Profits sent to Treasury | Left thin capital and years of litigation |
An initial public offering (IPO) would not simply hand fresh money to the companies. Fannie Mae’s net cash from new equity generally must reduce Treasury’s liquidation preference, although it may keep up to $70 billion in gross proceeds from common stock sales.
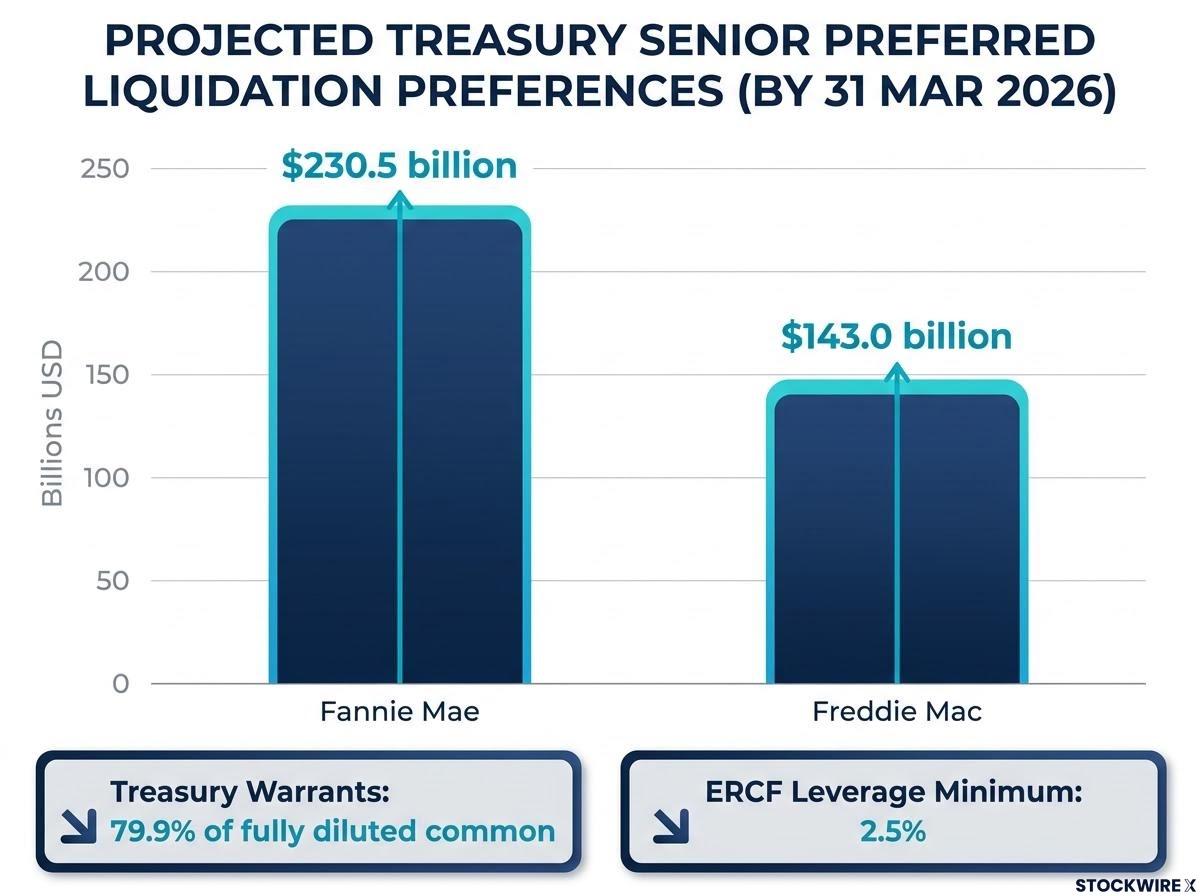
If you hold or are considering the shares, this means headline offering sizes say little about whether common holders recover value. Treasury’s claims sit ahead of yours.
The legal and operational problem
Former Federal Housing Finance Agency (FHFA) director Mark Calabria has argued that capital was always the central constraint, because the companies were leveraged roughly 1,000 to 1 before 2008. The August 2012 net-worth sweep made that worse. It sent essentially all profits to Treasury, left the companies with little capital and triggered shareholder lawsuits that are still active, with jury-related reporting appearing in October 2026.
Then there is readiness. Chris Whalen of The Institutional Risk Analyst argues that neither company has done the preparatory work on management, systems and controls needed to operate privately again.
When big ASX news breaks, our subscribers know first
How does government ownership hold up the AAA/AA ratings?
The ratings send what looks like a mixed signal. Freddie Mac’s senior debt is rated just below the US government, while its preferred stock is rated deep in distress.
| Agency | Instrument | Rating | Note |
|---|---|---|---|
| Moody’s | GSE senior debt | Aa1 | Cut from Aaa in May 2025 |
| S&P | Freddie Mac senior debt | AA+ | Stable |
| Moody’s | Freddie Mac preferred | Ca | Deeply distressed |
| S&P | Freddie Mac preferred | C | Deeply distressed |
The gap makes sense once you see what is being rated. The bonds score highly because the market expects extraordinary government support in a crisis. In effect, the senior debt rating is a rating on Washington’s backing.
That support is implicit rather than explicit. An implicit guarantee is one investors assume exists but that no law requires. Each company’s charter contains only a $2.25 billion Treasury credit line, and making support explicit would require legislation.
Whalen goes further. He asserts that the US owns 95% of both companies on a fully diluted basis, and that Moody’s and S&P would probably downgrade them if US ownership fell below 50%. These are his claims and have not been independently verified. The documented figure is the 79.9% warrant.
Chris Whalen’s view: The public adds nothing to the companies’ credit quality. It is US support that earns them AAA/AA status.
The Urban Institute finds that funding spreads would rise in proportion to how much support is removed. It estimates that guarantee fees could rise by about 10-25 basis points after conservatorship ends. A basis point is one hundredth of a percentage point. Jim Parrott and Mark Zandi estimate that more privatised structures could lift 30-year mortgage rates by about 43-97 basis points. Other commentary puts the increase at 60-90 basis points if no credible backstop exists.
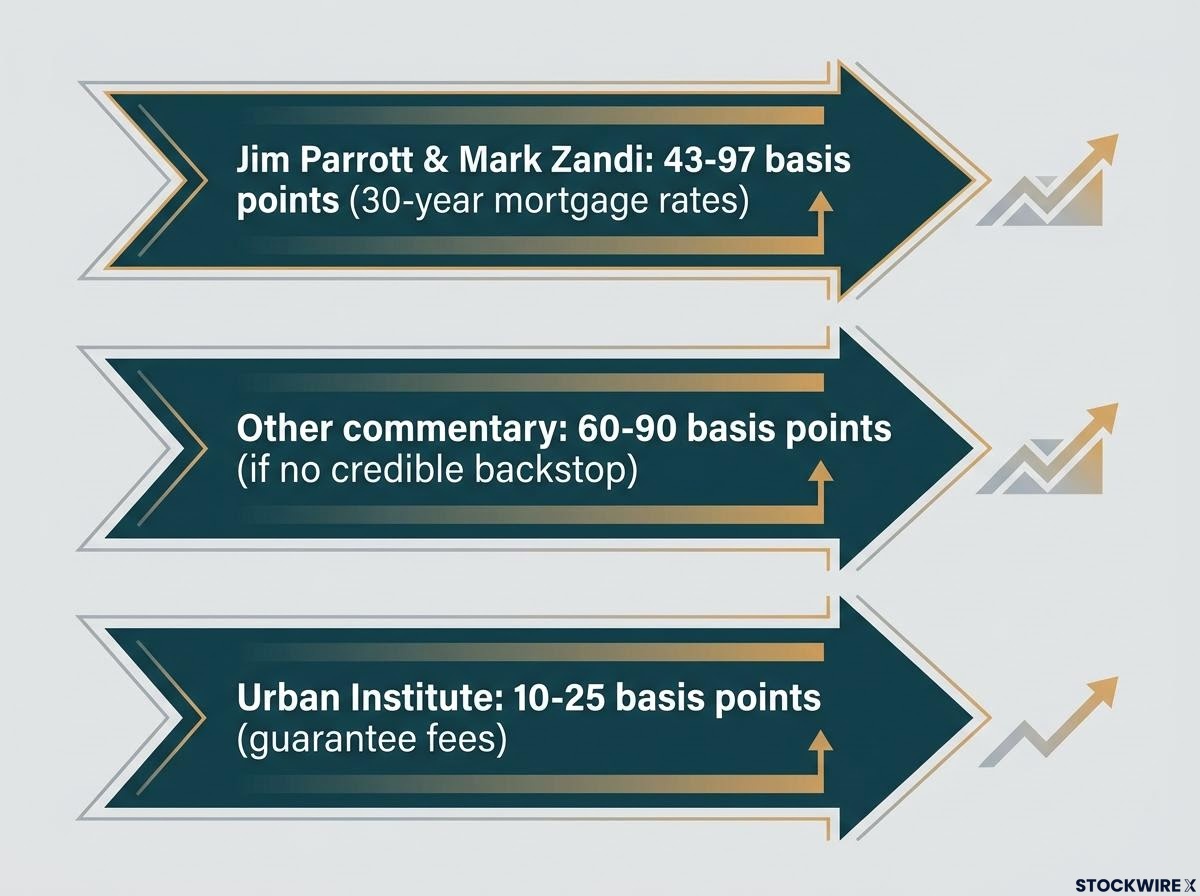
That explains Bessent’s reported test: take no action that pushes long-term mortgage rates higher. It also means the bond rating and the value of the common shares can move in opposite directions. A release that helps shareholders could raise funding costs for the companies and for borrowers.
The stakes are real because mortgage rate pressure is already squeezing the market, with the Freddie Mac 30-year rate at 7.40% in October 2026, so any release that lifts funding costs would land on borrowers and lenders already under strain.
What are the realistic alternatives, and what does history say?
The options on the table
Fannie Mae and Freddie Mac are government-sponsored enterprises (GSEs). These are companies owned by shareholders that perform a public policy role, chiefly buying mortgages and packaging them into securities. Any release has to decide which of four models they become:
- An ordinary private financial company
- A private company with an explicit federal guarantee
- A government-backed utility with regulated returns
- A shareholder-owned company still relying on an implicit guarantee
The near-term option looks smaller than any of these. Reporting points to a sale of roughly 3%-6%, or up to 5%, while conservatorship continues. Whalen proposes a different route: buy back public common shares, make the government the sole equity holder, and let the public hold non-voting preferred stock and debt.
| Option | Main argument | Main risk |
|---|---|---|
| Full privatisation | Market discipline, no taxpayer exposure | Higher rates without a backstop |
| Recapitalise and release | Build capital, then exit | Dilutive and legally contested |
| Partial IPO | Raises money, builds a public market | Government stays in control |
| Utility model | Regulated returns, explicit catastrophic guarantee | Capped returns, taxpayer risk |
| Continued conservatorship | Avoids a disruptive transition | Effectively permanent, litigation continues |
| Stronger federal guarantee | Protects low-cost mortgage funding | Large contingent taxpayer liability |
| Whalen’s model | Honest about control, preserves ratings | Common holders shifted into preferred |
Parrott argues that keeping an implicit guarantee while returning the companies to public ownership looks more like a regulated utility than a genuine private exit.
What history shows
- 1968: Fannie Mae became shareholder-owned; Whalen calls this Vietnam-era move deficit window-dressing
- 1970: Freddie Mac was created, becoming shareholder-owned in 1989
- September 2008: Conservatorship began under the Housing and Economic Recovery Act, with senior preferred and 79.9% warrants
- August 2012: The net-worth sweep began
- September 2019: Treasury’s reform plan produced no release
Each “privatisation” changed the label while the expectation of federal support stayed in place. So when you see a headline saying “IPO”, it most likely describes a partial sale of the government’s position, not the end of government control.
How should you judge the next official comment about a release?
The past week shows the pattern clearly.
| Event | Date | Share reaction |
|---|---|---|
| Orderly release framework disclosed | January 2025 | Multiyear highs |
| Trump’s roughly $1 trillion valuation remark | June 2026 | Shares surged |
| Bessent ownership comments | 20 October 2026 | FNMA up about 14% to $3.89; FMCC up about 14% to $3.59 |
| Retreat | 23 October 2026 | FNMA about $3.58 |
Whalen labelled Bessent’s remarks a “pump and dump”, which is his characterisation of the rally-then-retreat pattern. Look closely at what officials actually committed to. President Donald Trump said in June 2026 that an IPO was “on the table” but there was “no rush.” Bessent pointed to 2027 or 2028. FHFA Director Bill Pulte said conservatorship would continue during any sale of up to 5%.
Run any new statement through five questions:
- Does it name a structure?
- Does it address Treasury’s senior preferred and warrants?
- Does it say who provides the guarantee?
- Does it show the effect on mortgage rates?
- Does it give a date and a decision-maker?
These shares are highly speculative. Their prices reflect hopes for favourable treatment of Treasury’s claims, the warrants and legacy lawsuits, not operating earnings, and active litigation adds another layer of risk.
A statement that answers none of the five questions is sentiment, not a plan. Weigh it accordingly in your own thinking.
What a partial sale changes, and what it leaves untouched
A limited offering of roughly 3%-6% is plausible. A full release requires solving four problems at once: recapitalising to ERCF standards, resolving Treasury’s senior preferred and 79.9% warrants, choosing between an explicit and an implicit guarantee, and avoiding a rise in 30-year mortgage rates.
Whalen’s readiness and ratings arguments explain why officials can discuss an IPO without ending conservatorship. Selling a slice keeps the government’s backing, and the ratings, intact.
Bessent’s 2027-2028 window is the next marker. Until then, watch three variables: how Treasury treats its senior preferred, whether guarantee legislation advances, and how the litigation resolves.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Forward-looking statements are speculative and subject to change based on policy and market developments.