Kevin Warsh offered markets almost nothing on Thursday, and the euro still climbed. The new Federal Reserve chair gave no fresh guidance on interest rates. That silence cut the market-implied odds of an October Fed hike from 26% to 14%, showing that what a central banker leaves out can move a currency as much as what they say.
EUR/USD traded around 1.1230 in Asian hours on 16 October 2026, recovering from a 17-month low of 1.1113. The rebound looks tidy on a chart, but three forces are competing to explain it: the gap between US and eurozone short-term yields, stress in French government bonds, and how much European Central Bank (ECB) tightening is already priced.
Each driver points to a different euro dollar forecast, and trading the wrong one can be costly.
Here is how to separate the yield-gap story from the French bond story, and how to tie both to the chart levels that will settle the pair’s next move.
Why did Warsh’s silence lift the euro?
Traders expected some signal on the Fed’s next step, and they did not get one. Warsh said the Fed remained focused on its inflation goal and had not “pre-judged meetings.” He spent much of his time on artificial intelligence and how it might change the way monetary policy is run.
Strategists at MUFG and Scotiabank both read the absence of hawkish language as a signal. Hawkish means leaning towards higher interest rates to fight inflation.
Dovish by omission MUFG described Warsh’s comments as dovish “by omission”: no hawkish guidance was offered, so markets saw them as broadly consistent with existing pricing.
The transmission from a quiet press appearance to a firmer euro ran in four steps:
- Warsh offered no fresh guidance, and October Fed hike odds fell from 26% to 14%.
- The US two-year Treasury yield fell about 3-4 basis points (a basis point is one hundredth of a percentage point).
- Short-maturity yield spreads between the eurozone and the US narrowed modestly.
- The euro rose as the dollar’s yield advantage shrank.
The dollar was broadly unchanged at first. This was a spread story, not a broad dollar sell-off. MUFG still expects a December Fed hike but argued that pricing for multiple hikes in 2027 looks excessive.
That distinction matters for you. The euro’s lift came from markets repricing the Fed’s path, not from any new strength in the eurozone economy, so it lasts only as long as that repricing holds.
How to read a two-year spread
A front-end yield differential is the difference between short-term government bond yields in two countries. Two-year yields are used most often because they move closely with where traders expect central bank rates to go over the next couple of years.
Interest rate differentials work because markets price expected policy paths rather than current settings, which is why a quiet press appearance can shift the euro when it nudges the Fed’s anticipated trajectory lower.
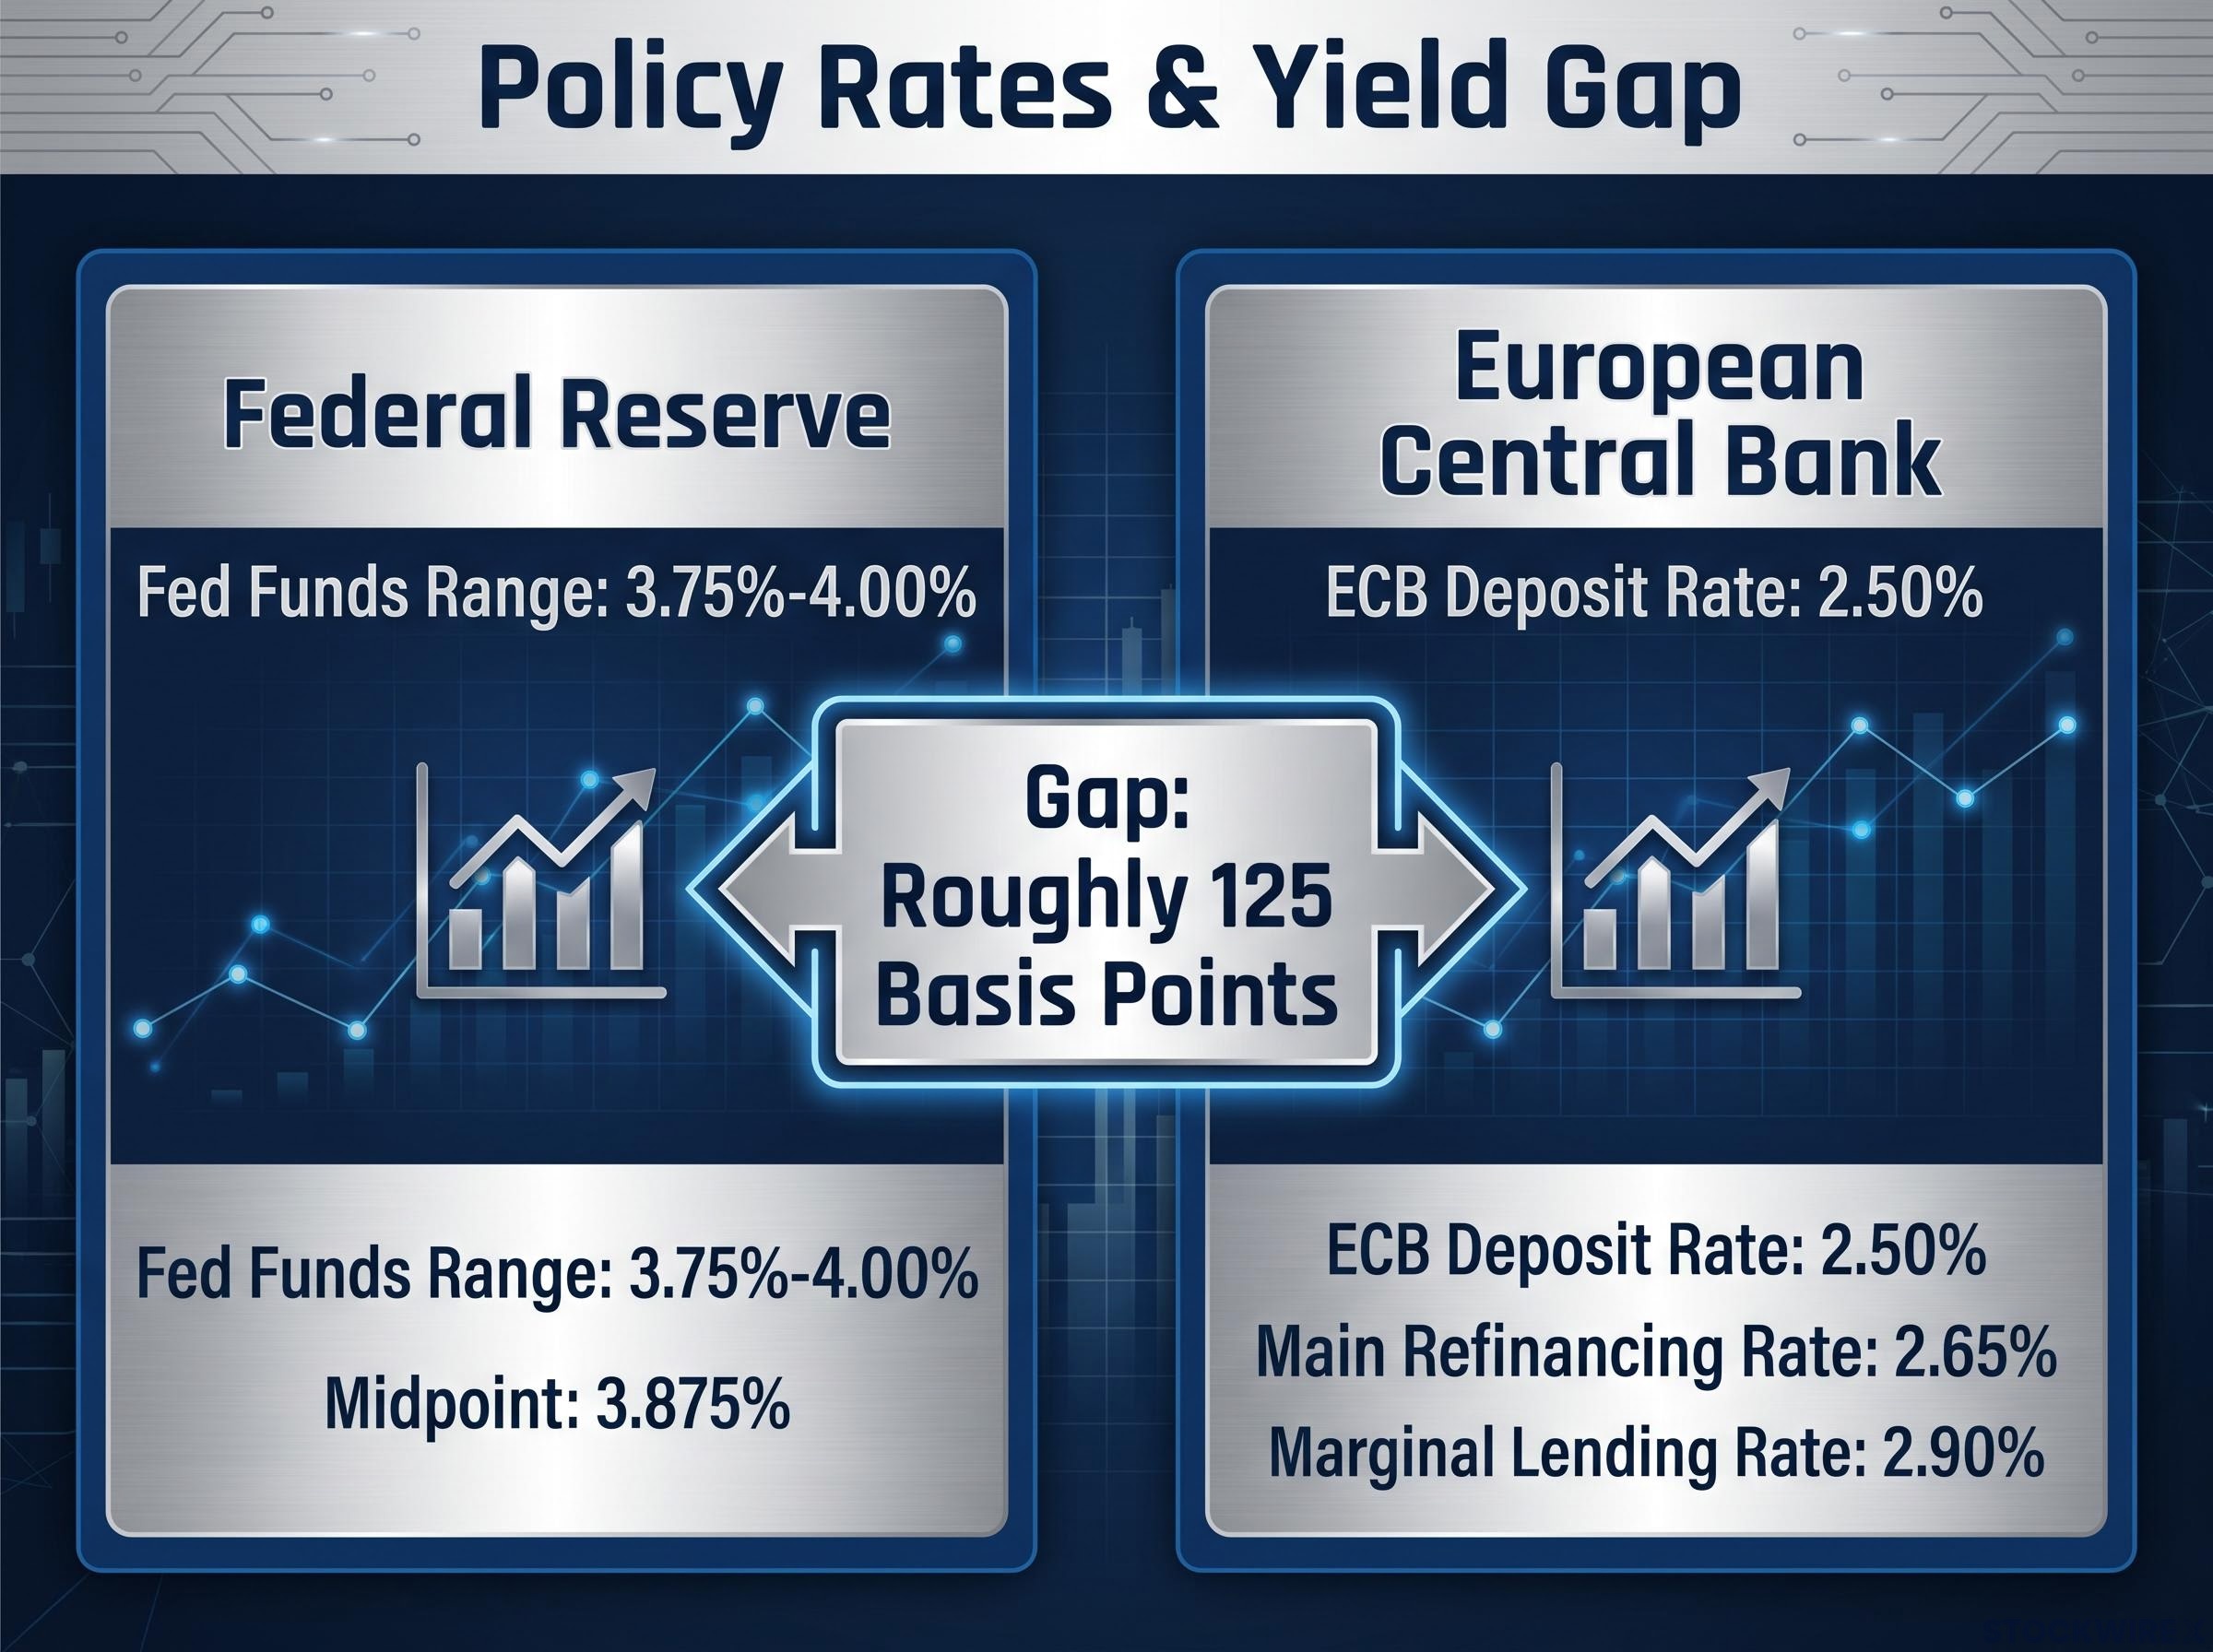
Take today’s policy rates. The Fed funds range sits at 3.75%-4.00%, a midpoint of 3.875%, while the ECB deposit rate is 2.50%. That leaves a gap of roughly 125 basis points in the dollar’s favour. When the gap shrinks, holding dollars pays less extra, and the euro tends to benefit.
When big ASX news breaks, our subscribers know first
What are French bonds really telling the euro?
Earlier this month, the headlines looked alarming. The spread between 10-year French government bonds (OATs) and German government bonds (Bunds) neared 150 basis points, its widest since late 2011. That spread is the extra yield investors demand to hold French debt instead of German debt.
The sell-off has since calmed. Scotiabank put the spread at about 135-140 basis points on 16 October, while Morningstar measured roughly 141 basis points on 15 October. The difference between the two figures likely reflects when each was observed.
The French bond spread widened partly because deficit concerns and the limits of ECB backstop tools have made Paris the focal point of eurozone credit risk, even as the sell-off eased from its early October peak.
The 2011 echo is real, but the comparison breaks down quickly. A commentary led by Anshul Gupta called the 2011-12 parallels overstated, because this episode is a French fiscal and political problem rather than a banking crisis. Bank funding and credit markets are not showing that kind of stress.
Scotiabank’s view is that the euro’s link to sovereign spreads “tends to be episodic”. According to its strategists, spread widening hits EUR/USD mainly when it:
- Changes expected ECB policy by tightening financial conditions and making hikes less likely
- Raises contagion risk, so French stress starts to look like a wider eurozone problem that lifts demand for dollars
- Creates financial-system stress that threatens banks or market functioning, which produces a much sharper currency reaction
Not everyone is relaxed. Citi rates strategists argue that wider French spreads may signal ECB policy is already too restrictive and could force an earlier pause, which would weaken the euro. UBP called the sharp rise in French yields negative for the currency.
| Period | Spread move | EUR/USD response | Interpretation |
|---|---|---|---|
| Early to mid October | OAT/Bund toward ~150 bp, then ~141 bp by 15 Oct | Fell to a 17-month low near 1.1113, then rebounded | Moved together: French stress weighed on ECB hike expectations |
| 16 October | Holding near 135-140 bp | Rose, with a possible bullish weekly reversal | Divergence: lower US short-end yields became the main driver |
| 12 October (ING outlook) | More volatility expected | Broad 1.10-1.15 range | No one-for-one daily link anticipated |
The practical read is to treat French spread moves as a conditional risk flag for EUR/USD, not a daily trading signal. Watch for those three channels before acting on an OAT headline.
Does ECB hike pricing cap or cushion the euro?
The French question feeds directly into the ECB debate, and analysts are genuinely split. The ECB deposit rate stands at 2.50%, with the main refinancing rate at 2.65% and the marginal lending rate at 2.90%.
Markets price about an 11.7% chance of a 25 basis point hike on 29 October and roughly 78% for December. Scotiabank calls the December move almost fully priced.
Economists polled ahead of the meeting overwhelmingly favour an ECB rate hike in December rather than October, citing inflation near 3.8% and oil above $100 as the forces pushing the debate towards a higher peak.
One camp sees fiscal stress doing the ECB’s job for it. Goldman Sachs and Citi argue that wider spreads tighten financial conditions and reduce the urgency to hike. Marcin Marinov at Credit Agricole pointed to 2022, when peripheral spread widening restrained the ECB, and noted that the EUR/USD rate spread has weakened without collapsing.
The other camp still sees room to tighten. Nomura expects hikes in December and March, taking the deposit rate to 3.00%, while ING forecasts one final hike to 2.75% in December.
| Institution | Date | View | EUR/USD implication |
|---|---|---|---|
| Scotiabank | 16 Oct | December hike almost fully priced; French spreads secondary | Fair value 1.1285 |
| MUFG | 16 Oct | Wider French spreads a downside risk | Possible move toward 1.10 |
| ING | 12 Oct | Final hike to 2.75% in December | Range 1.10-1.15 |
| Goldman Sachs | 4 Oct | Spreads reduce hiking urgency; December likely final | Limits ECB support for the euro |
| Citi | October | Wider spreads may force an earlier pause | Euro negative |
| Nomura | 7 Oct | Hikes in December and March to 3.00% | More rate support than consensus |
ING baseline ING expects EUR/USD to hold a broad 1.10-1.15 range, with continued OAT/Bund volatility.
The split resolves once you focus on change rather than level. EUR/USD responds to shifts in the relative expected rate path, so a hike that is already priced adds little extra lift.
For you, that creates an asymmetry. Upside from fresh ECB hawkishness is likely limited, while any softening in December hike expectations is the larger risk to the euro.
Which EUR/USD levels decide the next move?
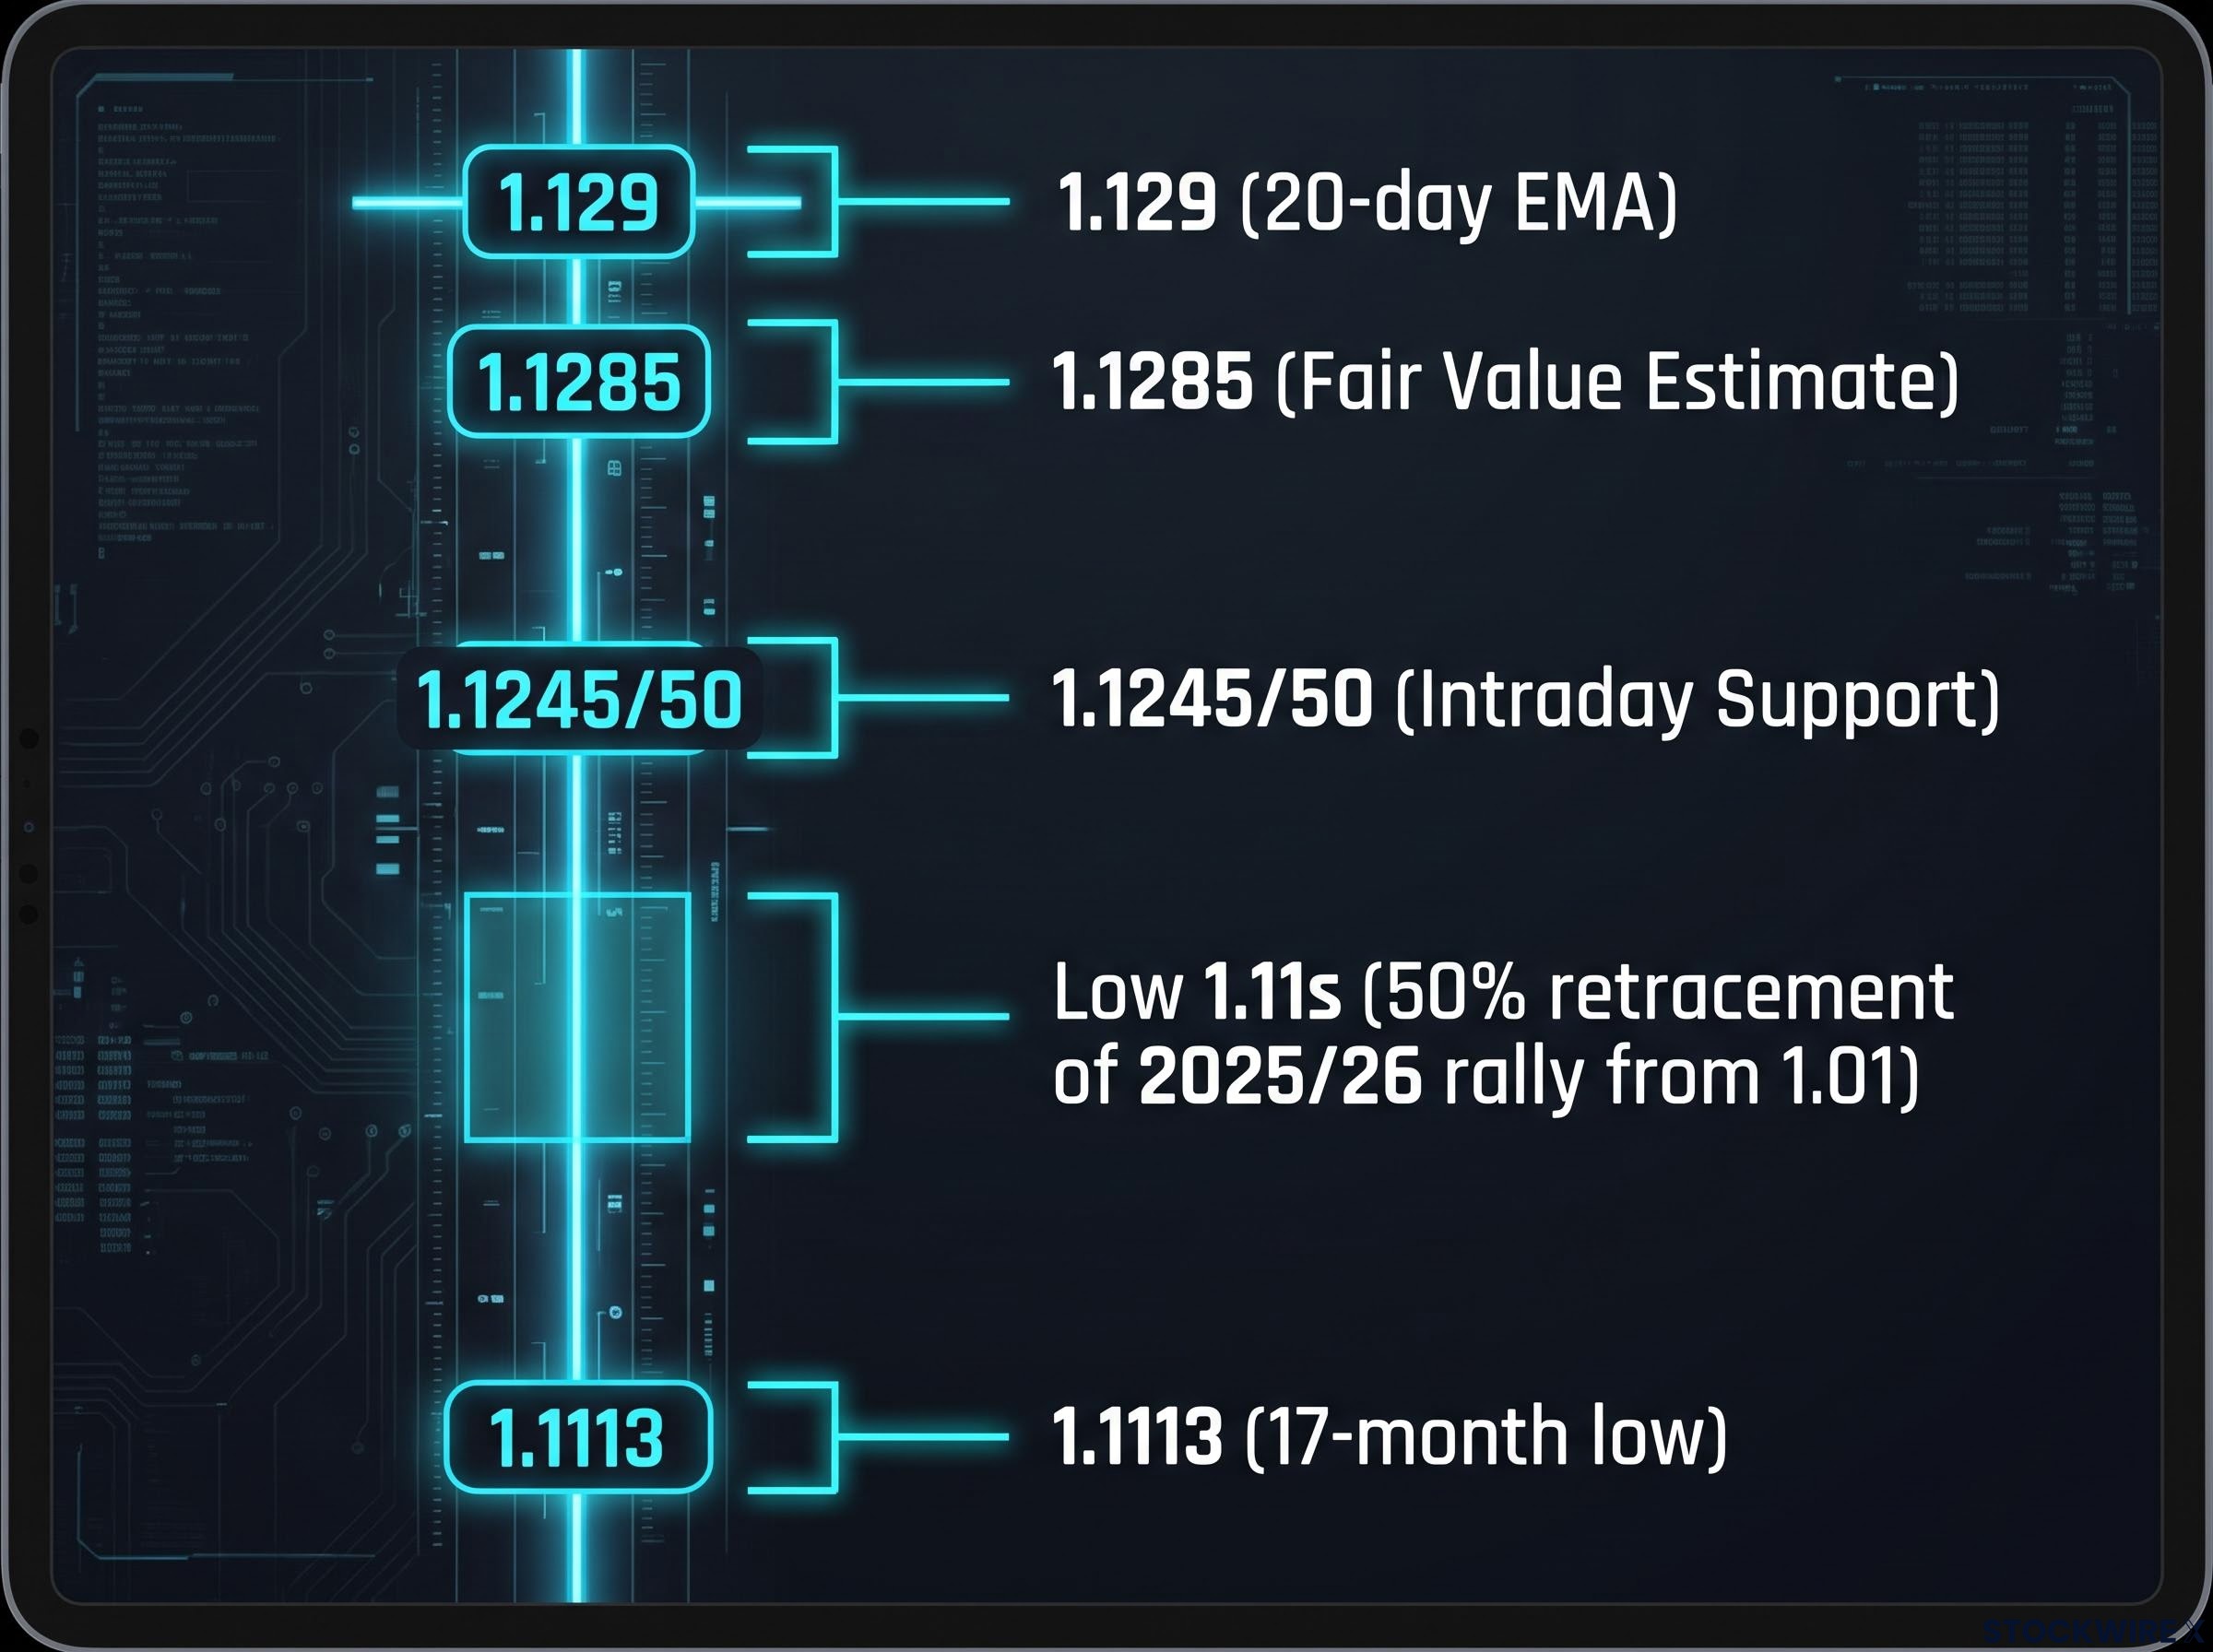
The chart offers a hopeful setup. Scotiabank’s levels, from resistance down to support, are:
- 1.129: the 20-day exponential moving average, a trend gauge that gives more weight to recent prices
- 1.1285: Scotiabank’s fair value estimate
- 1.1245/50: former resistance at 1.1240/50, now intraday support
- Low 1.11s: the 50% retracement of the 2025/26 rally from around 1.01, where the euro rebounded
- 1.1113: the 17-month low
The latest session range ran from about 1.1151 to 1.1269. Scotiabank sees a possible bullish weekly reversal, but only if the late-week gains hold through the close.
The caveat sits overhead. The pair remains below the 20-day average near 1.129, so the near-term trend is still vulnerable.
Support-to-resistance flips matter for the setup above, since former floors that fail often become ceilings; the 1.14 zone is a live example, where a stacked technical wall caps the pair unless the rate gap narrows.
What would confirm the setup:
- A weekly close that holds above 1.1240/50
- A sustained move through 1.129
- US two-year yields staying lower as Fed pricing settles
What would invalidate it:
- A slide back below 1.1245/50 and toward the low 1.11s
- Renewed widening in the OAT/Bund spread
- A rebound in US hike pricing
Bull case, bear case
The bull case rests on narrower front-end spreads and a confirmed weekly reversal. That would open a path toward fair value at 1.1285 and the top of ING’s range.
The bear case runs through Paris and Washington. MUFG warns that wider French spreads tied to budget uncertainty could push the pair toward 1.10, and ING names uncertain White House policy after the November midterms as the main upside risk for the dollar.
Read the chart and the yield gap together. A reversal that holds while US two-year yields stay lower carries more weight than one that rests on price alone.
What the yield gap settles, and what it leaves open
The rebound is mainly a front-end spread story. French bonds and ECB pricing act as secondary conditioners, with December already about 78% priced and October near 11.7%.
That ranking gives you a watch list:
- US two-year yields, the first variable likely to change the picture
- The 29 October ECB meeting
- The OAT/Bund spread against the 135-140 basis point zone
- The weekly close relative to fair value at 1.1285 and support in the low 1.11s
Yield spreads are not mechanical currency drivers. Their effect depends on whether a move reflects growth, inflation, fiscal risk or safe-haven demand. Size your conviction to the variable most likely to shift first, not to a single weekly candle.
Past performance does not guarantee future results. Forecasts and projections cited here are subject to market conditions and various risk factors, and may change as events develop.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.