ASML, the only commercial supplier of extreme ultraviolet (EUV) lithography systems, said on Wednesday that its planned supply for 2027 and 2028 will not fully meet customer demand. It is now investigating a 2028 capacity increase beyond the 30% it had already flagged. The warning arrived alongside record Q3 results, with net sales of €11.662 billion.
Net income reached €4.960 billion and gross margin hit 57.5%, both records, and full-year guidance moved higher. EUV machines print the smallest circuit patterns on advanced chips. When the sole maker of those machines says it cannot keep up, the effects reach AI chips, memory and the wider semiconductor equipment chain.
Here is what the numbers show, what the capacity warning means for chipmakers further down the line, and what could still go wrong.
Why ASML’s admission that supply will fall short is the real headline
Record quarters are common in a strong cycle. Supply warnings from a monopoly toolmaker are not.
CEO Christophe Fouquet said customers’ order visibility and rising order-book momentum now mean supply “as currently planned for both 2027 and 2028 will not fully meet the demand of our customers.” Every leading-edge chipmaker depends on ASML’s EUV tools, so this is a forward signal about the entire advanced chip industry.
Christophe Fouquet, Chief Executive Officer “Given this, we are investigating ways to increase capacity for 2028 beyond the 30% increase we previously communicated.”
The earlier plan, set out in a footnote to the release, lifted low-NA EUV and DUV-immersion capacity by about 30% in 2027, with a further 30% increase under investigation for 2028. Low-NA EUV refers to ASML’s standard EUV machines. DUV-immersion refers to older deep ultraviolet tools that still handle many chip layers.
Low-NA EUV tools print features through a 0.33 numerical aperture lens and sit alongside the newer High NA platform that Intel, Samsung and TSMC are evaluating at different speeds.
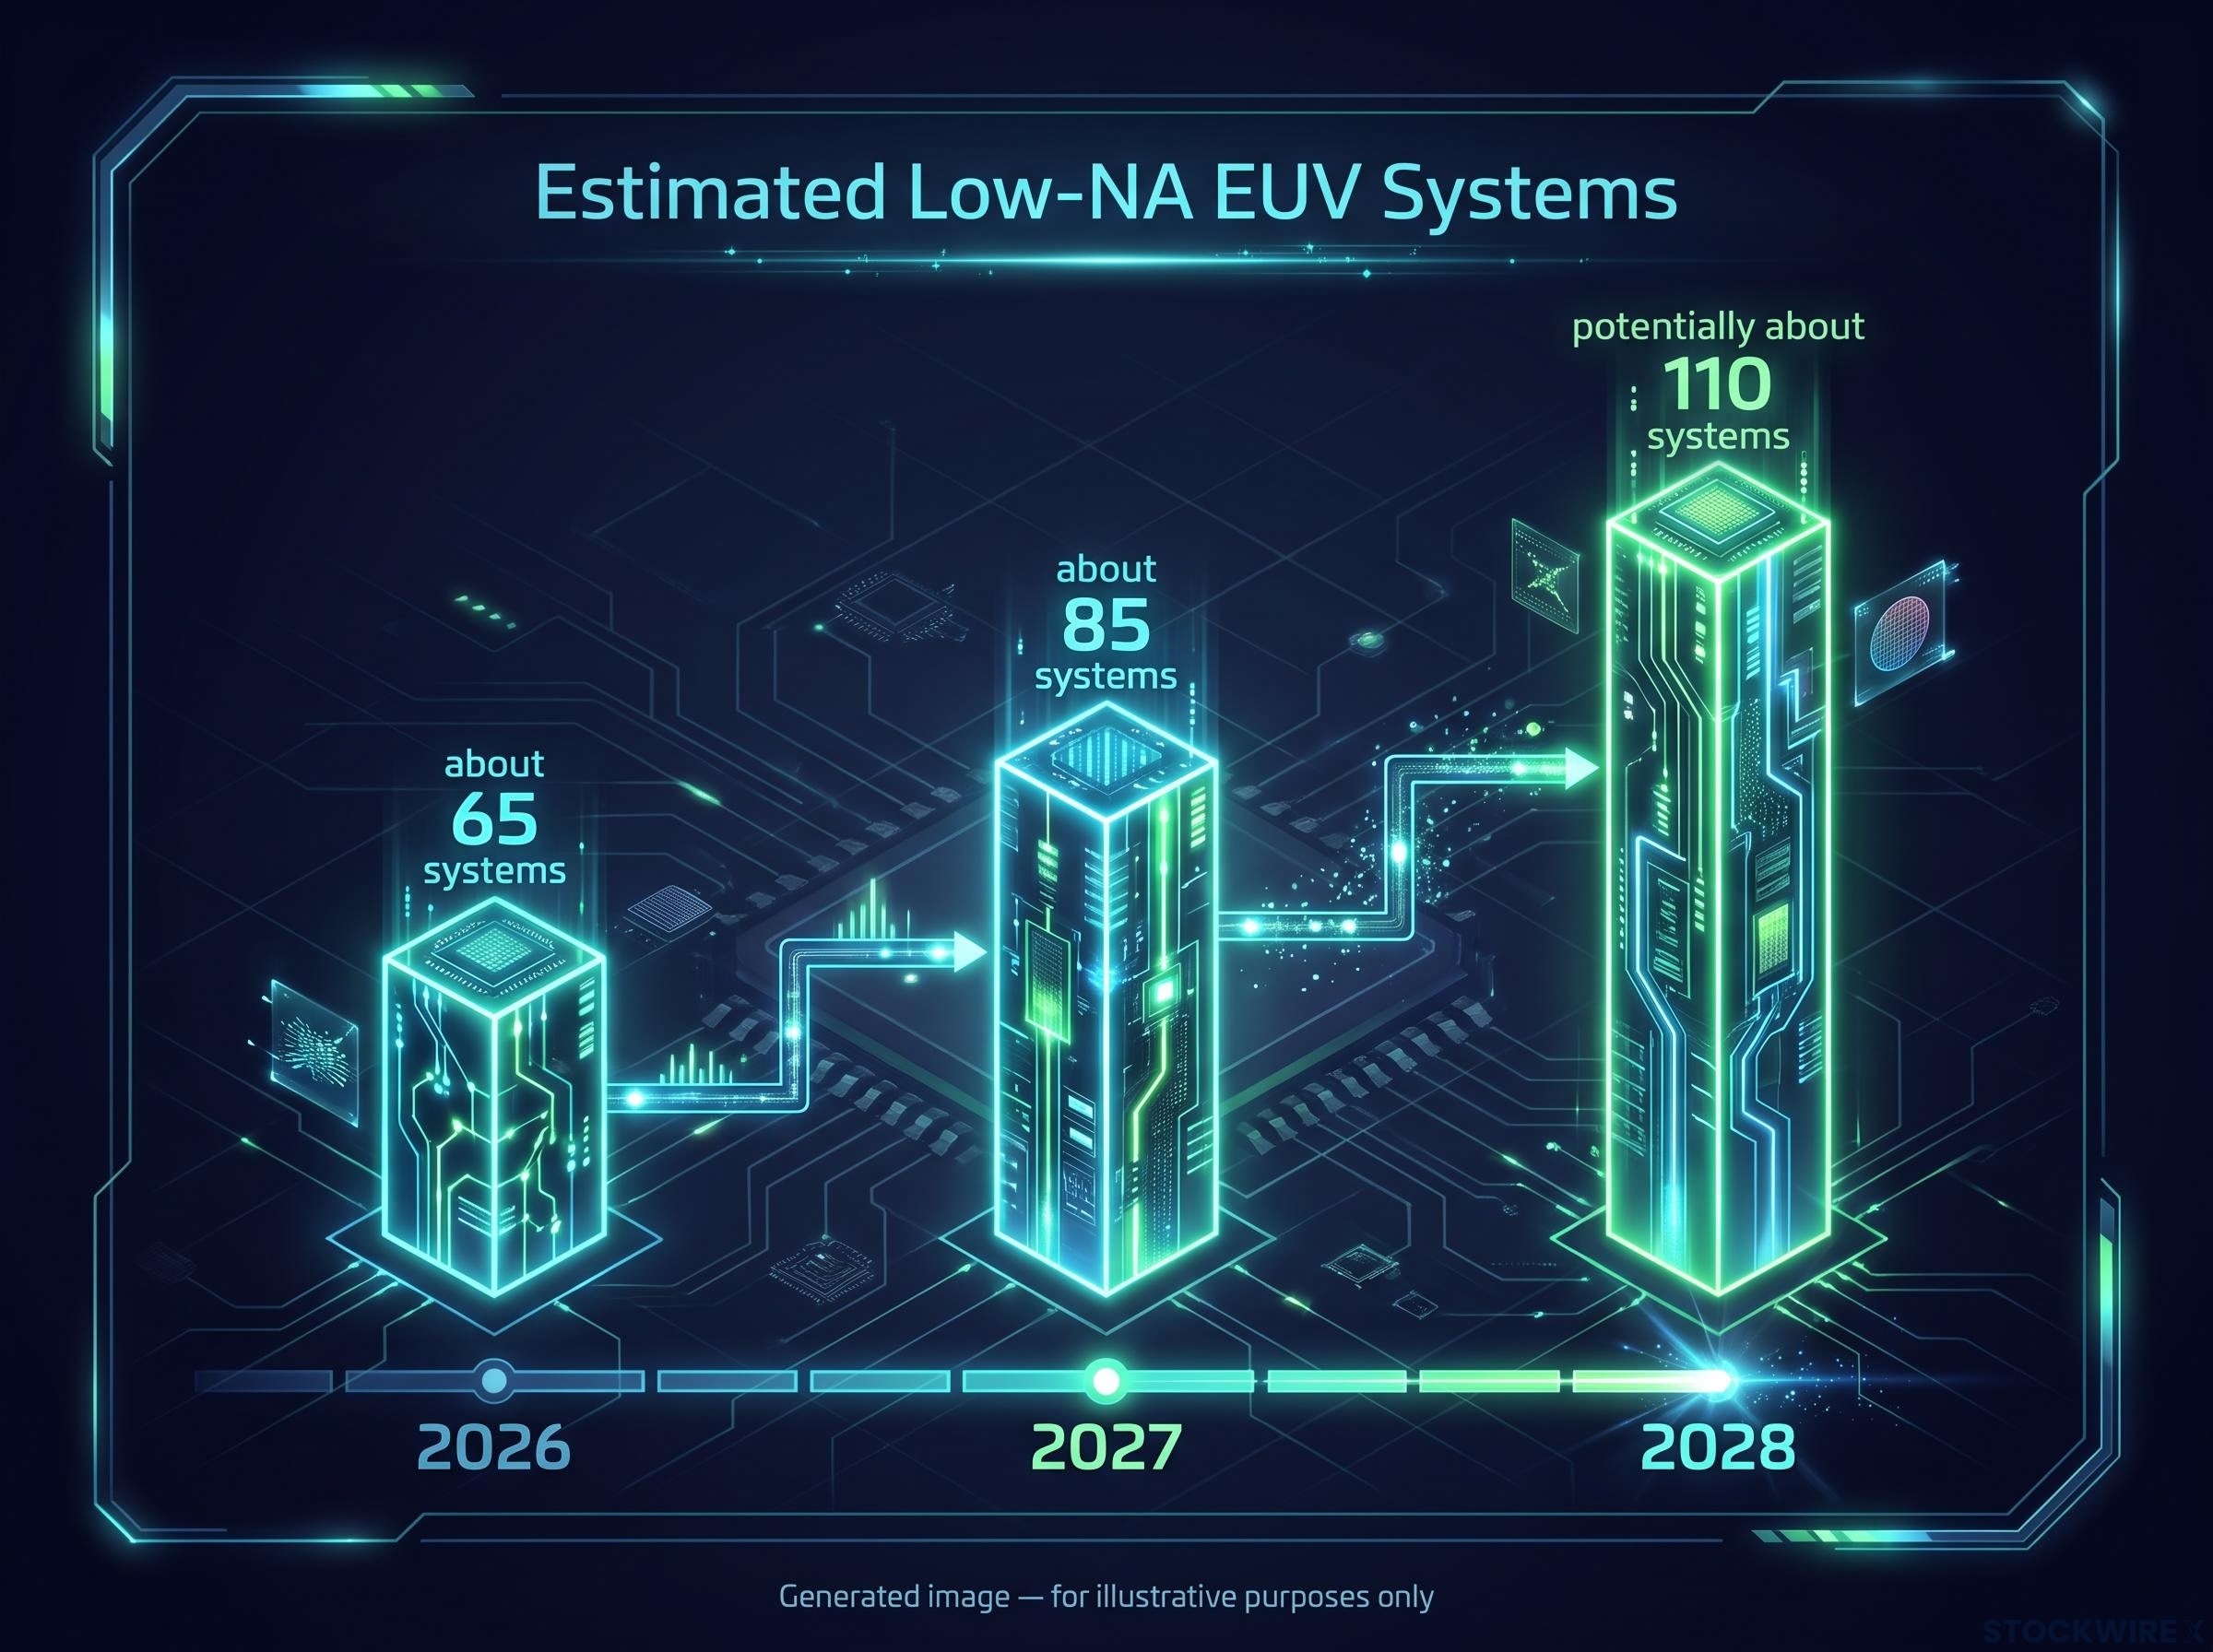
Pre-results reporting put rough unit numbers on that plan. These are secondary estimates, not ASML commitments:
- 2026: about 65 low-NA EUV systems
- 2027: about 85 systems
- 2028: potentially about 110 systems
ASML did not publish a separate net bookings figure, but it described order-book momentum as rising quarter on quarter. Customers are also looking much further ahead. “Some customers are expressing an interest in placing orders with us for 2029 and even 2030,” Fouquet said.
For you as an investor or industry watcher, a supplier that cannot meet demand two years out signals that chipmaker capital spending plans are being locked in long before the chips themselves are sold.
When big ASX news breaks, our subscribers know first
Record sales, margin and profit: what the Q3 numbers show
The step up from the June quarter was steep. Sales rose by roughly a quarter and net income climbed about 70%.
| Metric | Q3 2026 | Q2 2026 | Change |
|---|---|---|---|
| Net sales | €11.662B | €9.326B | +25.0% |
| Net income | €4.960B | €2.918B | +70.0% |
| Gross margin | 57.5% | 54% | +3.5 points |
| Installed Base Management sales | €3.289B | €2.762B | +19.1% |
Gross profit came to €6.700 billion. ASML sold 113 new and 8 used lithography systems. Installed Base Management sales, which cover servicing and upgrades to machines already in customer fabs, beat guidance on demand for productivity upgrades.
The picture is less tidy against expectations. LSEG consensus, cited by Morningstar, sat near €11.85 billion, leaving sales about €0.19 billion short, while Bloomberg consensus was closer to €11.7 billion. Consensus means the average forecast across analysts. A reported gross margin consensus of 55.88% has not been independently confirmed, but sales did clear the midpoint of ASML’s own Q3 guidance, and margin came in stronger.
| Metric | Guidance |
|---|---|
| Q4 2026 net sales | €14.2-€15.2B |
| Q4 2026 gross margin | Around 57% |
| Q4 2026 R&D / SG&A | Around €1.2B / around €0.4B |
| FY2026 net sales (raised) | €44-€45B |
| FY2026 gross margin | Around 56% |
What this means for you is that the guidance raise, not the small miss against one consensus figure, decides whether this quarter reads as a business strengthening or simply meeting expectations.
What is behind the AI-driven squeeze on EUV supply
Customers are giving ASML a clear reason for their bigger orders. Fouquet said they keep lifting short- and medium-term forecasts, “driven primarily by their views on the size and duration of AI-related investments.”
Hyperscaler AI capex is the upstream driver of these orders, with combined 2026 guidance near $725 billion and a $1 trillion annual run rate in view for 2027, which explains why customers are booking tools years ahead.
The harder question is why ASML cannot just build more. Several forces stack on top of each other:
- EUV lead times: each system needs lengthy assembly, qualification and installation, fed by a specialised global supply chain.
- Productivity upgrades: customers are squeezing more wafer output from installed tools, adding to service demand.
- Leading-edge logic: AI accelerators need the most advanced chip nodes, where EUV is required.
- Memory investment: ASML’s 2025 annual-report material said AI-server demand exceeded supply and DRAM and NAND demand increasingly outstripped it.
- Forecast-driven ordering: customers are booking years ahead, turning this into a capacity-planning problem rather than a one-quarter spike.
Christophe Fouquet, Chief Executive Officer “We now expect that our supply as currently planned for both 2027 and 2028 will not fully meet the demand of our customers.”
There is precedent. In 2025, ASML material showed customers planned about 30% more EUV capacity than in 2024, which ASML met with roughly the same number of NXE:3800E systems at higher selling prices and margins. The pattern tends to run the same way: chipmakers commit to capacity, then ASML expands tool supply.
That sequence is not guaranteed. Cycles can reverse between a forecast, an order and actual fab use.
For you, multiyear lead times suggest this constraint is likely to outlast a normal single-quarter upcycle, though memory and chip prices can still turn.
What could still go wrong, and how analysts are reading it
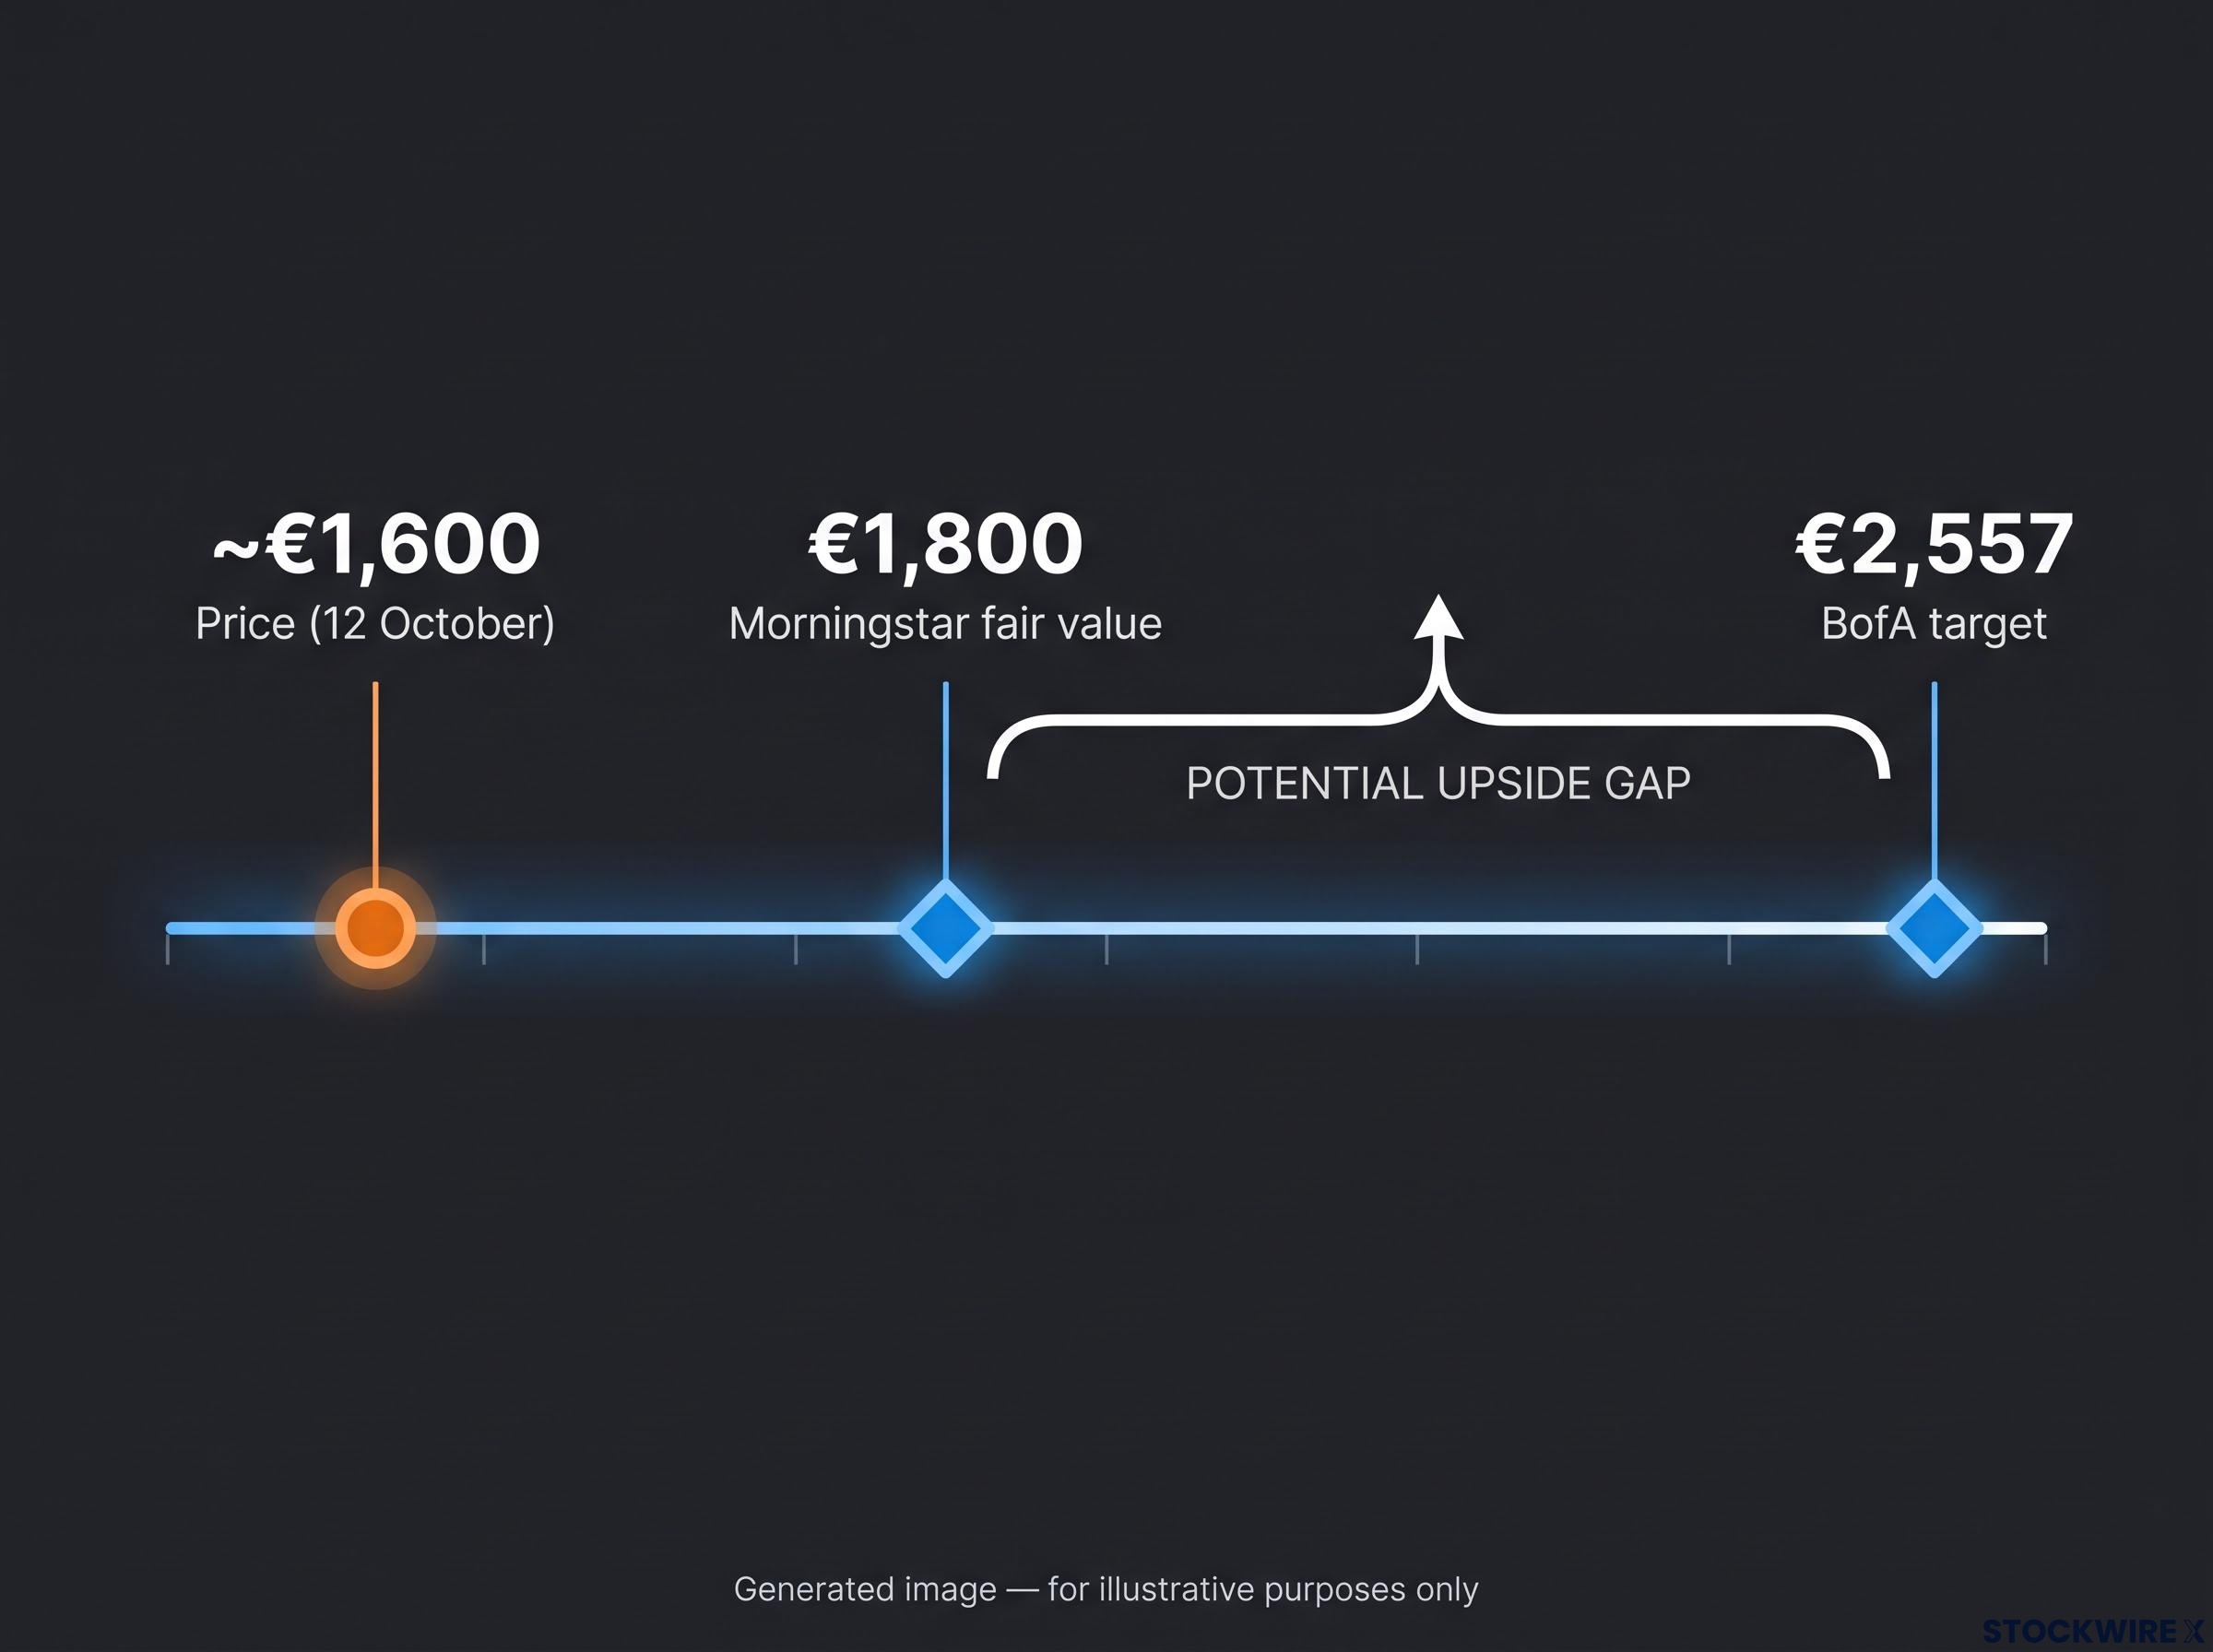
The bullish read is straightforward. BofA raised its price target from €2,452 to €2,557, citing higher like-for-like pricing and higher EUV and dry-system volumes, and argued AI demand is turning into real equipment volume and pricing power.
Not everyone is paying up. Morningstar held its fair value, its estimate of what the shares are worth, at €1,800. ASML was already up about 78% year to date and trading near €1,600 on 12 October. RBC suggested demand may be running ahead of expectations that were already elevated, while JPMorgan reportedly expected 2027 strength, a view not independently confirmed.
| Source | Stance | Figure |
|---|---|---|
| BofA | Bullish, target raised | €2,557 |
| Morningstar | Valuation-sensitive | €1,800 fair value |
| RBC | Expectations already elevated | No figure disclosed |
The risks are specific:
- AI-capex dependence: if hyperscalers or chipmakers slow spending, order visibility could fade quickly.
- China export controls: ASML cannot sell EUV to mainland China, which is still expected at roughly 20% of 2026 sales.
- Customer concentration: a handful of logic and memory makers drive advanced demand, so simultaneous delays would hurt.
- Execution: lifting 2028 capacity needs more suppliers, components, testing and field service.
- Over-expansion: building for peak AI demand could leave idle capacity if spending falls.
The cautious case holds that results may already reflect very high expectations if customers defer projects. No reliable post-release share price move was available at the time of writing.
ASML has never shipped an EUV system to China, yet export control scrutiny has intensified, and a valuation discount to US equipment peers has narrowed from roughly 84% to 6-15% as geopolitical risk is priced in.
For you, the gap between €1,800 and €2,557 shows the same results can support very different valuations. The capacity signal is evidence of demand, not a verdict on price.
What to watch after this record quarter
The record figures matter, but the capacity warning matters more. The sole EUV supplier says planned output falls short through 2028, while customers are already asking about 2029 and 2030.
Four variables will test that signal:
- Any formal 2028 capacity commitment beyond the current 30% plan
- Q4 delivery against the €14.2-€15.2 billion guide
- Signs of slowing AI capital spending from hyperscalers or chipmakers
- Shifts in China export policy
Tracking ASML’s quarterly order commentary alongside chipmakers’ capital spending updates gives you the earliest read on whether this squeeze tightens or eases.
For readers weighing the wider supply chain, our detailed coverage of chip equipment stocks shows why Citi favours KLA and Nova on rising estimates.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections and forward-looking statements are speculative and subject to change based on market conditions and company performance.