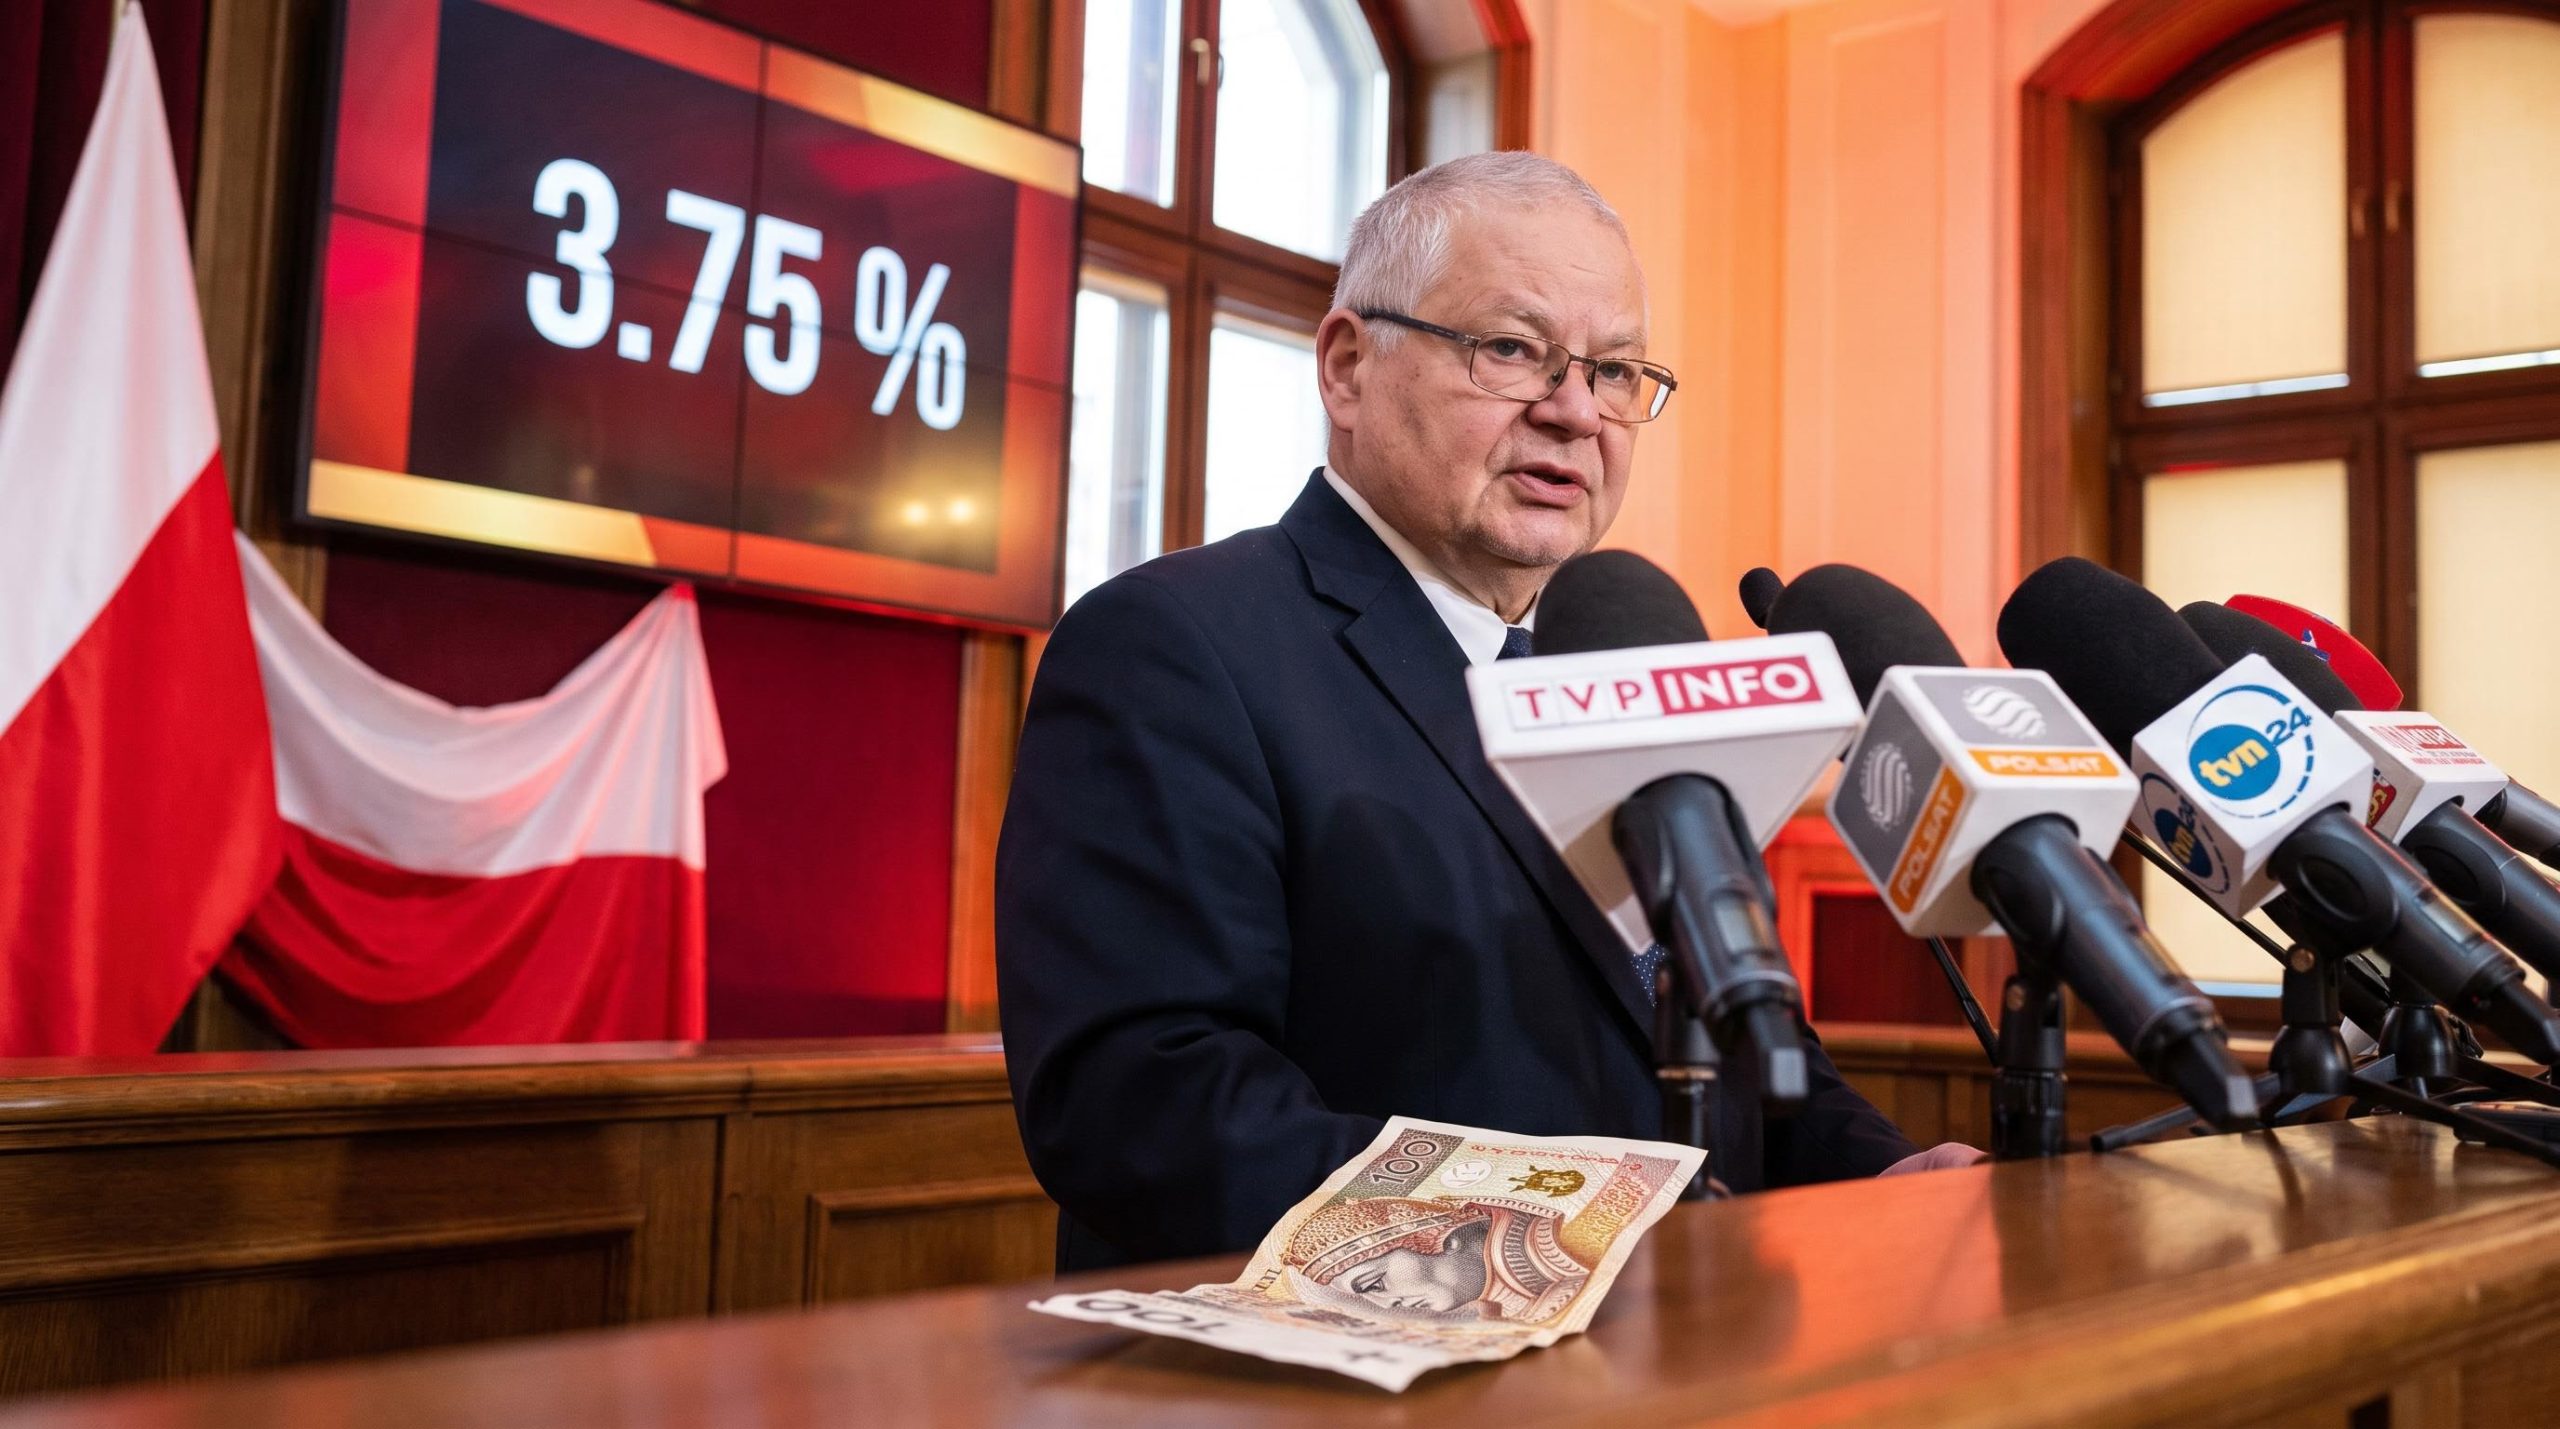
Poland’s central bank kept its reference rate at 3.75% this week, and Governor Adam Glapiński used his press conference on 8 October to leave the door to a November rate hike open, but only slightly. Traders had leaned toward a hike, and the zloty stayed weak, including against the Hungarian forint.
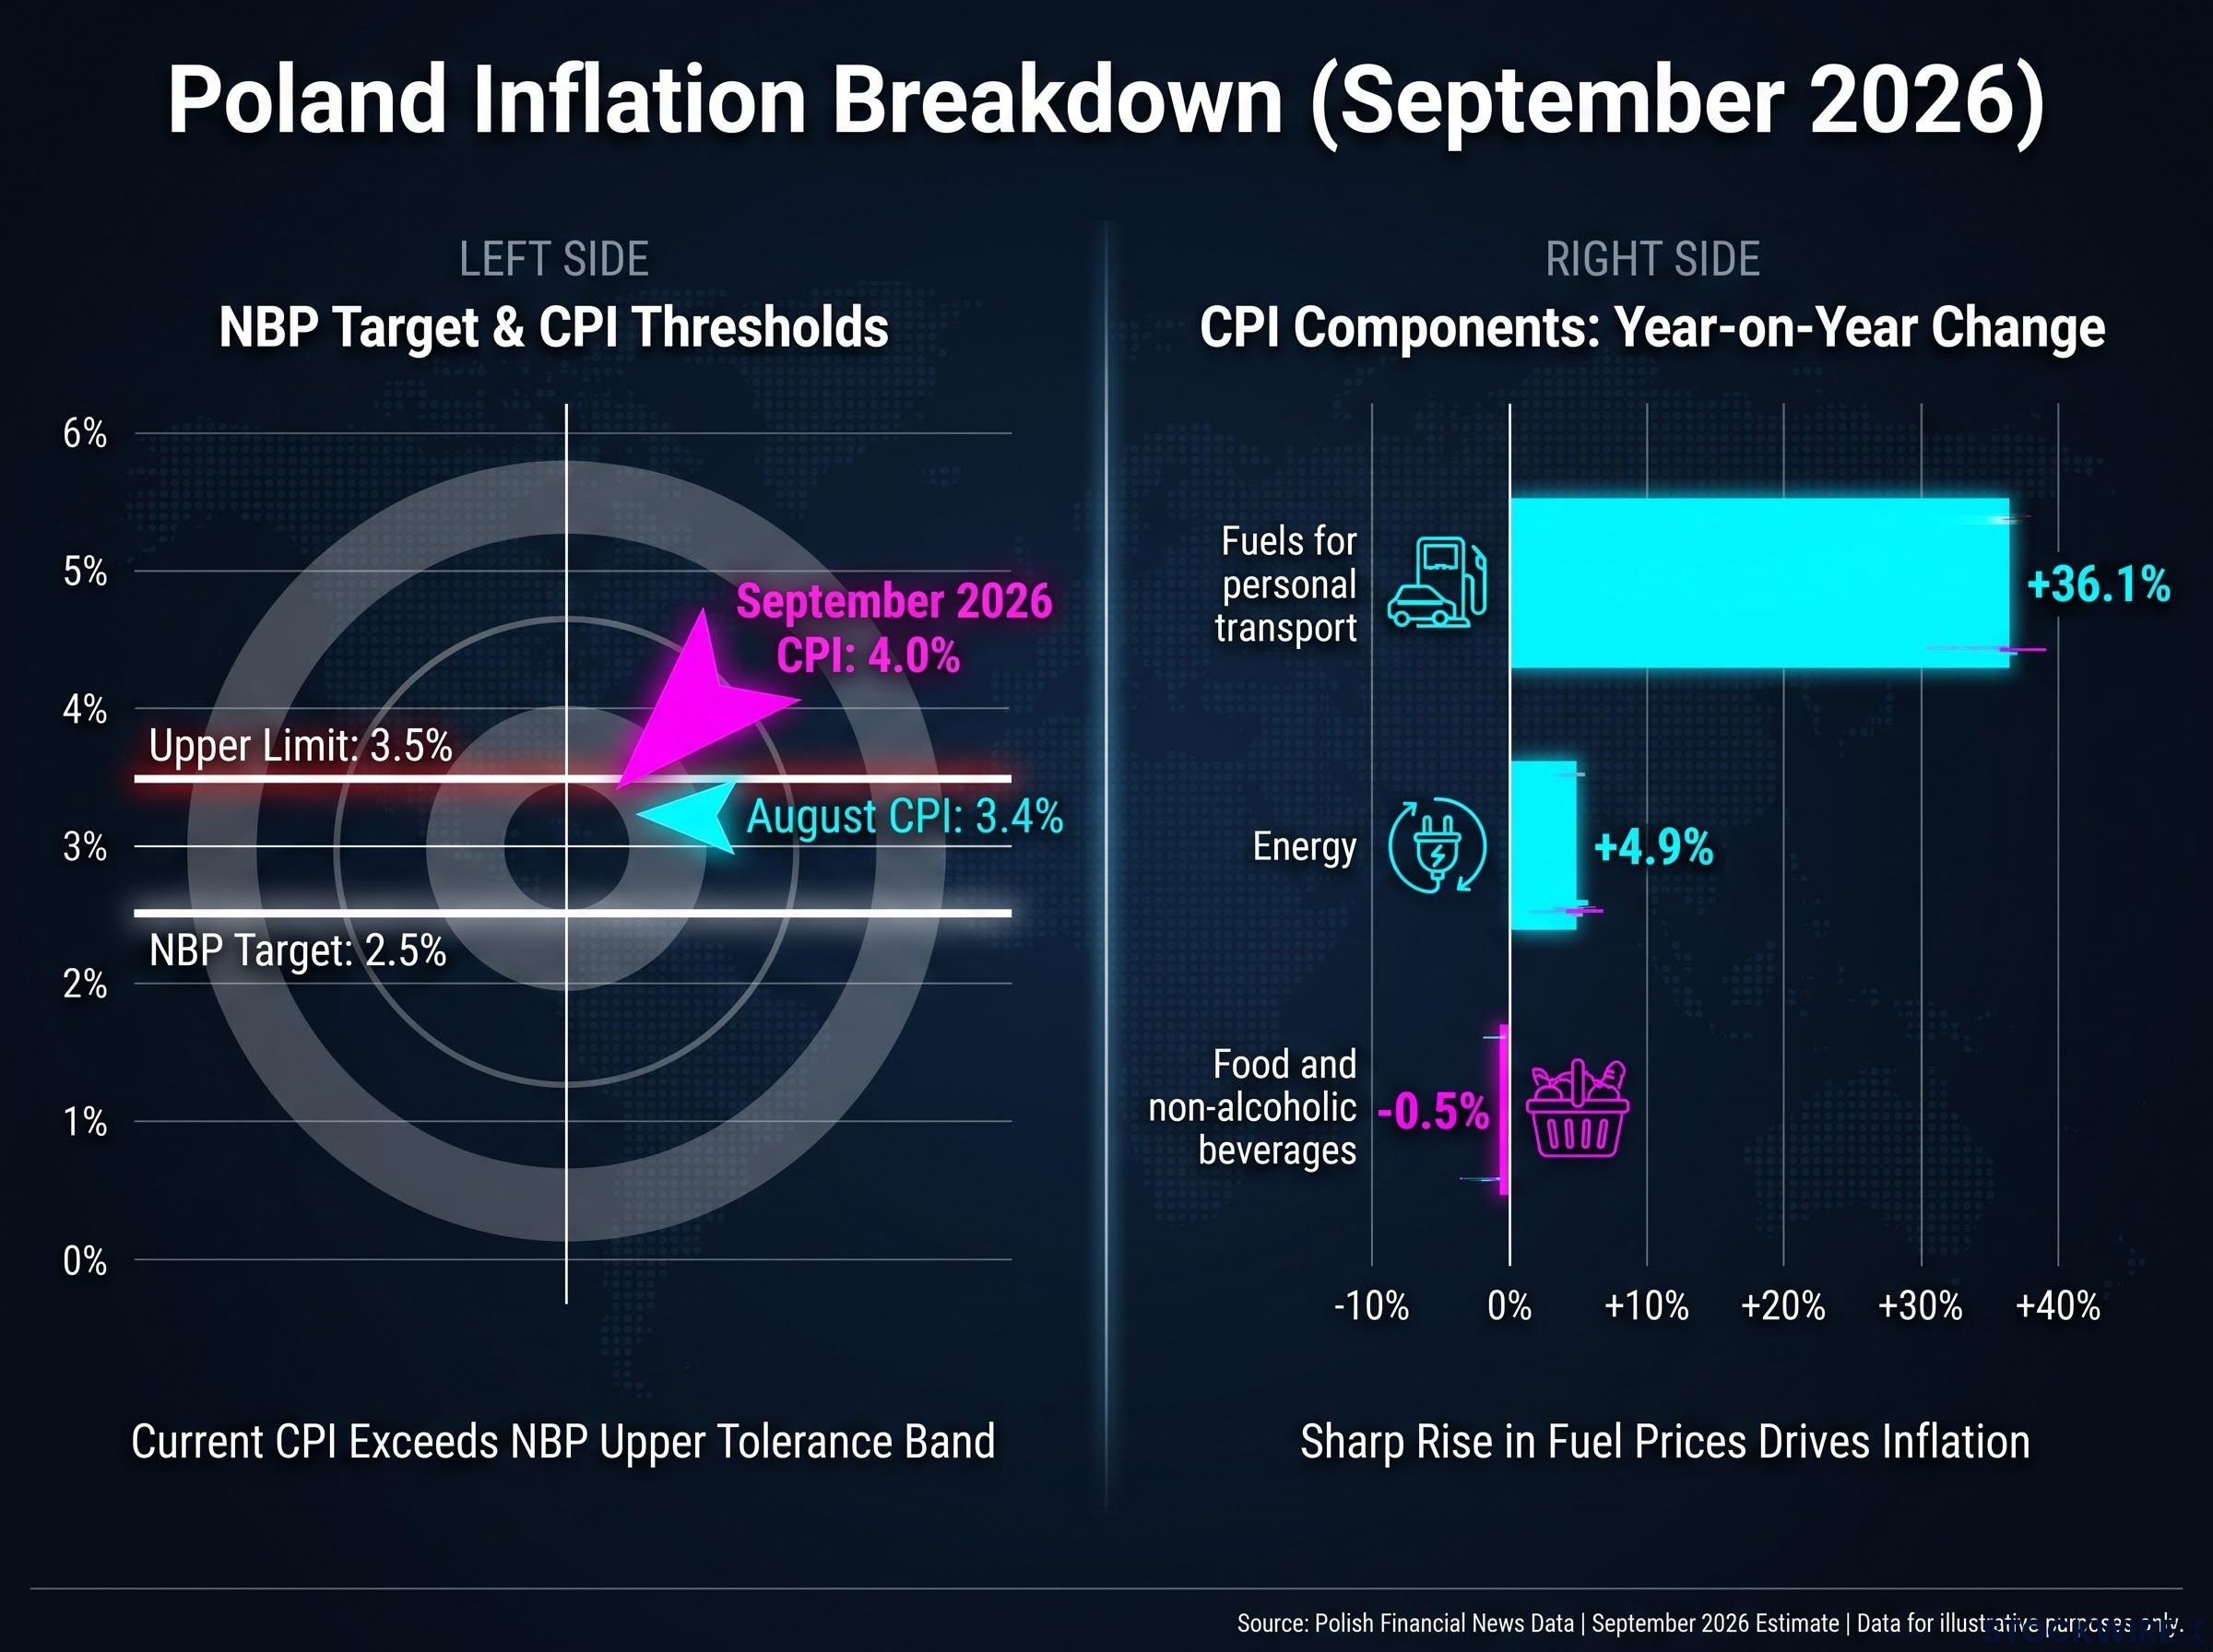
The pressure for a move came from inflation. Poland’s flash consumer price index (CPI) rose to 4.0% year on year in September 2026, above the 3.5% upper limit of the National Bank of Poland’s (NBP) target band of 2.5% plus or minus one percentage point.
A governor who sounds hawkish can still disappoint the people who had priced more than he offered.
Here is what Glapiński actually tied a hike to, why the market pulled back its bets, and which signals will tell you whether the case for tightening is building or fading.
Why did a hawkish-sounding press conference disappoint the market?
Going into Thursday, markets had drifted toward pricing a November hike. What arrived was a list of conditions.
The Monetary Policy Council (MPC) held all rates at its 6-7 October meeting: reference 3.75%, Lombard 4.25% and deposit 3.25%. Glapiński said the council is ready to act, including by raising rates, if secondary inflation effects appear or if the November NBP projection shows a strong inflation scenario. Secondary effects are price rises that spread from an initial shock, such as fuel, into wages and the wider basket.
War-driven energy costs also reach core prices indirectly through airfares, logistics and imported goods, which can make energy-led pass-through look like demand pressure in the data.
Then came the caveat. He said he does not expect either condition to be met before November.
Glapiński on a November hike (as reported) “Yes, although I do not expect it.” And: “This is not what it looks like at the moment, but I do not prejudge.”
The headline number was loud, but its make-up was narrow. Glapiński attributed the overshoot to energy and fuel shocks linked to the Middle East conflict, and the GUS flash data supports that reading.
| September 2026 CPI component | Change y/y |
|---|---|
| Fuels for personal transport | +36.1% |
| Energy (electricity, gas, other fuels) | +4.9% |
| Food and non-alcoholic beverages | -0.5% |
| Headline CPI | 4.0% (from 3.4% in August) |
That was the fastest pace since June 2025. Core inflation, which strips out volatile food and energy, tells a quieter story: PKO BP estimates 3.0-3.2%, and Bank Pekao puts it near 3.2%, while some calendar listings show 3.3%. For you, the signal was never the 4.0% headline. It was a governor naming conditions and then saying they are not currently met.
What changed from September’s guidance
In mid-September, Glapiński said rates could stay unchanged until end-2026 and possibly until mid-2027. On 8 October he did not repeat that line, swapping a time-bound promise for conditional wording.
Commerzbank’s Tatha Ghose read this as a cautious shift, noting that markets had expected a firmer signal on hikes. The bank’s 9 October note called the stance conditional, not a sign of an imminent November move. Deutsche Bank had already flagged the tension between above-target inflation and long unchanged-rate guidance; dropping the date eases that tension without committing to action.
How forward guidance moves a currency: the zloty and the forint
The zloty stayed under pressure through 8-9 October, losing ground against peers including the forint. That sounds odd for a central bank that neither cut nor eased.
The explanation lies in pricing. Markets trade the expected path of rates, so a currency moves on the gap between what was priced and what is delivered, not on the level of rates itself. Forward guidance, meaning a central bank’s public signals about future policy, is the tool that either confirms or deflates those bets.
Episodes such as the 2013 taper tantrum show that central bank forward guidance tends to damage credibility when the gap between prior signals and later action widens, not when policy itself changes.
The sequence this week ran like this:
- Markets moved toward pricing a November hike after September’s 4.0% CPI print.
- Glapiński offered conditions rather than commitment, and said they were not expected to be met.
- Implied hike probabilities moved lower as traders repriced.
- The zloty weakened as the rate support it had been given was partly withdrawn.
Commerzbank ties the zloty’s weakness against the forint to exactly this: a hike had been priced that the conditional signals did not confirm. The bank also points to a divergence in how guidance was read relative to the Magyar Nemzeti Bank, Hungary’s central bank.
There are limits to the picture. No EUR/PLN or PLN/HUF levels and no swap-implied hike probabilities were available for the period, and no analyst commentary addressed structural drivers such as the fiscal deficit, ratings or positioning.
The lesson travels beyond Warsaw. A currency’s reaction depends on what the market had already bought, which means a central bank that sounds hawkish can still be bearish for its own currency.
How to read the next signals: language to watch and the November projection
Glapiński gave no numeric triggers, so the wording itself becomes the data. These are the cues to track:
- “Secondary” or “second-round effects”: evidence that fuel costs are feeding into wages and core prices strengthens the hike case.
- “Strong inflation scenario”: if the November projection carries this framing, the main stated trigger is live.
- References to the November projection: heavier emphasis signals the council sees it as the deciding document.
- Return of time-bound guidance: a revived “unchanged until” line would point back toward a long hold.
The risk readings cut both ways. If fuel and energy shocks fade while core stays contained, the hike case weakens; rising core or wage pressure strengthens it. Persistence of the Middle East conflict, a fuel subsidy referenced through end-2026 with possible extension, and wage-price dynamics all sit on the upside.
PKO BP’s view The bank sees inflation outside the band for several months, possibly returning inside from March 2027, and argues the overshoot is largely an external shock that calls for measured rather than aggressive hikes.
| Date | Event | What it tests |
|---|---|---|
| 15 October 2026 | Official core inflation | Settles the 3.0-3.2% versus 3.3% discrepancy |
| November 2026 | MPC meeting and NBP projection | Whether a strong inflation scenario appears |
ING flagged on 30 September that tightening could be discussed in November after the new projections, while Pekao’s softer core reading supports caution. No individual MPC member positions have been mapped publicly. For you, the core print and the November projection, not any single headline, will decide whether caution turns into action.
These views are speculative and subject to change as data and market conditions develop.
What this hold settles, and what November still has to answer
The NBP stayed on hold and kept a hike on the table only under conditions its governor does not expect to see soon. The zloty paid for a market that had priced more than Glapiński was willing to offer.
Two variables now carry the story: the trend in core inflation, starting with the 15 October release, and the tone of the November projection. If you hold or track Polish assets, those two readings, rather than the fuel-driven headline, are the evidence to weigh before deciding whether the hike case is gaining ground.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.