Credit Corp Group posted a record net profit after tax of $105.5 million for FY26, and then watched its shares fall roughly 7% on the day the result landed. Weeks later, it signed a binding agreement to acquire HSBC’s Australian credit card run-off book for around $150 million, and a newly appointed independent director stepped into the market to buy stock at $13.63.
That sequence contains its own question. If the fundamentals are strong enough to earn a record profit, a director’s cheque and a bolt-on acquisition, what exactly is the market pricing when it values the business at roughly 8x earnings?
The answer matters right now because the terrain has shifted underneath the stock. The HSBC deal was announced on 21 August 2026, updated group PDL guidance sits at $200-280 million, and the shares are trading in the $14.10-$14.25 range as of late September 2026. Investors face a familiar tension: a compressed multiple that reads either as a genuine bargain or as a discount the market has good reason to keep in place.
What follows breaks down whether that discount is earned or unwarranted, and which specific signals to watch before making a call.
Three catalysts in six weeks: what the market has been digesting
The story investors are trying to price did not arrive in one piece. It came in three, across roughly six weeks, and the order matters.
On 4 August 2026, Credit Corp reported FY26 results. NPAT of $105.5 million landed at the top of the $100-110 million guidance range and slightly ahead of the $104.3 million consensus estimate. Revenue of $586 million came in about 1% short of the $590 million analysts expected. On paper, a record. The shares still fell around 7%, closing at $12.78.
The US debt buying segment was the standout within that record result, with NPAT surging 57% on a constant currency basis as collections rose 24%, context that the FY26 results coverage documents in full alongside the segment-by-segment breakdown that underpins the group’s FY27 growth assumptions.
Here is the part that clean analysis depends on getting right. The selloff was not an earnings reaction. The earnings miss was negligible, roughly 1% on revenue and a small beat on profit.
| Date | Event | Key figure | Share price |
|---|---|---|---|
| 4 August 2026 | FY26 result and selloff | NPAT $105.5M; PDL guidance $200-280M | $12.78 (down ~7%) |
| 21 August 2026 | HSBC acquisition announced | ~$150M consideration | N/A |
| 21 September 2026 | Director on-market purchase | ~$121,085 total | $13.63 |
What triggered the fall was forward guidance. Initial FY27 PDL acquisition guidance of $200-280 million carried a midpoint roughly 22% below the $309 million consensus. The market did not doubt the past year. It doubted the pipeline.
Then, on 21 August 2026, the HSBC announcement arrived and reset that same PDL guidance upward, taking group investment to $300-380 million. The specific concern that drove the August selloff, that Credit Corp could not deploy capital fast enough, had been partly answered by the deal that followed it.
That repositions the current price as a different valuation question than the one investors were asking on 4 August. If you are still treating the August drop as a fundamental warning, you may be pricing a risk the company has already moved to address.
What the director purchase does and does not signal
The third catalyst came on 21 September 2026, when independent non-executive director Lyn McGrath bought shares on-market at $13.63, a total of roughly $121,085.
The price is the point. McGrath paid about 7% above the post-results close of $12.78. This was a valuation call made after both the results and the deal were public knowledge, not before.
Australian brokers treat director buys as supportive but secondary evidence, weighting consistency and meaningful size over a single transaction. What gives this one added context is that it established McGrath’s first substantial shareholding, making it both a governance alignment signal and a considered entry at a recovering price.
When big ASX news breaks, our subscribers know first
What the HSBC credit card run-off deal actually adds to the investment case
The HSBC transaction is easy to file under “growth” and move on. Doing so misses what Credit Corp is actually buying, and why it behaves differently from a standard debt purchase.
This is a credit card run-off book. HSBC is deactivating the cards and winding the portfolio down rather than selling charged-off debt in the traditional sense. That distinction changes the receivable profile: shorter in duration and more sensitive to how well the collections strategy is executed than a typical purchased debt ledger, which is an acquired portfolio of already charged-off consumer receivables.
The scale is significant for the domestic business. The roughly $150 million consideration lifted AU/NZ PDL acquisition guidance from $100-150 million to $200-250 million, making the HSBC book the dominant driver of Australian segment growth in FY27.
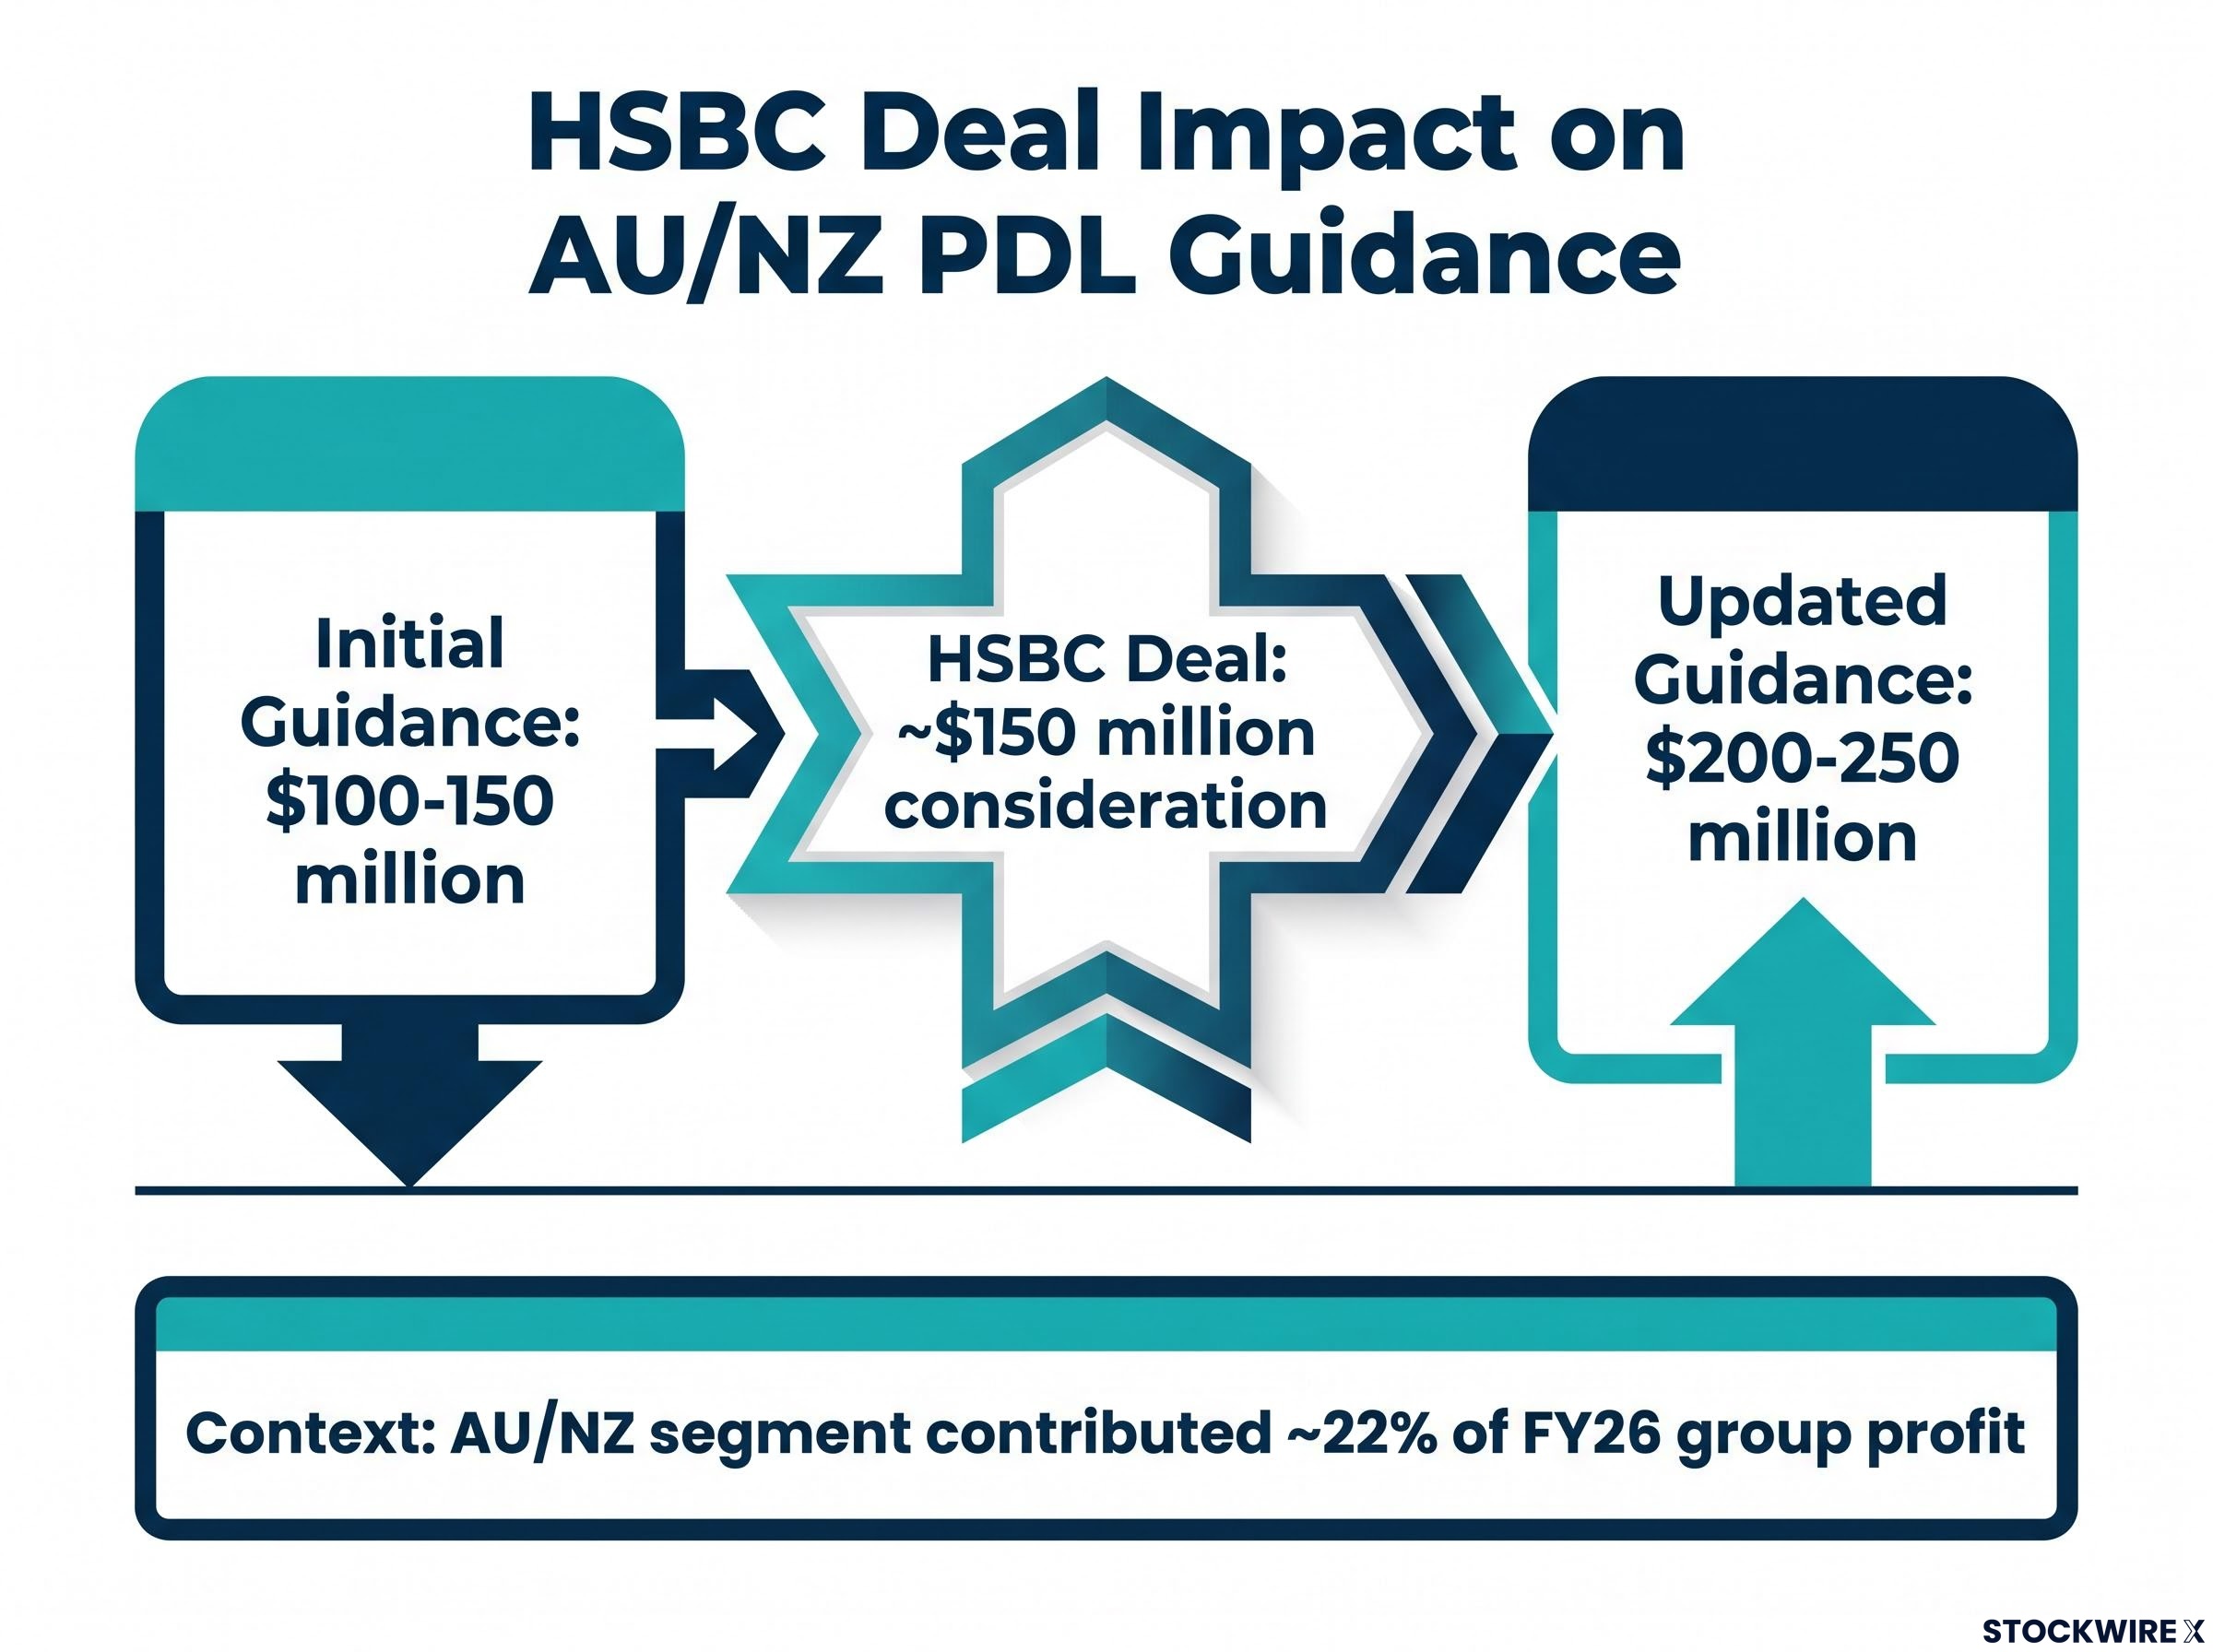
That segment matters more than its size suggests. The AU/NZ purchased debt ledger business contributed approximately 22% of FY26 group profit, and Macquarie identified it as the direct beneficiary of the deal. Macquarie lifted its target price to $14.37 from $13.34 following the announcement.
There is a broader pattern here too. Global banks have increasingly been exiting or streamlining specific Australian consumer credit lines, and the HSBC book fits that shift, potentially signalling more episodic opportunities for specialist acquirers ahead.
The deal is not without its own conditions and risks specific to this transaction:
The HSBC acquisition announcement confirmed the deal follows the collapse of Credit Corp’s earlier Humm Group bid, with the freed balance sheet redeployed directly into this transaction, a sequencing that shaped both the pricing rationale and the revised PDL guidance range.
- Regulatory approval is required before completion.
- Settlement depends on HSBC first deactivating the cards on issue.
- The shorter receivable duration raises the importance of collection execution.
- Integrating a sizeable finite portfolio adds concentration and operational complexity while Credit Corp also manages US and UK growth.
Completion is expected early in calendar 2027, contingent on those approvals and the deactivation process.
Macquarie’s read Outperform rating, target raised to $14.37 from $13.34, with the valuation characterised as attractive at roughly 8x price-to-earnings while acknowledging limited visibility on FY27 PDL volumes.
The takeaway for investors is that the $150 million is not simply a volume uplift. It is a commitment to a higher-execution-risk profile, and the updated guidance range is only as achievable as Credit Corp’s collections performance on a shorter-duration book. Price the upside, but price the integration bar with it.
Why Australian PDL businesses trade at compressed multiples, and what would change that
Before deciding whether 8x is a bargain or a fair price, it helps to understand why the market rarely awards debt buyers anything richer. The discount is not an accident. It is structural, and it comes from four distinct pressures.
- Earnings cyclicality. Debt buyers depend on the volume, pricing and mix of charged-off debt that banks sell, which swings with macro conditions and lending standards. Supply is lumpy, and Credit Corp’s initial FY27 guidance landing 22% below consensus is that lumpiness in real time.
- Regulatory and conduct-risk overhang. These businesses operate at the sharp end of consumer credit under oversight from ASIC (conduct and licensing), AFCA (dispute resolution) and at times the ACCC. The persistent chance of enforcement or remediation keeps a discount on the sector.
- Accounting profile. PDL portfolios are carried at amortised cost using expected-collection models, with high yields early that normalise as portfolios age. That raises questions about earnings quality and the durability of high returns.
- Capital-intensity treadmill. Debt buyers must keep reinvesting in new ledgers to sustain earnings, an ongoing allocation challenge that raises the risk of overpaying when competition is fierce.
ASIC’s RG 96 debt collection guideline sets out the conduct standards that collectors must meet under Commonwealth consumer protection law, and any enforcement action or remediation finding under that framework is the direct source of the tail risk that keeps a discount on the sector.
Those pressures split investors into two camps.
| Dimension | Bull case at 8-9x | Bear case / structural discount |
|---|---|---|
| Earnings quality | High returns on invested capital and disciplined pricing | Model-driven, cyclical, sensitive to charge-off supply |
| Regulatory outlook | Track record of compliant collections; scale advantage | Persistent ASIC/AFCA tail risk and remediation exposure |
| Reinvestment risk | Diversification into US, UK and lending smooths earnings | Continual ledger purchasing risks overpayment |
The numbers give the bull camp something to work with. Updated NPAT guidance of $110-118 million implies roughly 4-12% growth at the midpoint over FY26. Broker coverage runs 6 Buy, 1 Hold, 0 Sell, with an average 12-month target of $17.09 and Morgans at $18.25. The stock had also rallied heading into the 4 August result, so some optimism was already banked before the pullback.
Here is where the reading sharpens. If you accept that the compressed multiple is partly structural rather than purely a reflection of current earnings risk, the re-rating question becomes specific: has Credit Corp done enough to demonstrate the cycle-through resilience and earnings diversification that would justify a higher multiple?
Historically, re-ratings have followed evidence of exactly that: resilience across cycles, disciplined portfolio pricing, regulatory clarity and geographic diversification. The HSBC deal and the US expansion are the primary data points that will either build that case or leave the discount in place. A 20-30% implied upside to consensus is not actionable until you decide which way that evidence is heading.
For investors wanting to stress-test the structural discount argument against an earlier episode, our deep-dive into Credit Corp’s mid-year valuation gap examines the 1H FY26 result in detail, including the second-half earnings step-up required to meet full-year guidance and the broker reasoning that sustained Buy ratings through the gap.
Where the risk-reward sits heading into FY27
The single most important number for the year ahead is not the profit line. It is the width of the guidance range.
FY27 PDL investment guidance sits at $200-280 million, split between US purchasing of $100-150 million and AU/NZ of $100-150 million (with the AU/NZ figure expected to increase materially following the HSBC acquisition). That is a wide band, and it is wide for concrete reasons: HSBC deal timing and its regulatory contingency, the inherent lumpiness of PDL supply, and the difficulty of predicting when banks choose to sell.
Width is uncertainty, and uncertainty is what a single acquisition cannot fully resolve. That leads to three signals worth monitoring closely:
Debt buyers benefit when banks accelerate charged-off debt sales, but the same macro environment that generates ledger supply also raises collection risk; credit stress signals including tightening bank lending standards and rising distress ratios in consumer credit are therefore a double-edged variable for Credit Corp’s FY27 purchasing volumes.
- HSBC regulatory approval and completion timing, expected early calendar 2027.
- US segment PDL purchasing volumes relative to the $100-150 million guidance.
- Any ASIC or AFCA developments affecting Credit Corp’s collections practices.
The caution case is straightforward. Even after the pullback, it trades above the $12.78 post-results close, in the $13.60-$14.37 range through September with recent levels around $14.10-$14.25. The wide guidance leaves real earnings variability that the HSBC book alone does not remove.
The bull anchor Morgans rates Credit Corp a Buy with a target of $18.25, implying more than 30% upside from levels around its August coverage price. That figure anchors the optimistic end of the broker range.
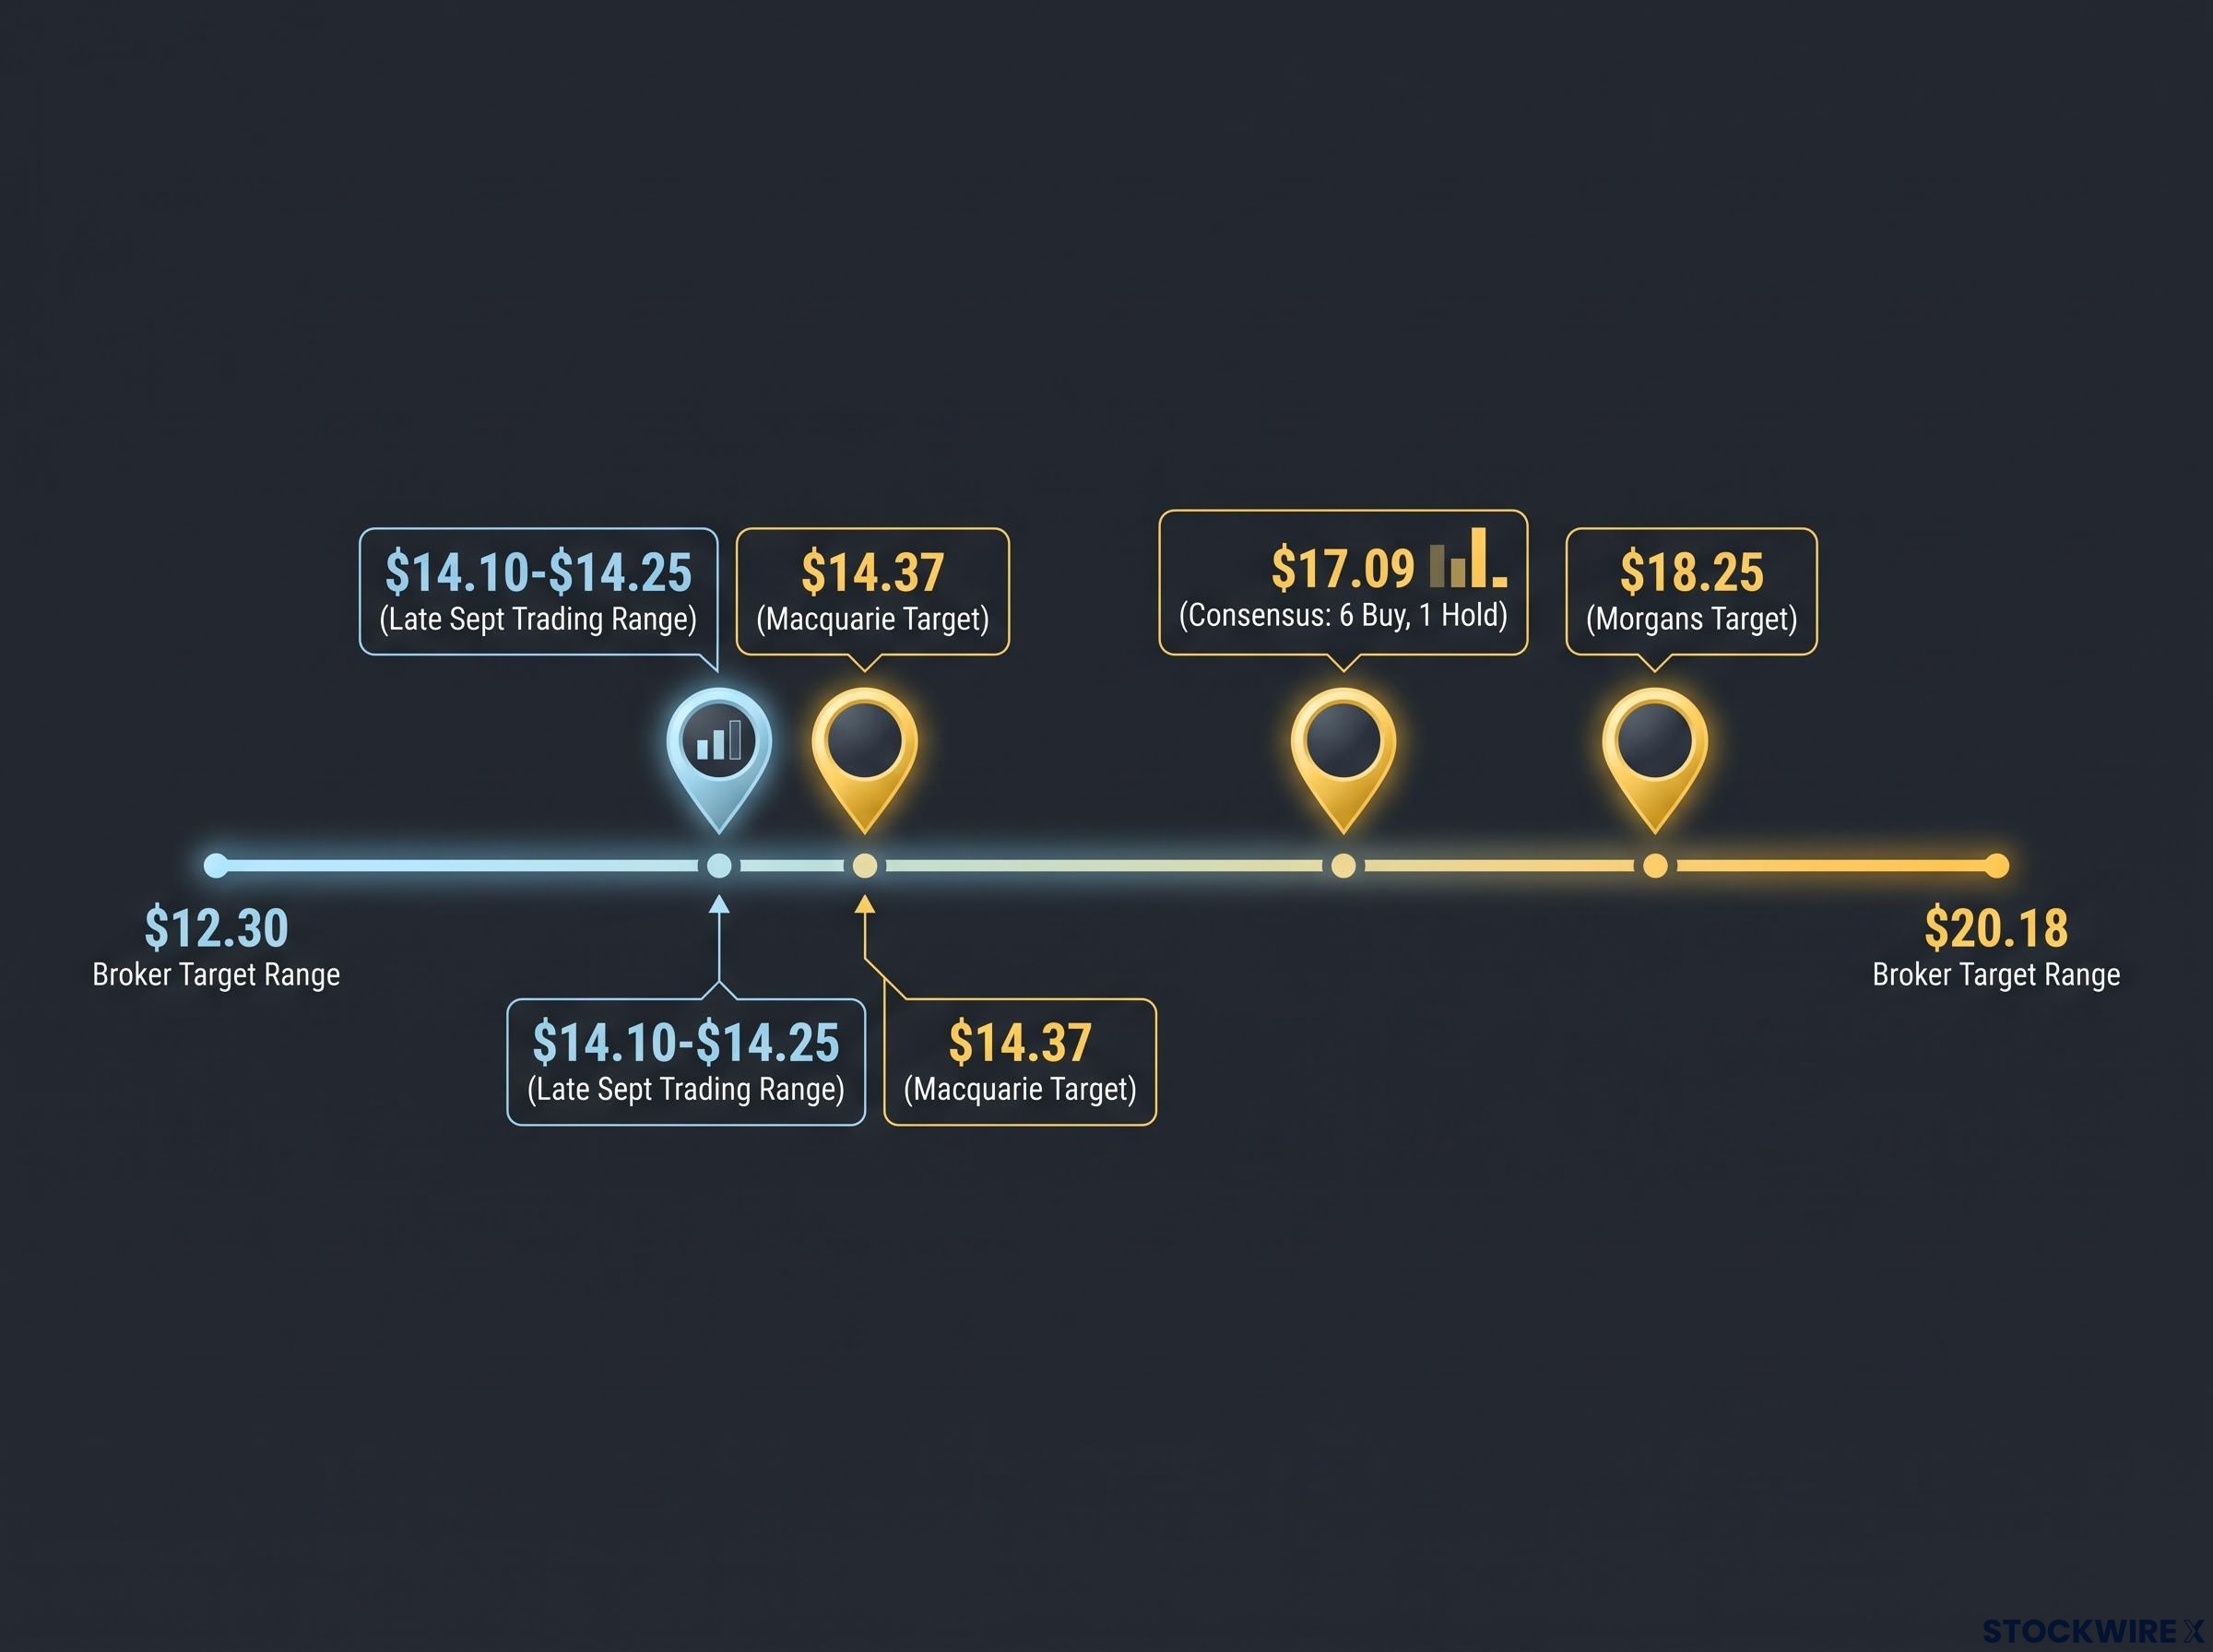
The gap between Macquarie’s $14.37 and Morgans’ $18.25 is itself the signal. At current prices, there is minimal upside to Macquarie’s conservative target but substantial room to both Morgans and the $17.09 consensus. Buying here means implicitly backing the more optimistic execution scenario, not the floor. The decision is not whether Credit Corp is a good business. It is whether the market’s FY27 uncertainty has been overpriced.
Making a call at 8x when the range is this wide
Strip the noise away and the core tension is clean. Part of the multiple compression is structural and will not lift without sustained evidence of cycle resilience and regulatory stability. Part of it is cyclical, tied to FY27 PDL volume uncertainty that the HSBC deal has only partly resolved.
Several signals point the same way. A record FY26 NPAT of $105.5 million. Broker consensus firmly in Buy territory at 6 Buy, 1 Hold, with an average target of $17.09 against a $12.30-$20.18 range. Updated FY27 guidance implying roughly 4-12% NPAT growth at a ~$114 million midpoint. And a director’s first substantial purchase struck above the post-results close.
Against that sits a genuinely wide range of outcomes and the moving parts of an acquisition that will not complete until early 2027.
For an investor at $14.10-$14.25, the question is not whether those moving parts are manageable. It is whether the current price already compensates for them. That is the distinction between the structural discount arguments that deserve respect and the cyclical uncertainty that may already be in the price.
Four conditions would support a re-rating from here:
- Demonstrated cycle-through resilience across a full purchasing cycle.
- Evidence of disciplined pricing that avoids overpaying for ledgers.
- Clean execution and timely completion of the HSBC book.
- Regulatory clarity from ASIC and AFCA that reduces tail risk.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results, and financial projections are subject to market conditions and various risk factors.