A month ago, the market gave the Federal Reserve roughly a 1-in-10 chance of hiking again at its October meeting. As of late September 2026, that figure sits near 2-in-3. A repricing that steep, inside a single calendar month, does not happen quietly.
The shift is the product of a coordinated hawkish message from a run of Fed officials through August and September 2026, capped by a unanimous 25 basis point hike on 16 September. The federal funds target range now stands at 3.75%-4.00%, PCE inflation is running at 3.7%, and unemployment has held at 4.1%. That combination gives policymakers cover to keep pressing, and currency markets are pricing accordingly.
The size of the move in Fed rate hike odds has direct consequences for the US Dollar, but the harder question is whether the Dollar’s current strength is durable or a late-cycle surge that peaks before the cuts arrive. This piece offers a framework for separating signal from noise in the current cycle, so you can read the next Fed move for yourself rather than react to it after the fact.
From 9.4% to 65.9%: how fast the market repriced the Fed
Start with the number, because the number is the story. One month ago, the CME FedWatch tool put the implied probability of an October hike at 9.4%. One week ago it was 57.6%. It now sits at roughly 65.9%.
That is a 56-percentage-point swing in market conviction across four weeks. A move of that magnitude does not describe a slow drift in sentiment. It describes a market that was positioned one way, got caught wrong-footed, and is correcting at speed.
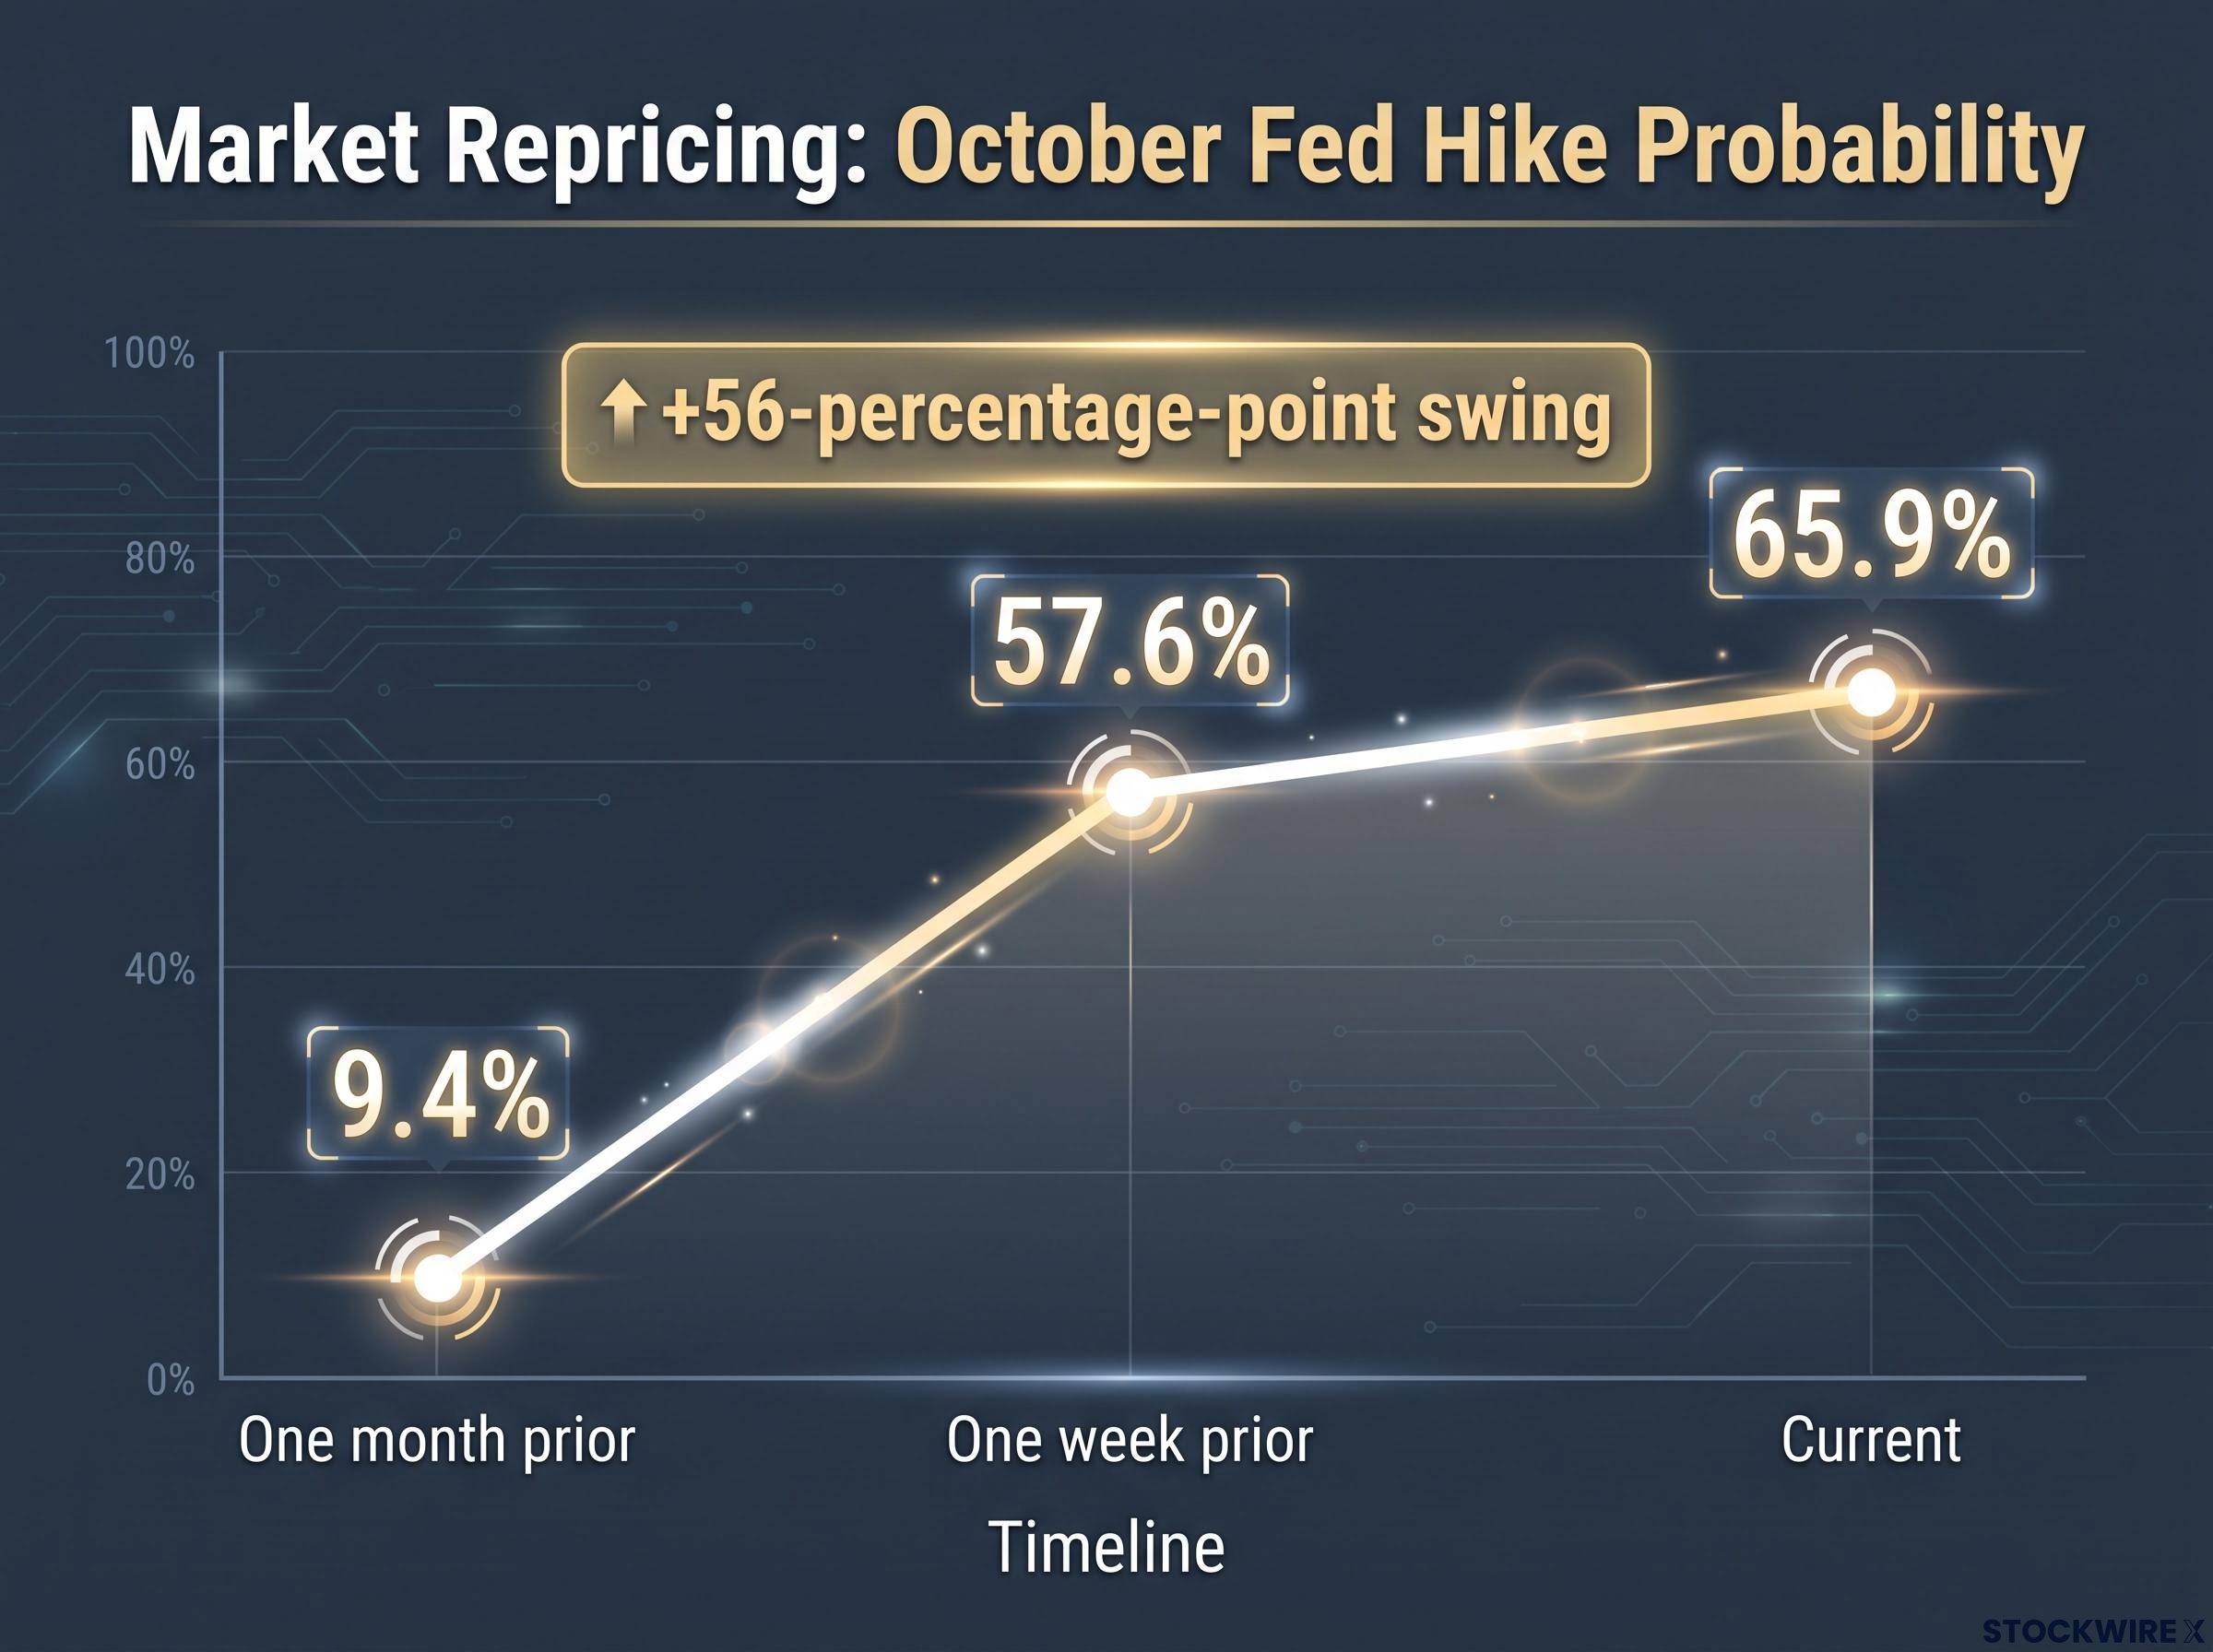
| Date reference | Implied hike probability | Change from prior |
|---|---|---|
| One month prior | 9.4% | Baseline |
| One week prior | 57.6% | +48.2 points |
| Current | 65.9% | +8.3 points |
The 16 September hike itself was not the surprise. The move to 3.75%-4.00%, effective 17 September, was widely expected and delivered unanimously. What repriced the market was the recalibration that followed: the growing conviction that another hike is coming in October, on top of the one just delivered.
The September FOMC statement confirmed the unanimous 25 basis point hike to 3.75%-4.00% and characterised inflation as still elevated, giving the committee’s own language to any analyst measuring how far the hawks have shifted the burden of proof on further action.
For you, the velocity matters more than the level. It tells you the current Dollar rate is highly sensitive to a narrow set of official communications, which means it can reverse just as fast if the next inflation print disappoints the hawks.
The officials whose words moved markets
The proximate catalysts for the final leg were two voices. Cleveland Fed President Beth Hammack warned that policy must stay restrictive if progress on inflation stalls, the clearest statement yet of where the hawks draw their floor. Philadelphia Fed President Anna Paulson indicated that some additional moderate tightening may be appropriate.
“Policy must remain in restrictive territory if inflation progress stalls.” That framing, attributed to Hammack, is the hawks’ bottom line: the bar for stopping is progress, and progress has not yet arrived.
Those remarks landed on already-hawkish ground. At Jackson Hole on 28 August 2026, Chair Kevin Warsh flagged 12-month PCE at 3.7% and the six-month change at 4.1%, concluding the Fed’s focus should sit squarely on prices. Dallas Fed President Lorie Logan had gone further still, stating she believes modestly higher rates would better balance the outlook. Hammack’s own FXS Speechtracker score came in at 7.2 out of 10, just below the historical average of 7.5 but firmly in hawkish territory. The market was not reacting to one speech. It was reacting to a chorus.
FOMC voting structure matters when reading the hawk-dove balance: only 12 members vote at each meeting, and comments from non-voting regional presidents carry context weight rather than binding policy force, a distinction that becomes critical when markets are trying to read whether Hammack or Paulson will actually move the outcome.
When big ASX news breaks, our subscribers know first
Why rate expectations move the Dollar: the transmission mechanism explained
Before you can judge whether the Dollar’s strength should hold, you need to see why it moves in the first place. The link between rate expectations and the currency is a sequence, not a mystery, and it runs through three connected channels.
- Yield differential: Higher expected US rates lift US short and medium-term yields relative to peers. That draws foreign capital into US bonds, money-market instruments, and Dollar-denominated credit, and buyers must convert into Dollars to get there, lifting demand for the currency.
- Carry trade dynamics: Investors borrow in lower-yielding currencies and deploy into higher-yielding US instruments, pocketing the gap. This reinforces the same directional flow, provided volatility stays contained.
- Real-rate credibility premium: A Fed seen as genuinely committed to price stability strengthens confidence in the future real value of Dollar assets, adding a trust premium on top of the mechanical yield advantage.
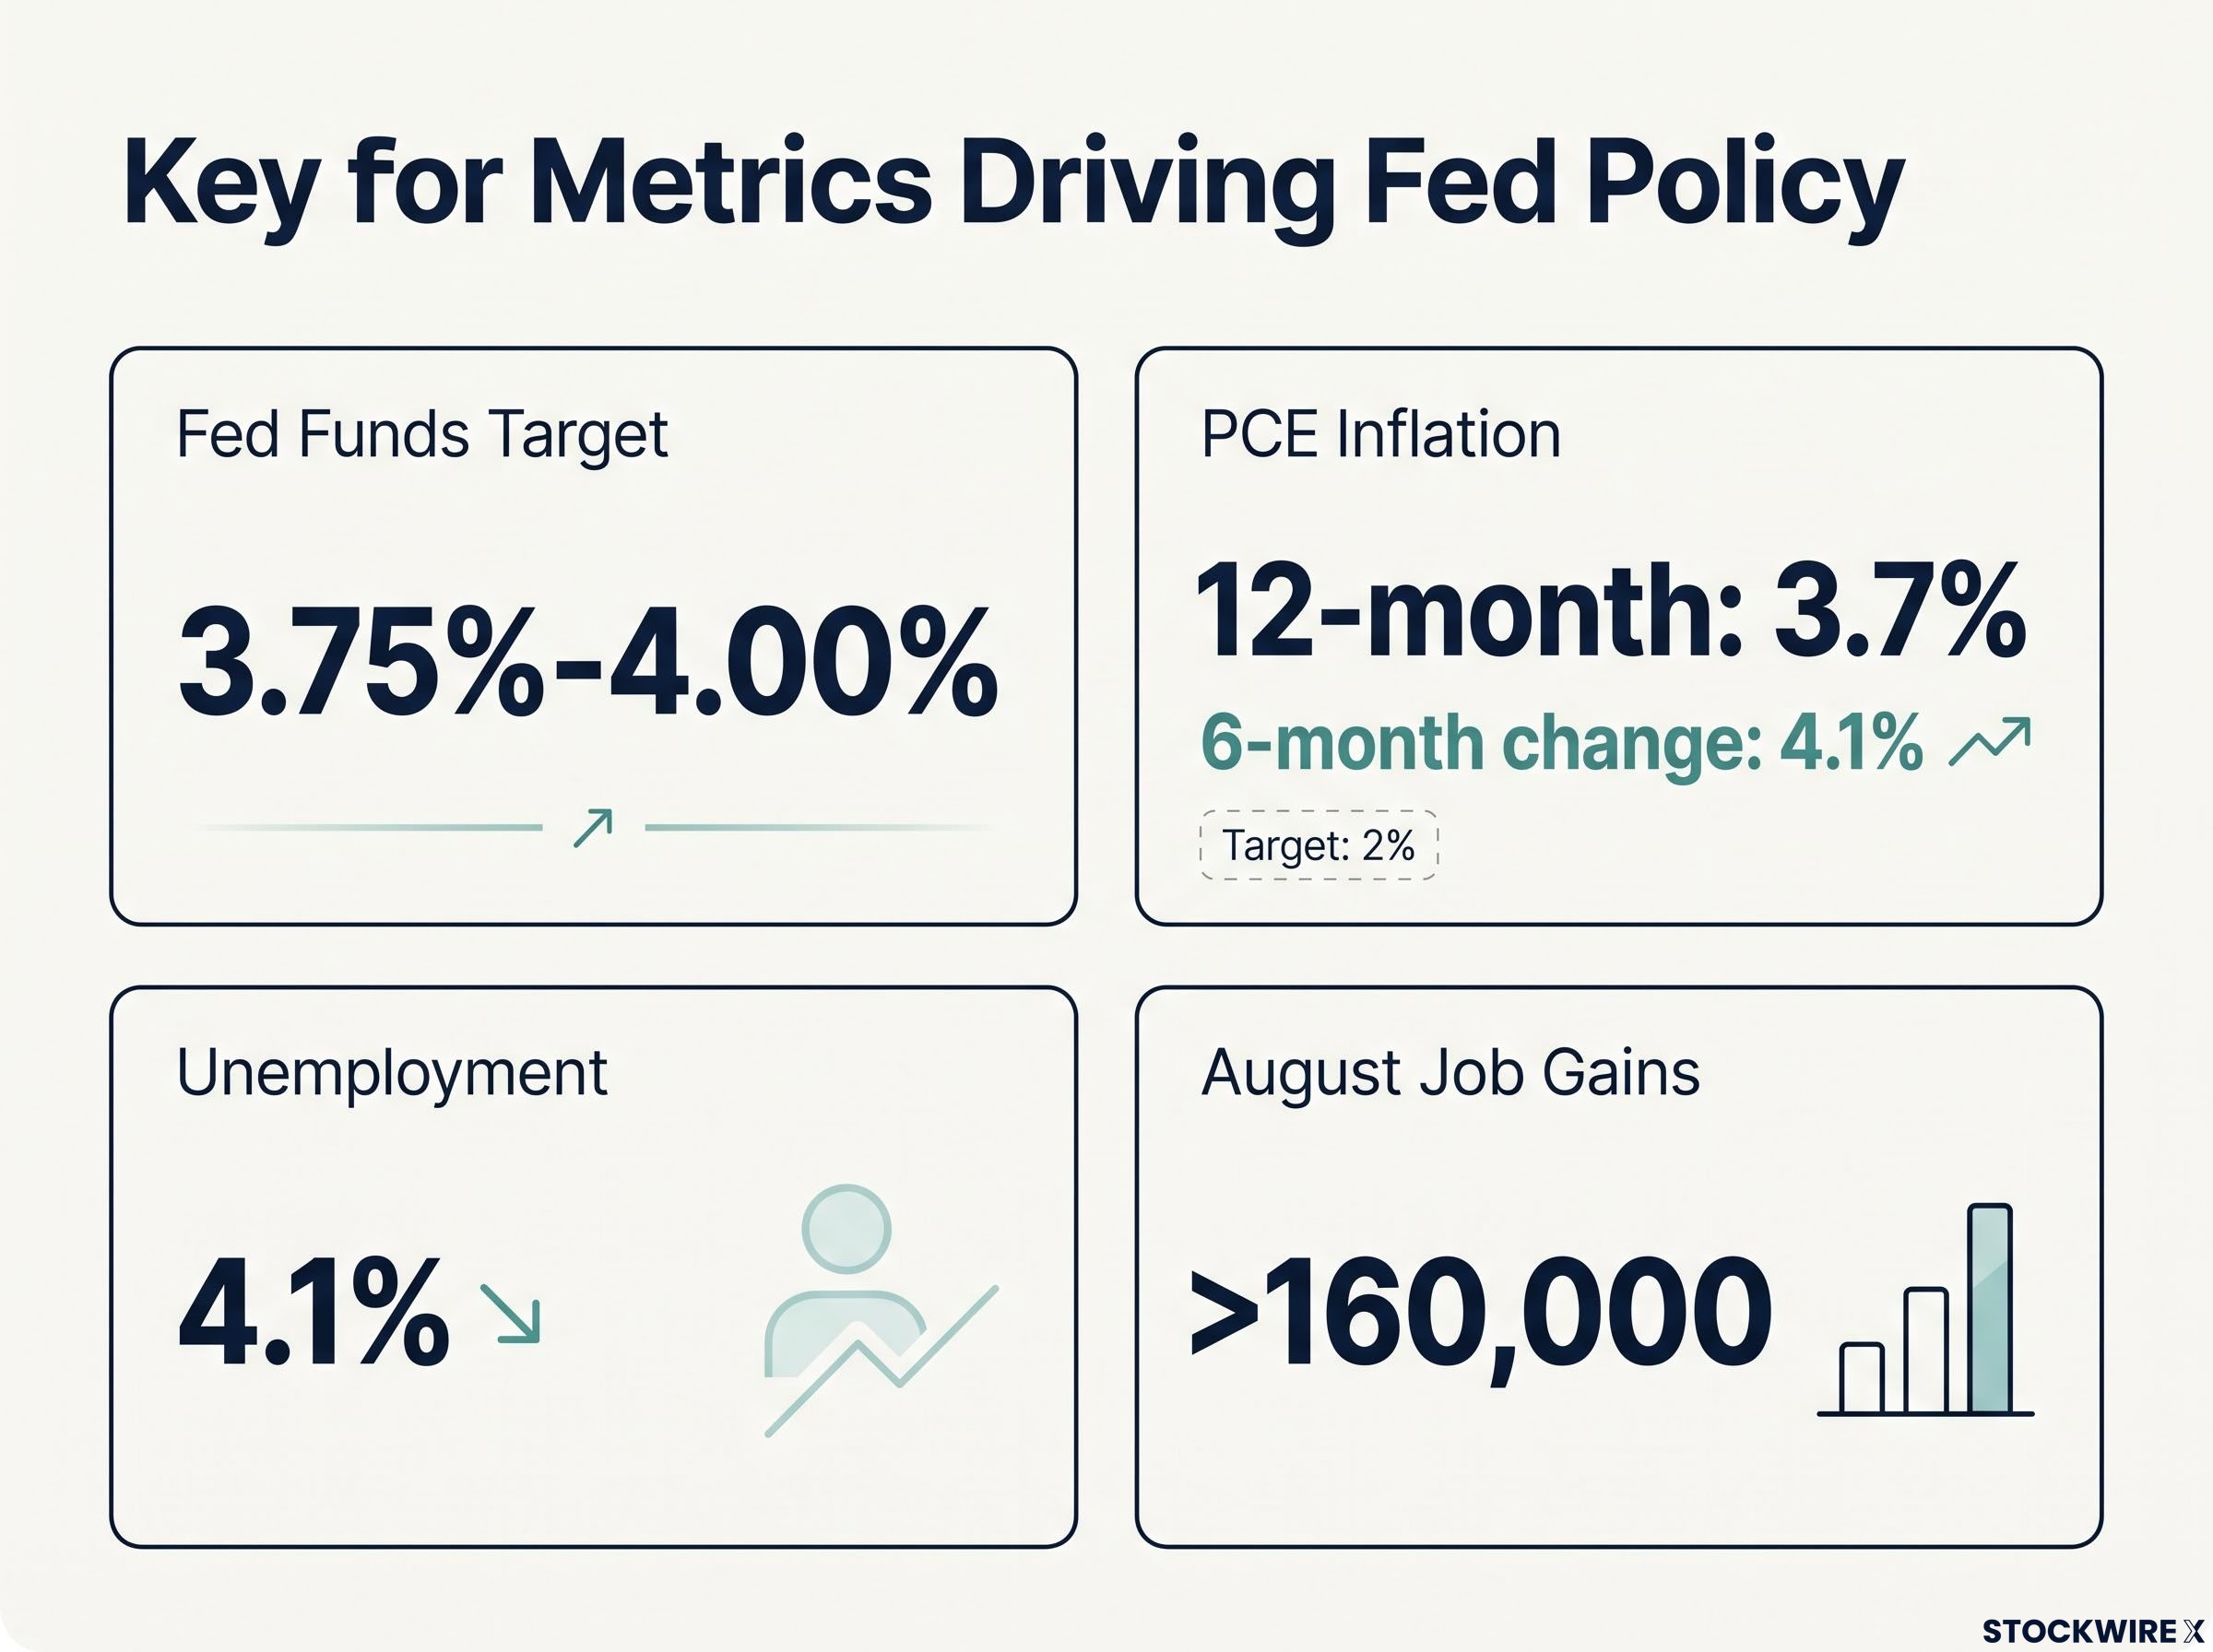
The inflation backdrop is what gives that credibility channel teeth. Warsh cited 12-month PCE at 3.7% and a six-month change at 4.1% at Jackson Hole, numbers that justify the Fed’s stated priority on prices. Personal consumption expenditures, or PCE, is the inflation gauge the Fed watches most closely.
The BEA Personal Income and Outlays release for July 2026 placed the 12-month PCE price index at 3.7%, the same figure Warsh cited at Jackson Hole, confirming that the inflation backdrop driving the hawkish consensus reflects official government data rather than model estimates.
The labour market is the other half of the case. Richmond Fed President Tom Barkin noted on 22 September 2026 that unemployment held at 4.1% in August with job gains rebounding above 160,000. A labour market that is not breaking under restrictive policy gives the Fed room to keep it there.
Governor Lisa Cook put the duration of the problem plainly.
“Inflation has been stubbornly high, exceeding the 2% target for more than five years,” Cook said, characterising an economy that is resilient and growing at a solid pace.
Here is what the mechanism means for you in practice. The Dollar is not responding to a number on the FedWatch screen. It is responding to a broader signal that the US yield advantage over peers is likely to persist. That reframes the probability figure entirely: it stops being a scoreboard and becomes a forward-looking indicator. Any data that challenges the persistence of that yield advantage will move the currency immediately, and knowing this lets you anticipate which releases matter most rather than waiting to react.
Three readings of the same signal: how analysts disagree on what comes next for the Dollar
Here is where honest analysis gets uncomfortable. The same set of facts, a restrictive Fed, elevated inflation, a resilient labour market, supports three genuinely competing conclusions about the Dollar. Each has a strong form, and none can be dismissed.
The structural bull case argues that as long as the Fed holds its rate well above neutral and keeps the door open to hikes, the Dollar stays supported by high carry and policy credibility. Logan’s on-record view is the anchor here: she “currently believe[s] modestly higher interest rates would better balance the outlook and risks,” the strongest hawkish signal from a voting participant. Restrictive policy also tends to coincide with relative US growth resilience, pulling global capital into US equities and credit and supporting the Dollar indirectly.
The late-cycle peak case runs the other way. Once markets are convinced the Fed is at or near its peak rate, the Dollar can roll over well before the first cut lands. The 2014-2018 cycle is the precedent: the Dollar strengthened ahead of and during the early hikes, then flattened once the path was fully priced. The lesson from that cycle is that anticipation of tightening often matters more than its continuation.
| View | Core argument | Key risk to that view |
|---|---|---|
| Structural bull | High carry and policy credibility keep global capital flowing into USD assets | Dollar strength fades once the peak rate is fully priced |
| Late-cycle peak | Dollar rolls over before the first cut, as in the 2014-2018 cycle | A hawkish data run extends the cycle longer than expected |
| Data-dependent range | Each inflation or jobs print resets pricing; no sustained trend | A decisive data break forces a clean directional move |
Why the data-dependent view is more than a hedge
The third view holds that the Dollar trades in a broad range, with each release resetting the probability rather than driving a trend. It is tempting to read this as diplomatic fence-sitting, but the language of the officials themselves suggests otherwise.
Governor Christopher Waller said on 3 September 2026 that a fleeting improvement in disinflation would make it appropriate to raise the policy rate at September, explicitly conditioning further action on the incoming data. That is not neutrality. It is a description of how the committee will actually behave.
Warsh’s communication overhaul compounds the data-sensitivity problem: with forward guidance formally scrapped and the dot-plot’s future role under internal review, each incoming print lands on a market that has no Fed-provided buffer to anchor its reaction.
The 2004-2006 cycle offers a further caution: a predictable, well-telegraphed hiking path can have a modest FX impact when other macro conditions offset the mechanical support. Put together, the conditional framing makes the Dollar uniquely reactive to scheduled data. That suits some participants and creates real timing risk for others.
The takeaway for you is not which view wins. It is that anyone projecting a clean directional trend from here is suppressing genuine uncertainty. The honest position is to track the data, not anchor to a preferred story.
What the current setup gets wrong and what could break the Dollar’s momentum
The hawkish consensus is coherent, but it has specific soft spots, and the risks around it are not balanced. They tilt.
The first is overtightening. If the Fed leans too hard on lagging inflation data while underestimating the cumulative bite of past hikes, a growth shock could flip market expectations from further hikes to emergency cuts, unwinding Dollar strength rapidly. The second is global convergence: if the European Central Bank, the Bank of England, or the Bank of Japan tighten at the same time, relative differentials may not shift enough to keep the Dollar rising even if the Fed moves again.
- Overtightening and growth shock: Excess focus on lagging inflation could trigger a downturn that reverses hike bets into cut bets.
- Global central bank convergence: Simultaneous tightening abroad narrows the yield gap that supports the Dollar.
- Fed communication fragmentation: Officials hold genuinely different conditions for acting, so markets can overread any single speaker.
- Fiscal risk premium: Large US deficits mean part of the nominal yield advantage reflects fiscal risk, not real-rate support.
The communication risk is real and specific. Logan explicitly favours higher rates, Waller conditions further action on the data, and Governor Philip Jefferson flags the labour market’s exposure to shocks. A market that latches onto one voice can overshoot, then correct.
“The labour market is roughly in balance but susceptible to adverse shocks,” Jefferson said on 7 April 2026, the clearest official acknowledgment of a scenario where the hawkish consensus could break down.
There is an early warning worth watching too. The FXS Fed Sentiment Index sits at 147.72, comfortably above its 100 neutral mark, but it has slipped 0.34 points. Perceived hawkishness may be plateauing even as the headline probability stays high. Barkin’s emphasis on solid labour conditions on 22 September 2026 remains the bull case anchor the bears must disprove.
The asymmetry is the point. With a hike already 65.9% priced, the Dollar’s upside from a confirmed move is likely modest. A dovish data surprise, by contrast, would hit a market leaning heavily one way and could produce a sharper correction than the remaining upside is worth. The probability tells you where the market sits. The risks tell you what it is underweighting.
DXY technical levels add a second layer to the probability story: the support cluster between 99.69 and 99.80 is the line between trend continuation and failed breakout, meaning a dovish data surprise does not just move the FedWatch screen but hits a specific technical threshold that institutional flows watch.
What the 65.9% tells you now, and what to watch next
Pull it together and the picture is nuanced rather than one-sided. A 65.9% implied probability is high enough to move markets sharply if it reverses, yet not so high that further Dollar appreciation is off the table if incoming data validates the hawkish read.
That leaves the near-term direction resting less on the Fed’s intention, which is clearly hawkish, and more on whether the data gives the hawks permission to follow through. The rate is already known. The evidence that would justify the next move is not.
So the useful output is a watch list, not a forecast. These are the specific signals that will confirm or crack the current consensus before the October FOMC decision.
- The next CPI release, for whether disinflation is durable or fleeting, the exact condition Waller set.
- The next PCE release, the Fed’s preferred gauge, currently at 3.7% and still well above the 2% target.
- Formal remarks from Logan, Hammack, or Paulson, the clearest hawkish voices and the ones most likely to move pricing.
- The FXS Fed Sentiment Index trajectory, now at 147.72 and slipping, as a leading tell on whether official hawkishness is peaking.
PCE disinflation gauges matter beyond the headline reading: the Dallas Fed trimmed mean and Cleveland Fed median were both trending near 2% as of June, approaching target faster than core PCE and serving as the breadth-of-disinflation test the Fed applies before any pivot becomes credible.
The practical read is this: watch scheduled data and named speakers over the policy rate itself, because the rate is settled and the data that justifies the next move is not. Leave with the watch list rather than the number, and you can update your view as information arrives instead of anchoring to today’s 65.9% as if it were fixed.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results, and these statements about future Fed policy and currency direction are speculative and subject to change based on incoming data and market developments.