

Board rejects second Warburg Pincus offer, standing firm on value
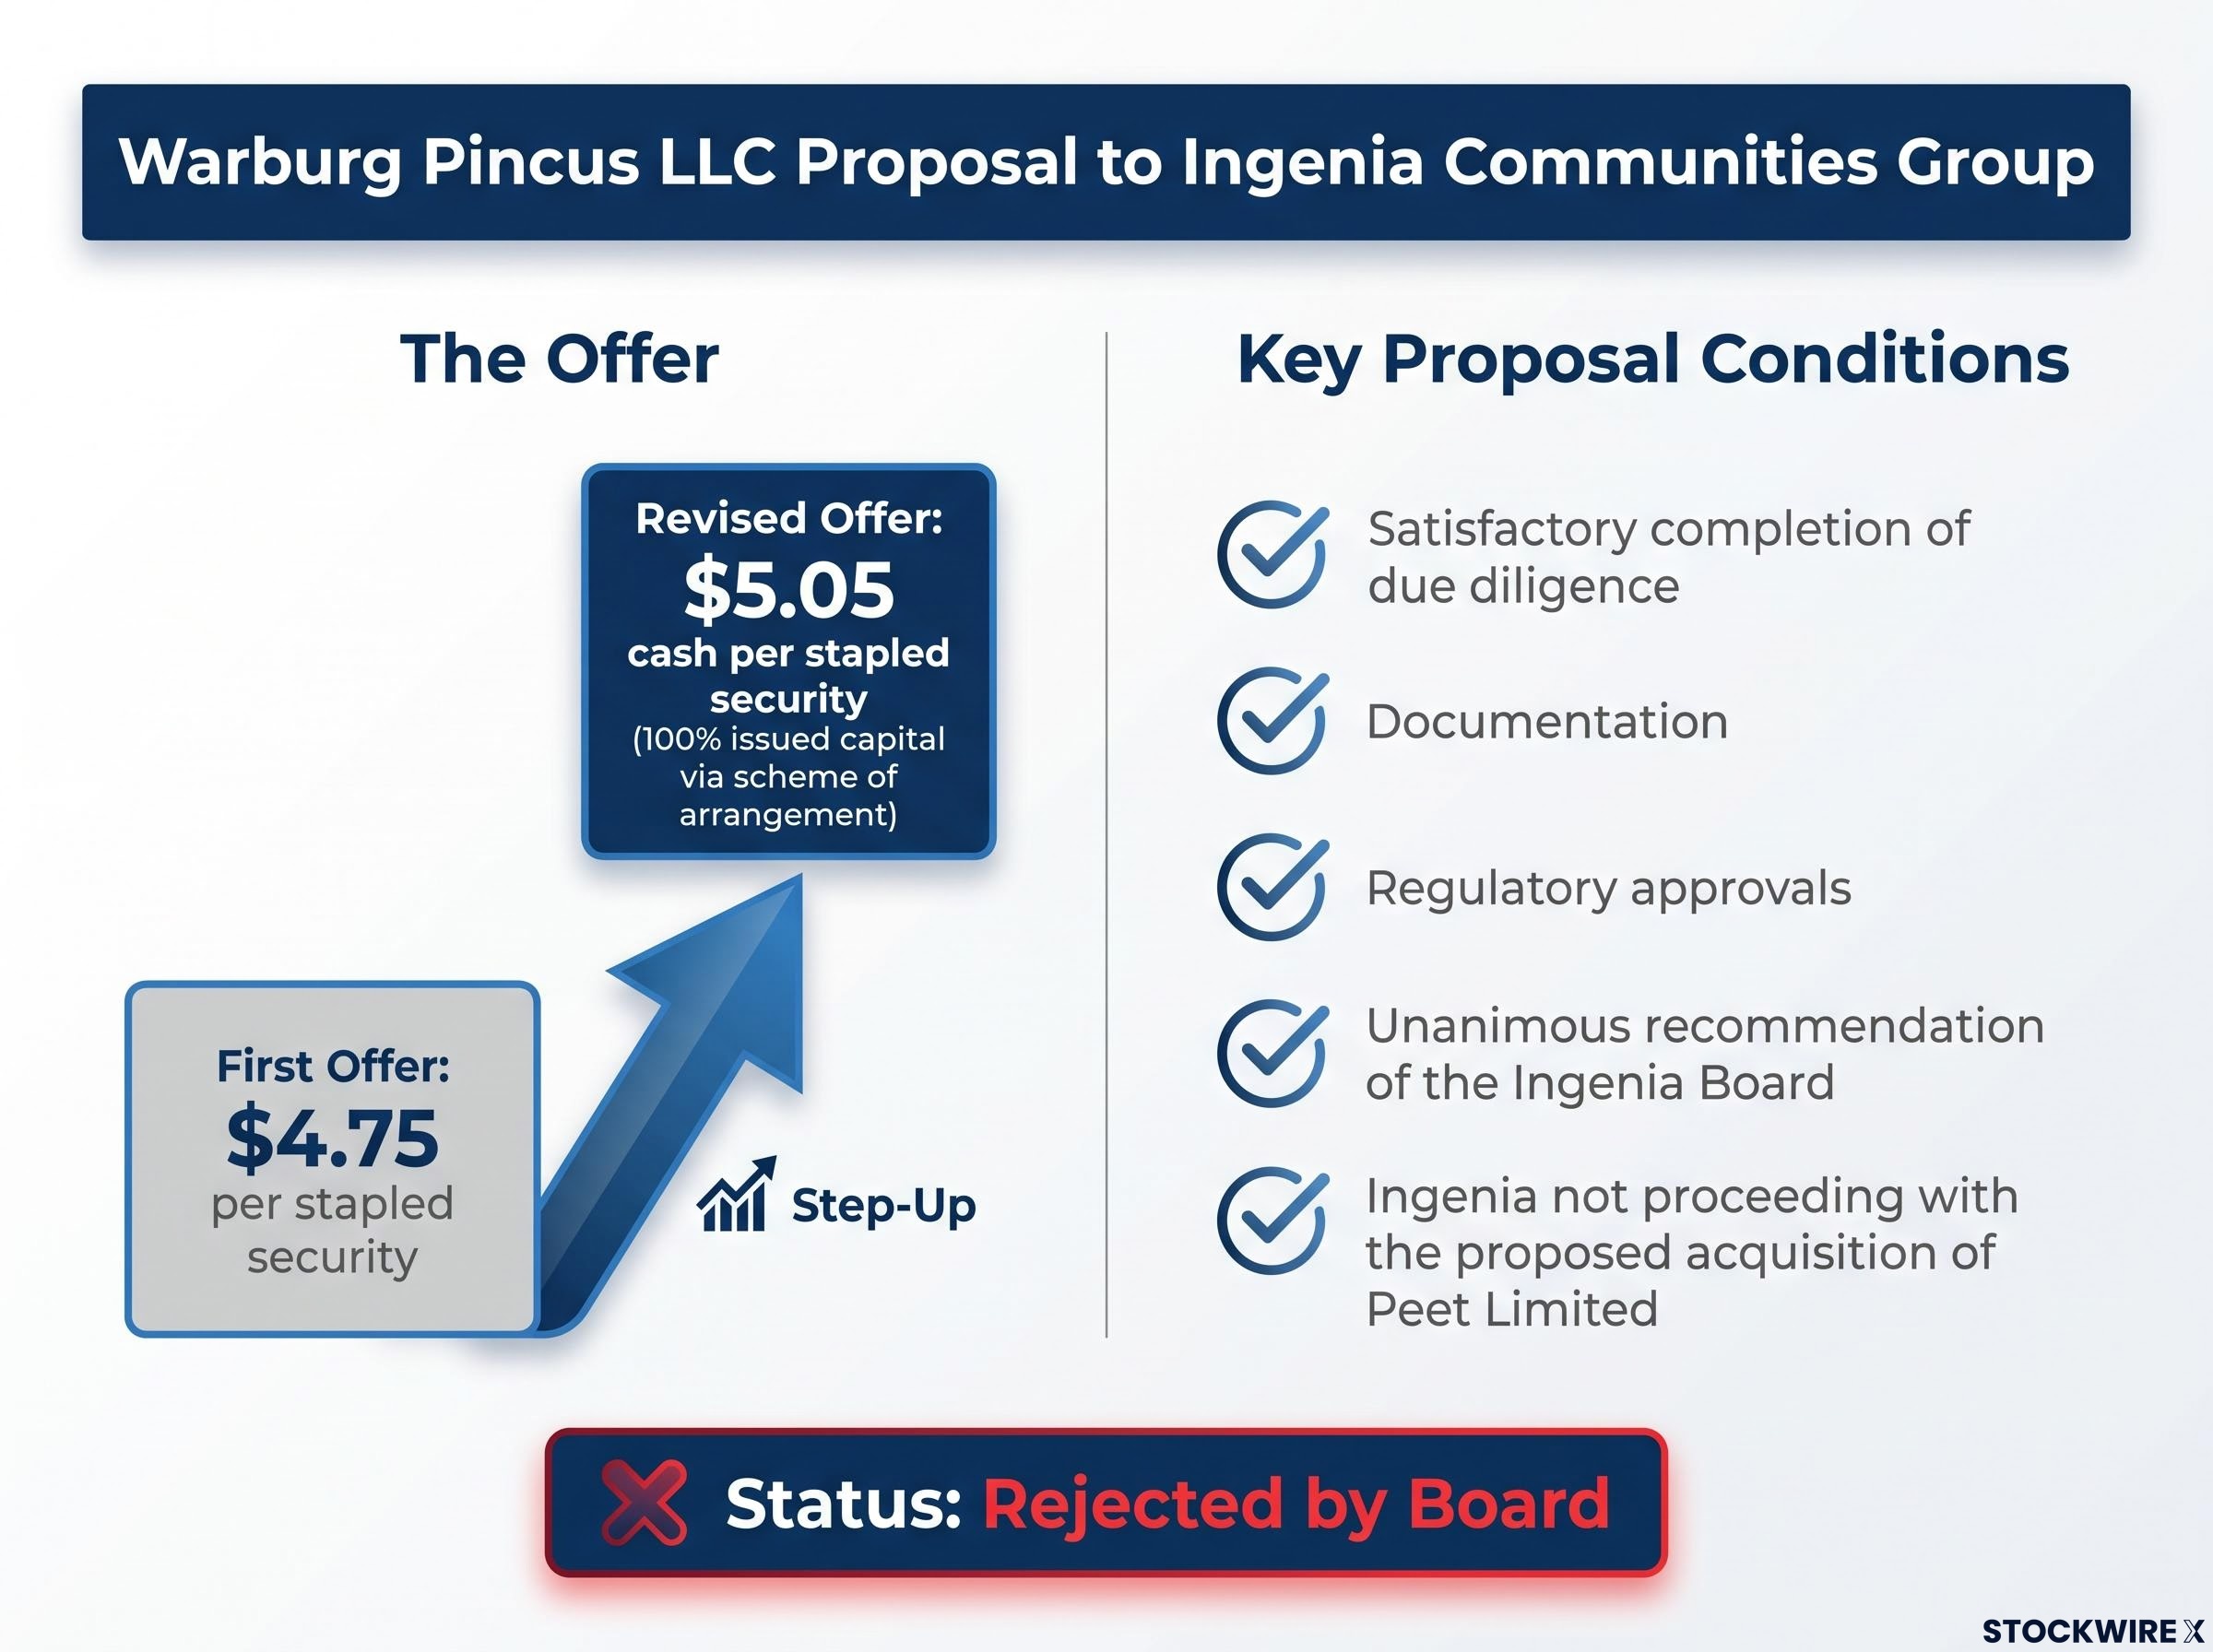
Ingenia Communities Group (ASX: INA) has rejected a revised non-binding indicative proposal from Warburg Pincus LLC and/or its affiliates to acquire 100% of its issued capital via a scheme of arrangement at $5.05 cash per stapled security, less any future distributions paid by Ingenia prior to implementation.
This is the second offer the Board has turned away. The first, also from Warburg Pincus, was priced at $4.75 per stapled security, making the revised bid a meaningful step up — yet still not enough to satisfy the Board.
After thorough consideration, including consultation with independent financial adviser Greenhill (a Mizuho affiliate) and external legal counsel, the Ingenia Board concluded that the Revised Indicative Proposal “substantially undervalues Ingenia” and is not in the best interests of securityholders. Ingenia securityholders do not need to take any action at this time.
When big ASX news breaks, our subscribers know first
What a scheme of arrangement means for investors
A scheme of arrangement is a court-approved transaction structure used in Australian mergers and acquisitions. Under this process, a target company’s board must recommend the deal to securityholders, who then vote on it — and the court must ultimately approve the outcome.
This mechanism is precisely why the “unanimous recommendation of the Ingenia Board” is listed as a condition of Warburg Pincus’s proposal. Without Board support, the scheme of arrangement pathway is effectively closed, at least for now.
It is also worth clarifying what this proposal is and is not. Warburg Pincus has made a non-binding indicative proposal, not a formal bid. This means there is no legal obligation on Ingenia to engage, negotiate, or put any offer to securityholders. The Board retains full discretion over how, or whether, to proceed.
The “less any future distributions” clause carries a practical implication for investors. Any distributions paid by Ingenia between now and a hypothetical deal closing would reduce the effective cash consideration received per stapled security. Investors evaluating the offer’s attractiveness relative to Ingenia’s expected income stream would need to factor this in.
The key takeaway: the Board controls the next step, not Warburg Pincus.
Why the Board believes $5.05 falls short
The Board’s rejection followed a structured review process. Greenhill, a Mizuho affiliate, was appointed specifically as independent adviser to the Board in relation to the proposal, with the announcement noting this reflects the Board’s “commitment to a rigorous process and assessment.” External legal counsel was also engaged.
The Revised Indicative Proposal was subject to several conditions, including:
- Satisfactory completion of due diligence
- Documentation
- Regulatory approvals
- Unanimous recommendation of the Ingenia Board
- Ingenia not proceeding with the proposed acquisition of Peet Limited
The condition relating to Peet Limited is particularly notable. By requiring Ingenia to abandon its proposed acquisition of Peet Limited as a prerequisite for the deal, Warburg Pincus has effectively signalled concern about Ingenia’s growth strategy. The Board’s decision to proceed on its own terms, without entertaining this condition, reflects its commitment to that strategic path.
The proposed acquisition of Peet Limited, structured as a cash-and-scrip scheme at $2.185 per share, represents a 29% premium to Peet’s undisturbed price and carries approximately $1 billion in identified synergy potential from land lease conversion across Peet’s pipeline.
Despite the rejection, the Board has left the door open, communicating directly to Warburg Pincus and its advisers that it remains willing to consider offers that meet a higher bar.
Ingenia Board Statement
“The Ingenia Board remains open to considering proposals that represent compelling value and are considered to be in the best interests of securityholders.”
This language is a clear signal: a materially higher proposal may receive a different response. The phrase “compelling value” sets a threshold without disclosing a specific target price.
Ingenia’s investment case stands on its own
The Board expressed confidence in Ingenia’s strategic direction and growth trajectory independent of any takeover outcome. The Group remains focused on executing its strategic plan and delivering long-term value to securityholders.
Ingenia operates across four business divisions — Ingenia Lifestyle, Ingenia Gardens, Ingenia Holidays and Ingenia Rental — collectively spanning 96 communities and development sites, with growth continuing through both acquisition and development.
With a market capitalisation of $1.7 billion and inclusion in the S&P/ASX 200, Ingenia is a material player in Australian seniors accommodation. The Board’s rejection of two successive offers signals that it views the Group’s intrinsic value — anchored in a defensive, needs-based platform serving a growing demographic — as exceeding what either proposal has recognised. The strategic plan remains in place, and management is focused on delivering on it.
For readers wanting to understand the asset base underpinning the Board’s valuation confidence, our dedicated guide to Ingenia’s $2.9 billion property portfolio walks through all four business divisions, occupancy metrics, and the 4,946-site development pipeline that anchors long-term recurring income growth.
Don’t Miss the Next Real Estate Takeover Move
Get FREE breaking ASX real estate news delivered to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ subscribers staying ahead of market-moving developments. Click the “Free Alerts” button at StockWire X to start receiving alerts the moment news breaks.