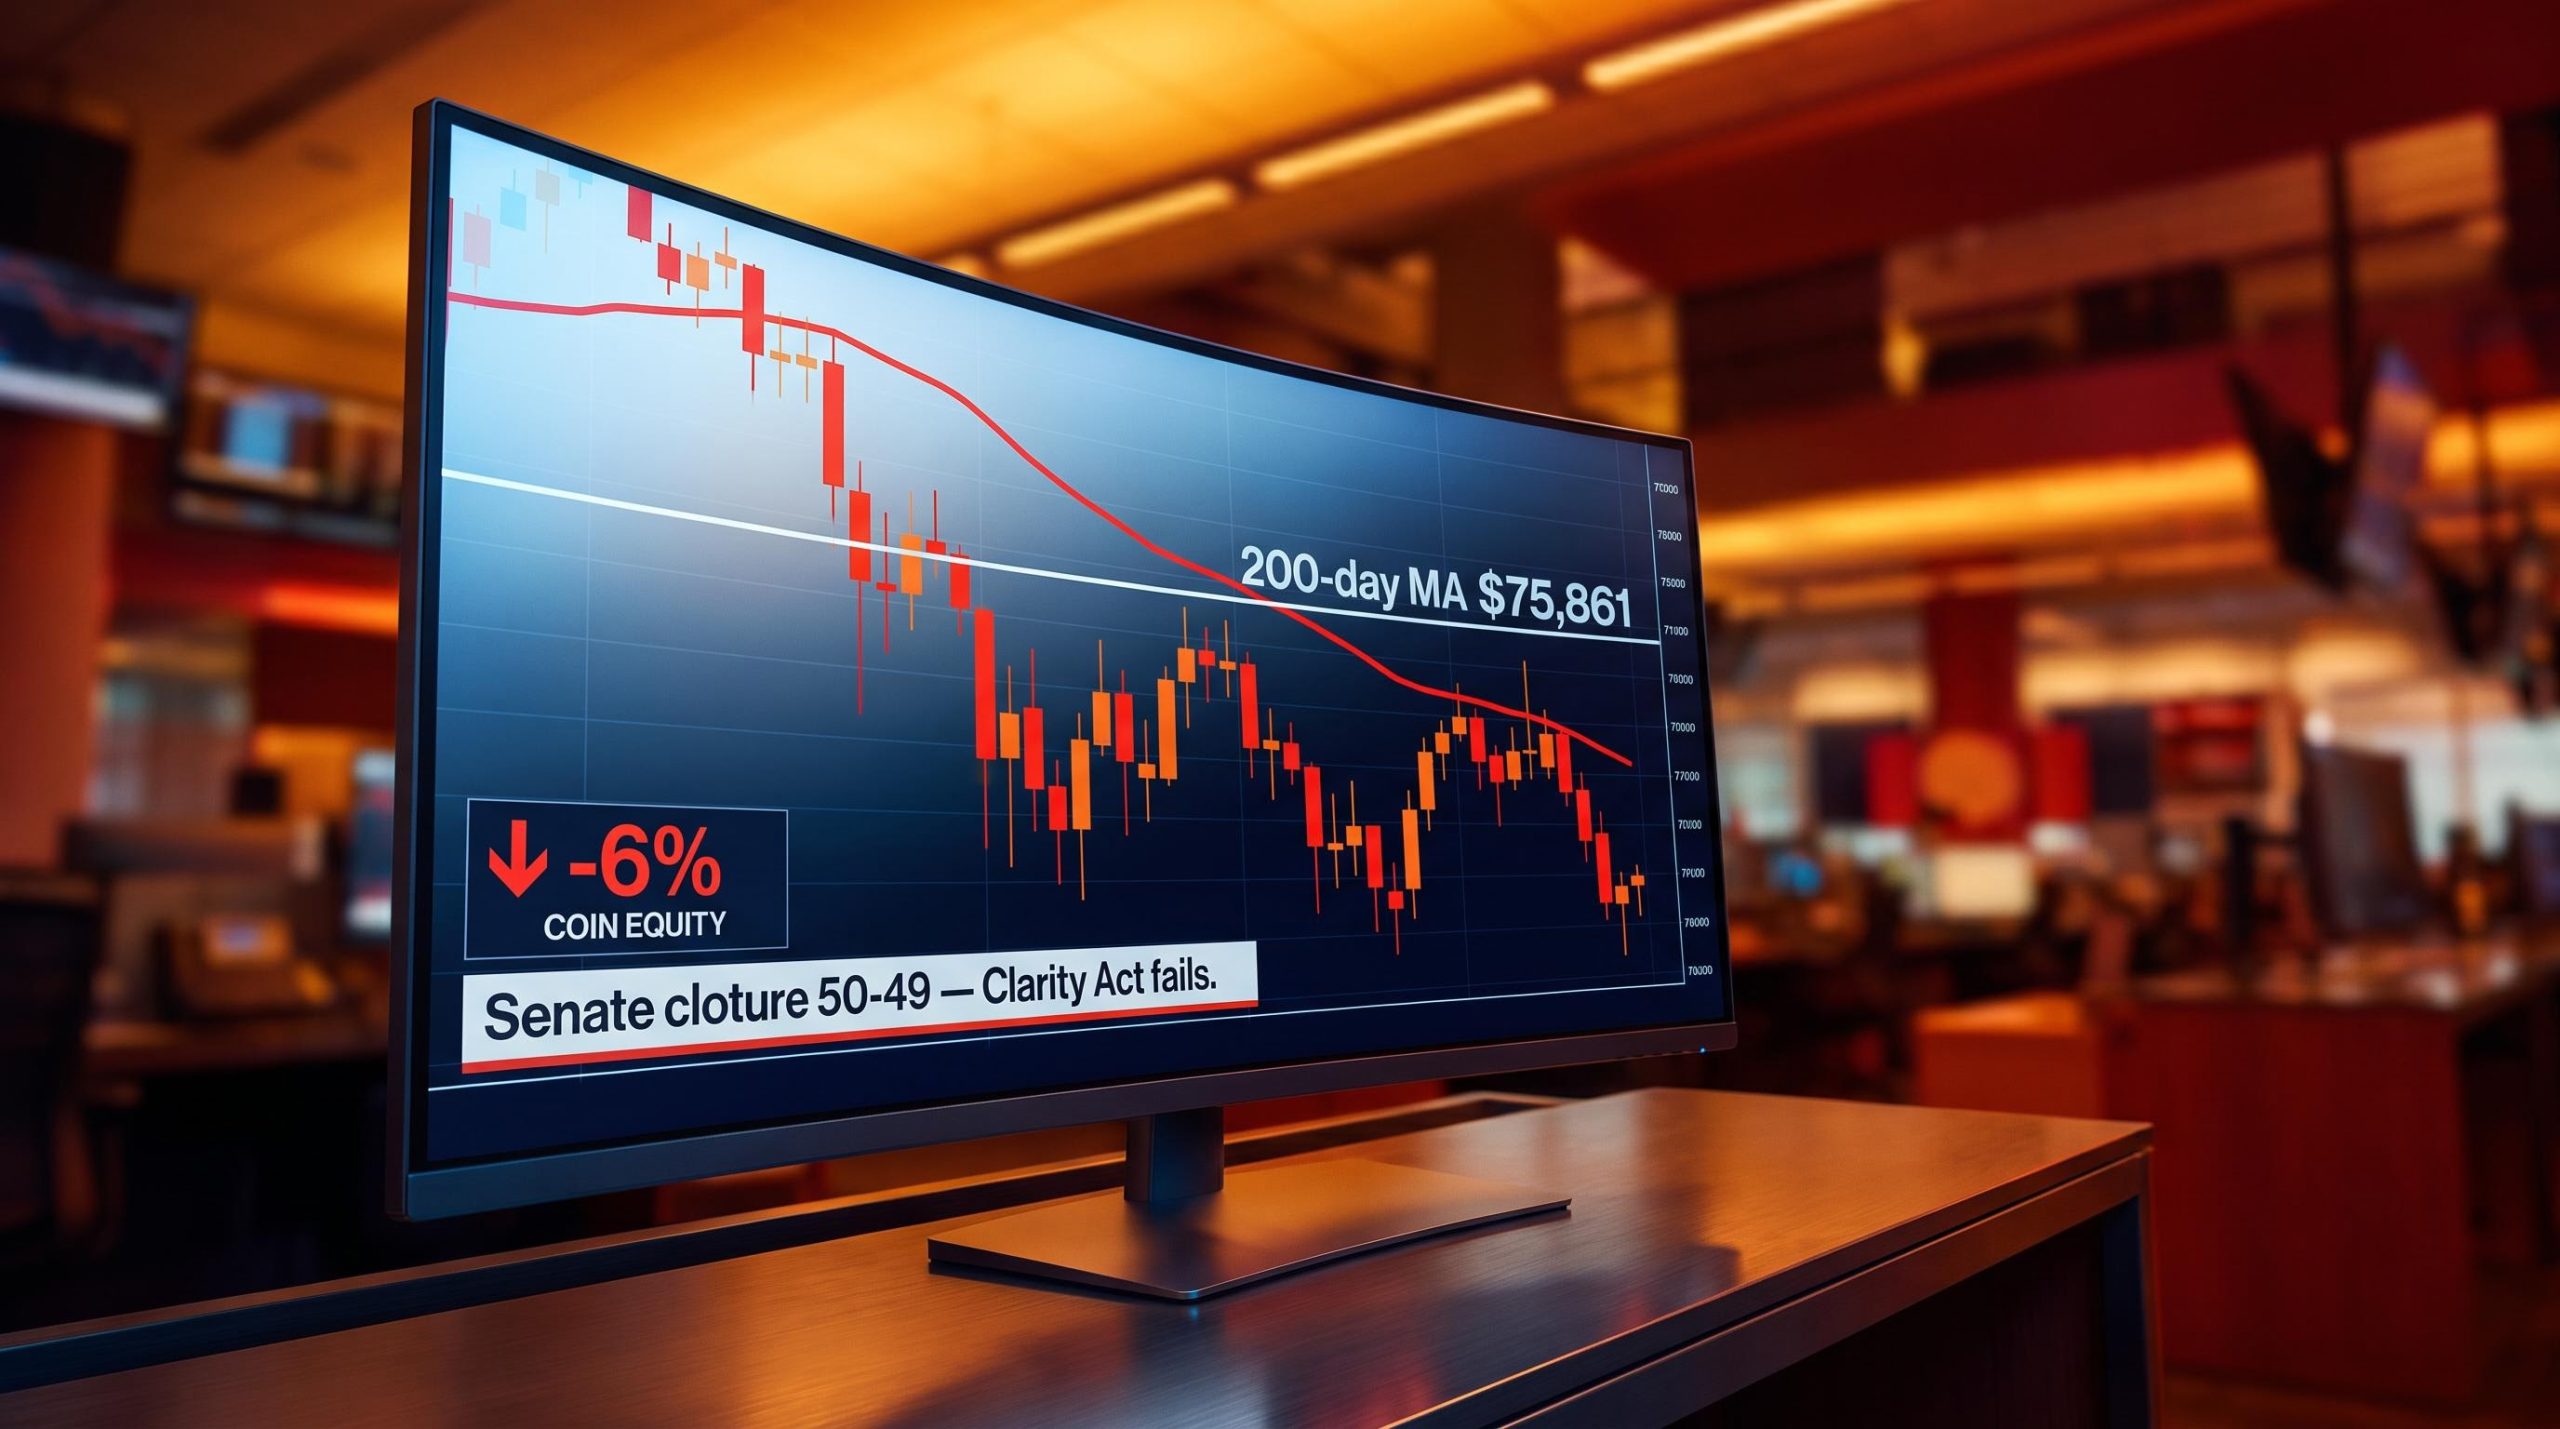
Two of the most heavily owned speculative themes in U.S. markets are cracking at the same time. Bitcoin has broken below its 200-day moving average, crypto-related equities are down sharply after the death of landmark market-structure legislation, and the AI sector is heading into its most consequential IPO cycle with bubble-risk questions circling Anthropic’s expected autumn listing.
These are not unrelated tremors. When speculative leadership breaks down in concert, the effect on broader risk appetite is non-linear, and the crypto and AI market risk building across portfolios right now tests the weight-bearing capacity of a market that has concentrated extraordinary capital into a narrow set of secular growth stories.
The timing sharpens the stakes. Congress is out until after the midterms, the Federal Reserve is watching, and election uncertainty layers policy risk onto an already pressured setup. What is laid out below gives a clear framework for why these two breakdowns are happening at the same moment, how they interact across a portfolio, and which specific variables to track as conditions evolve.
How the Clarity Act’s collapse broke crypto’s legislative premium
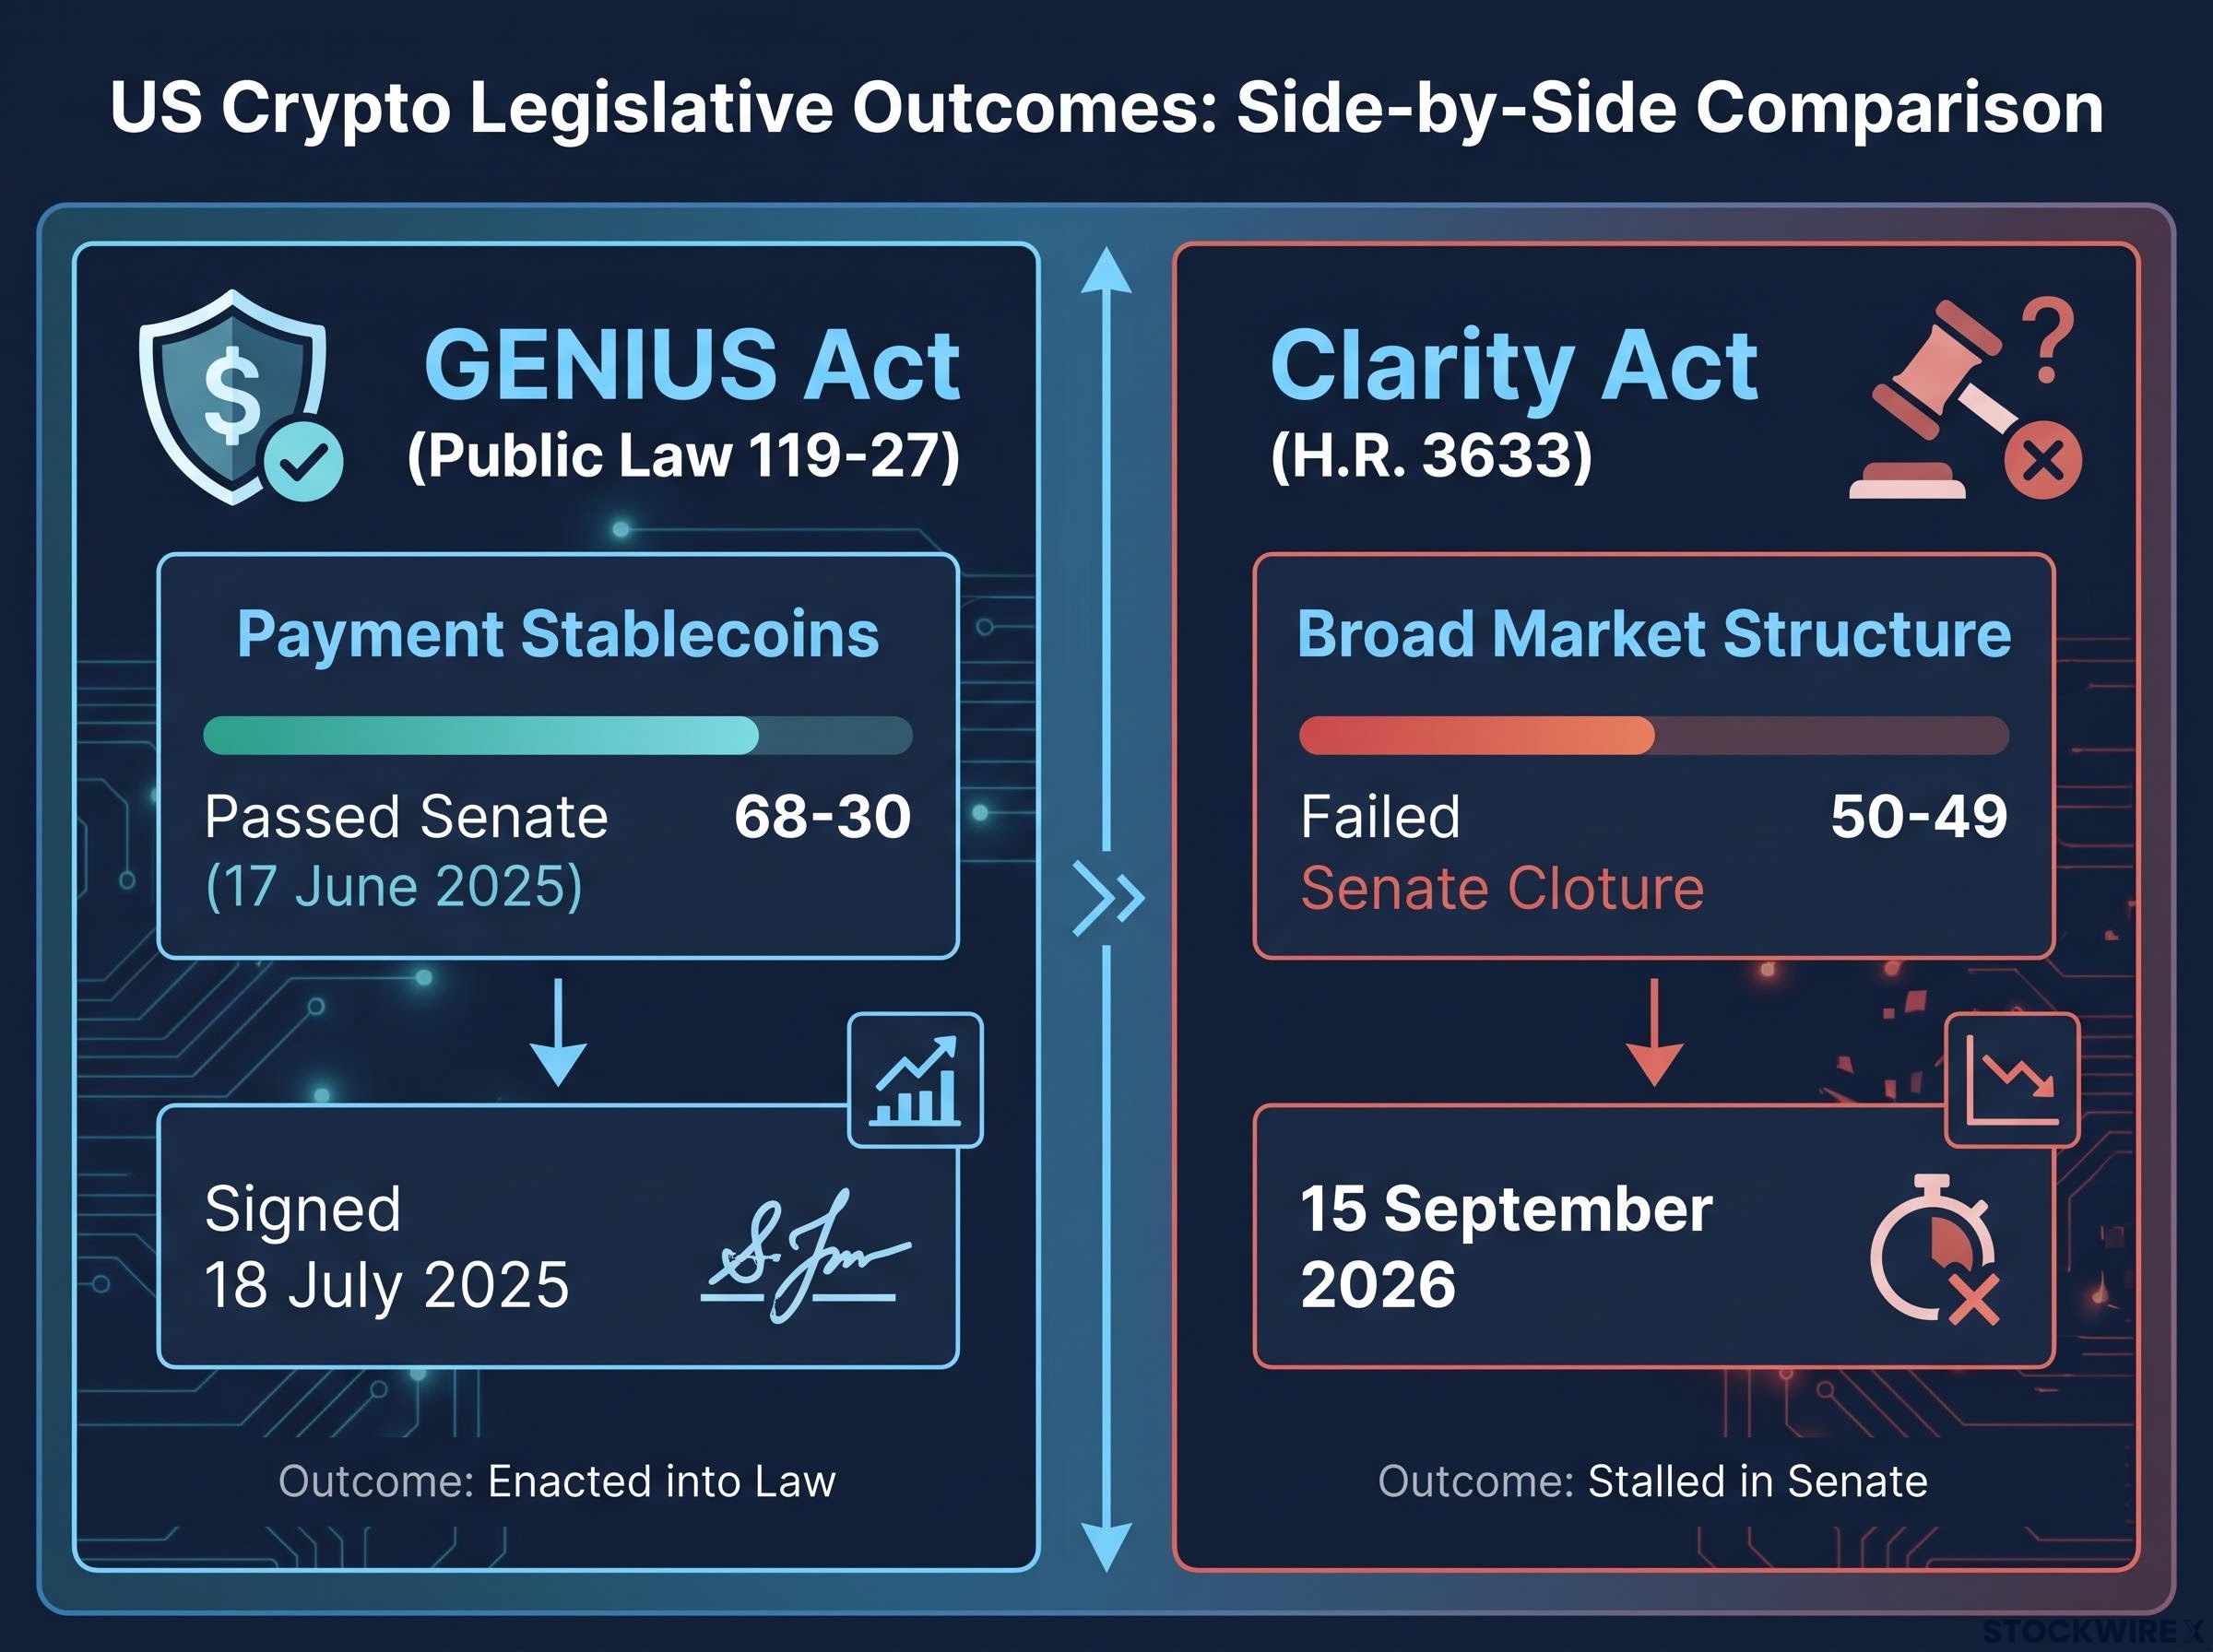
The number that mattered arrived on 15 September 2026. A Senate cloture vote on the motion to proceed with the Clarity Act (H.R. 3633), the comprehensive crypto market-structure bill, failed 50-49. That single tally stalled the most important piece of digital-asset legislation in the pipeline.
Cloture vote result, 15 September 2026 The Senate motion to proceed on the Clarity Act (H.R. 3633) failed 50-49, leaving broad crypto market structure without a legislative framework.
The equity reaction told the market’s real position. Coinbase fell roughly 6% in the relevant session, Strategy (formerly MicroStrategy) dropped about 3.67% despite sitting near technical support, and Circle Internet slid sharply across two consecutive sessions after the vote.
The Clarity Act cloture failure did more than stall legislation; Coinbase’s roughly 10% single-session drop reflected the exchange’s direct exposure to US regulatory conditions in a way that Bitcoin’s multi-jurisdictional pricing base did not, confirming that crypto equities carry a legislative risk premium that Bitcoin itself partially offsets.
What was being drained here was not ordinary price discovery. Crypto equities had been carrying a “passage premium,” a chunk of valuation that assumed comprehensive legislation would arrive and legitimise the sector’s business models. The cloture failure removed that assumption in a single afternoon, which is mechanically different from investors simply deciding a stock is expensive.
That distinction matters for you if you hold these names. The question shifts from “has the selling been overdone?” to a harder one: what is the correct valuation for a crypto equity in a regime of ongoing regulatory ambiguity? That is a longer-horizon problem, and it may have further to run until a new legislative timeline becomes visible.
The regulatory picture is not uniformly bleak. Three distinct outcomes now sit side by side:
- Clarity Act: Failed Senate cloture 50-49, broad market structure left in limbo.
- GENIUS Act: Enacted as Public Law 119-27 for payment stablecoins, giving that corner of the market a working framework. It reportedly passed the Senate 68-30 on 17 June 2025 and was signed into law on 18 July 2025 (unverified).
- Regulators: Signalled they will proceed under existing authority rather than wait for Congress.
The problem is timing. Congress will not reconvene before the midterm elections, so the earliest realistic window for revisiting the bill is post-vote. Academic research suggests unexpected regulatory blockades have historically triggered average crypto price drops of 5.2% over three days and 17.2% over 30 days (unverified), which frames the current decline as a valuation reset embedding a structural risk premium, not a one-session panic.
When big ASX news breaks, our subscribers know first
Bitcoin’s technical breakdown and what the chart is actually saying
Read the Bitcoin chart as a series of decisions the market has already made, not a scatter of numbers. Through mid-September 2026, the price oscillated between roughly $75,774 and $78,173 (unverified), sitting just above a line it had already lost.
That line is the 200-day moving average at approximately $75,861 (unverified). A moving average smooths out daily noise to show the intermediate trend, and a break below the 200-day version signals that the medium-term direction has turned lower. The market crossed it.
This was a continuation, not a fresh shock. In early September, Bitcoin repeatedly failed to reclaim resistance in the low $80,000s, reaching as high as $79,697 on 4 September before retreating (unverified). Ethereum did something similar, briefly poking above its own resistance before that level held and sent it back down. Each failure was the market declining to pay up.
The Bitcoin technical structure entering the current breakdown had already printed a significant pattern in late August, when an inverted head-and-shoulders completion drove a near $4,000 single-session surge toward $84,000 before resistance at that level reasserted itself and set up the subsequent failure to reclaim the low $80,000s.
Below current prices, the support structure tiers into progressively higher-stakes levels.
| Level type | Price level | Status | Significance |
|---|---|---|---|
| Key resistance | $82,793 | Not reached | Ceiling capping any recovery attempt |
| 200-day moving average | $75,861 | Broken | Intermediate trend has turned lower |
| Near-term support | $75,674 / $71,781 | Being tested | First lines where buyers must defend |
| Deeper targets | $62,677 / $57,776 | Prior low / 2026 low | Where capitulation historically clusters |
All figures in the table are flagged as unverified. The break below the 200-day average reportedly opened short-term targets at $73,308, $72,879 and $70,005, with the 17 August low near $62,677 and a possible retest of the 2026 low near $57,776 as the deeper-risk scenario (unverified).
For any U.S. investor with crypto exposure, these levels are more actionable than macro commentary, because they are where forced selling and capitulation events tend to concentrate. The open question is whether the $71,781-$75,674 zone holds or gives way.
Altcoin breadth confirms this is a market-wide repricing, not a Bitcoin-specific event
The weakness is not contained to Bitcoin. Cardano and Litecoin peaked back during the prior altcoin cycle and remain in severely deteriorated technical condition, sitting well below their previous highs.
That is a breadth signal, not just sector-specific noise. When the riskier tiers of the crypto market have already broken down while Bitcoin is only now testing support, it tells you speculative capital rotated out of the high-beta names first. That rotation typically precedes or accompanies broader crypto stress rather than marking its bottom.
The Anthropic IPO and what it reveals about AI concentration risk
While crypto breaks down, the AI sector has been holding broad equity markets up. That pillar now faces its own stress test, and the trigger is a listing.
Anthropic has had a confidential S-1 on file since 1 June 2026 and is working toward an autumn 2026 IPO. The confidential route lets a large issuer complete SEC review and refine its accounts privately before going public, a standard feature for offerings of this size. Underwriters are reportedly targeting a marketing window in mid-October 2026, just ahead of the November midterms (unverified).
The scale of the question is best captured by the valuation spread. Expectations reportedly range from $965 billion to as high as $2.8 trillion (unverified), an unusually wide band that signals how little consensus exists on what the AI growth story is actually worth.
The provocative number Anthropic’s offering has reportedly been discussed at an estimated price-to-sales ratio of 22x on over $44 billion in annualised revenue (unverified). Price-to-sales measures a company’s market value against its revenue, and 22x is a valuation that demands sustained, high-quality growth to justify.
That figure is the crux. The IPO is not just a single-stock event; it is a valuation referendum on the entire AI narrative. If the market receives the deal poorly, or underwriters trim their targets, the repricing will not stay confined to Anthropic’s stock.
The reason it spills over is concentration. The evidence clusters into a few striking numbers, all unverified:
- AI stocks are reportedly nearing 45% of total index weight in the S&P 500.
- The Magnificent 7 account for roughly 34% to 35% of the index’s total market value.
- Semiconductor and AI-hardware firms contributed close to 60% of the MSCI World Index’s total return in a single quarter.
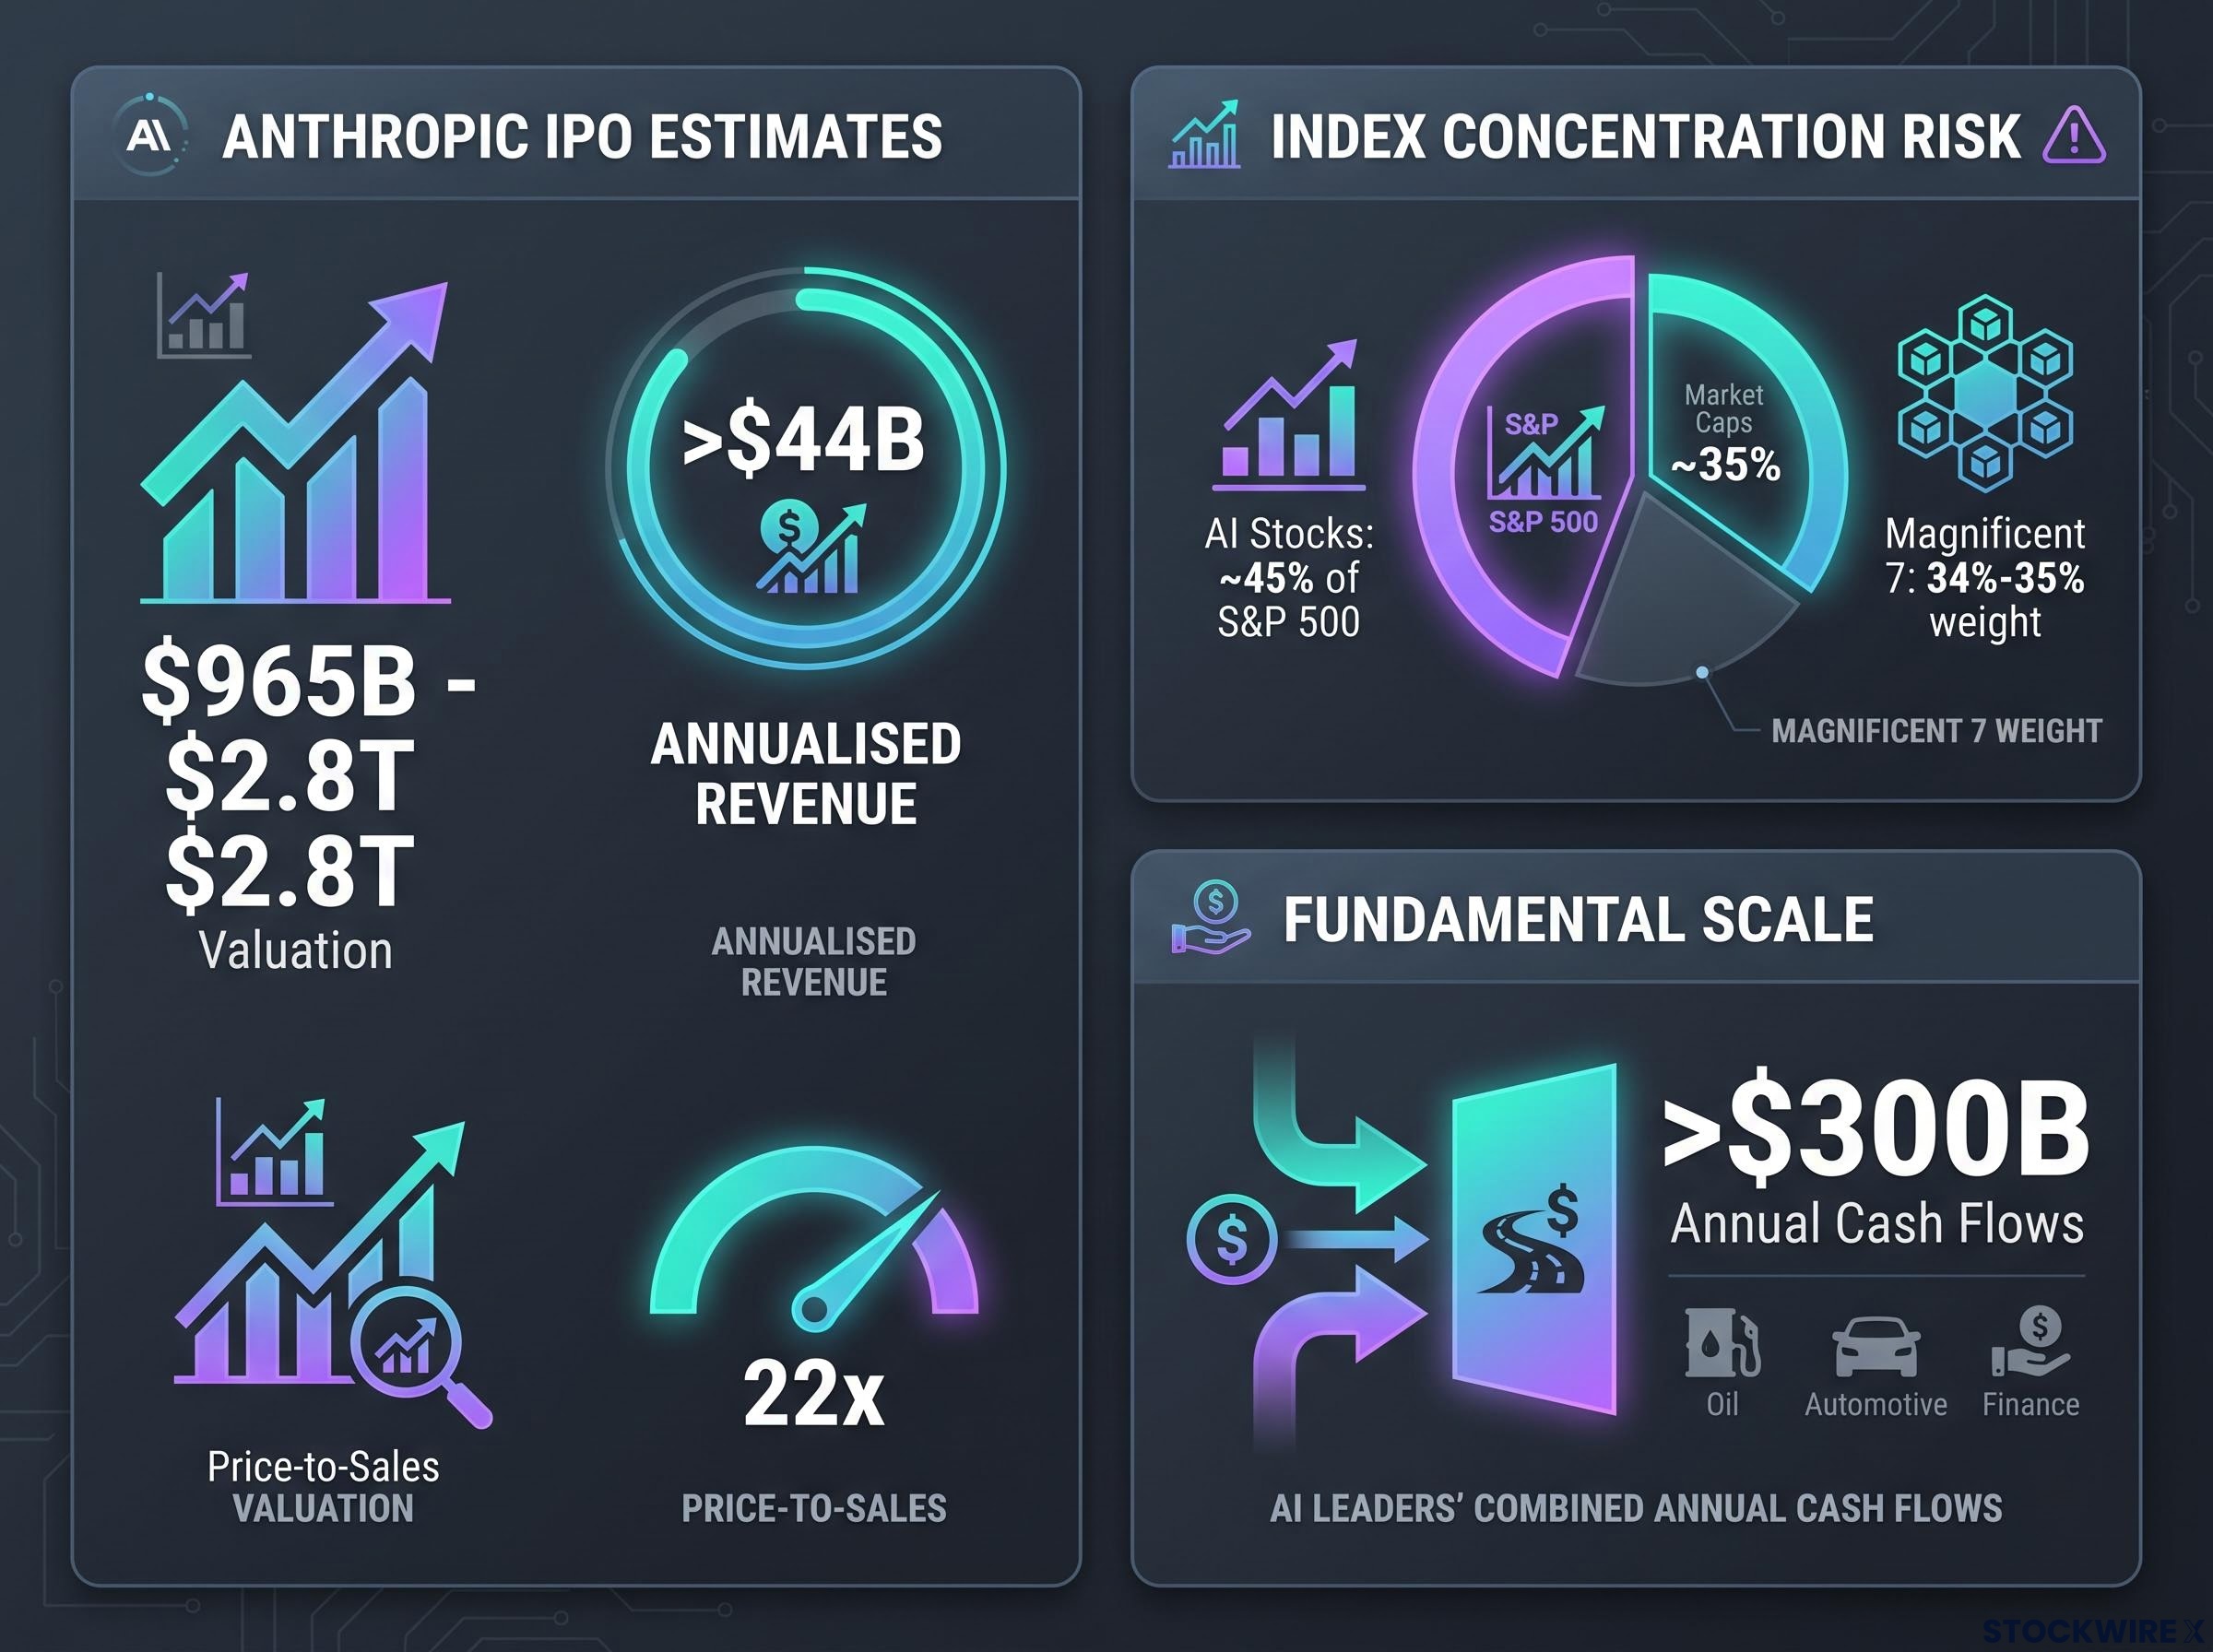
Today’s AI leaders are not the loss-making startups of 1999-2000. Their cash flows reportedly exceed $300 billion annually (unverified), so the primary risk is not balance-sheet fragility. It is capex misallocation and extreme breadth narrowness, a market leaning its full weight on a handful of names.
Why index concentration turns an AI repricing into a systemic event
Concentration is what converts a single-sector wobble into an index-wide problem. When mega-cap AI stocks reprice, passive and active funds are forced to rebalance at the same time, and that simultaneous selling amplifies the drawdown beyond what the underlying fundamentals alone would justify.
Index concentration at the current scale, with five companies controlling roughly 30% of total US equity market capitalisation and the top 10 S&P 500 stocks representing around 40% of index weight, means passive investors are exposed to the AI cluster by construction, not by choice, and any repricing of that cluster cascades across funds with no direct AI mandate.
If you hold a broad index fund, you are, by construction, heavily exposed to this cluster. An IPO that functions as a forced valuation disclosure should change how a passive investor thinks about index risk over the next two months.
Regulators are already tracking the mechanism. The Financial Stability Board (FSB) and the UK Financial Conduct Authority (FCA) have warned that AI-driven trading strategies, combined with programmable tokenised assets, could amplify herding behaviour and procyclical leverage.
Where crypto and AI risk converge into a single portfolio problem
The temptation is to treat these as two separate stories. The more useful read is that they share a common driver: the repricing of speculative premium across assets whose valuations depend on uninterrupted regulatory and fundamental tailwinds. Remove the tailwind, and both reprice.
The convergence is not just thematic; it is structural. The same automated AI-driven trading strategies that move equities are increasingly wired into crypto markets through programmable tokenised assets and automated trading agents.
The regulators’ warning The FSB and FCA have flagged that highly correlated AI-driven trading strategies, combined with the programmable nature of tokenised money, could amplify herding behaviour and procyclical leverage, raising the risk of rapid, self-reinforcing sell-offs when both sectors are stressed at once.
AI model convergence is the specific mechanism regulators are flagging: when institutions train on overlapping datasets and architectures, their strategies correlate more than their risk systems show, and the same tightening of spreads that benefits investors on calm days becomes correlated exit behaviour when stress conditions trigger simultaneous de-risking.
That interconnection is why stress in one can accelerate stress in the other. The research is clear that stablecoins and crypto assets do not yet pose a catastrophic threat to core banking solvency, so this is not a 2008-style solvency argument. It is a liquidity and de-risking argument.
The pressure is not confined to U.S. borders either. Weakness in the MSCI EAFE Index (traded via EFA) has been partly tied to AI bubble concerns spreading globally, a signal that the risk-off impulse is travelling across international markets rather than staying domestic.
Here is the part that reframes your own positioning: holding AI-heavy index exposure alongside a crypto position may look diversified, but if both are expressions of the same risk appetite, you are concentrated on a single factor. Three variables will determine whether this dual breakdown stabilises or accelerates over the next 60 days.
- The Anthropic IPO reception. A poorly received deal or reduced underwriter targets would function as a broad AI valuation reset, not a contained event. Expected mid-October 2026.
- A Congressional timeline for the Clarity Act. Any credible new legislative path would begin restoring the passage premium; nothing is likely before the post-midterm session.
- Bitcoin at the $71,781-$75,674 support zone. Whether this band holds or breaks tells you if crypto selling is stabilising or entering a deeper leg (levels unverified).
What the dual breakdown changes, and what it does not
The simultaneous breakdown in crypto and AI-adjacent risk signals a phase shift in speculative risk appetite. That is different from a systemic financial crisis, and the distinction should shape how you respond. Treating a repricing like a solvency event leads to overcorrection.
The structural difference from 2000 is real. Today’s AI leaders carry genuine revenue scale and cash flows reportedly exceeding $300 billion annually (unverified), so the risk is concentration and capex misallocation, not the absence of a business model.
What has changed is that two near-term catalysts now carry unusually high informational value. The Anthropic IPO marketing window, expected in mid-October 2026, and Congress reconvening after the midterms will do more to resolve current uncertainty than any macro data release in the interim.
For investors with concentrated exposure to either theme, the useful question is not whether to panic. It is what your re-entry or exit criteria actually are, defined before the IPO prices and before the next Congressional session, rather than waiting for a certainty that will not arrive in time.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results, and these forward-looking statements are speculative and subject to change based on market developments.