The Bank of Japan is expected to raise rates this week, and most analysts agree on what that means for the yen: it goes up. What they disagree on is how much, and more importantly, what happens if the BoJ says the right words in the wrong tone.
With USD/JPY trading near seven-month lows around 153.50 and markets pricing roughly 75 to 100 basis points of cumulative BoJ hikes over the next year, the meeting lands at a moment when positioning, carry-trade dynamics, and central bank communication are all pulling on the currency at once. The rate decision itself is almost priced in. What is not priced in is everything that happens after Governor Kazuo Ueda opens his mouth.
This piece maps the specific scenarios that move the yen in each direction: which outcomes amplify gains, which create the surprise reversal, and what structural forces are running underneath the policy decision regardless of what the BoJ announces. After reading, any Japanese Yen forecast you encounter this week will make more sense, because you will have a framework for interpreting the outcome in real time rather than reacting to the headline number.
What the market has already priced in before the BoJ meets
Here is the thing to understand before the meeting even starts: the yen’s recent move is not a bet on the future. It is a repricing of something markets now treat as close to certain.
A 25 bps hike to 1.25% is the overwhelming base case. Market pricing ahead of the meeting assigned roughly an 84% probability to that outcome, according to CondorEdge’s BoJWatch tracking in mid-September 2026. A Reuters poll published on 10 September 2026 found economists expect the policy rate to reach 1.25% at this meeting.
Economists surveyed by Reuters on 10 September 2026 expect the Bank of Japan to lift its key policy rate to 1.25% at this week’s meeting.
That expectation is already sitting inside the exchange rate. When you see USD/JPY near 153.50, you are looking at a price that has absorbed the hike, not one waiting for it.
The July hold decision, delivered 8-1 with dissenter Hajime Takata explicitly pressing for an immediate hike to 1.25%, was the moment the perceived distance to the September move shortened materially, because a named board member on record for faster tightening shifts how markets calibrate the next meeting’s probability.
Here is the pre-meeting snapshot in one place:
- Current USD/JPY level: around 153.50, near seven-month lows
- Four-week range: approximately 152.89 (intraday low, 8 September) to 160.18 (close, 1 September)
- Market-implied probability of a 25 bps hike: approximately 84%
- Cumulative hikes priced over the next year: approximately 75 to 100 bps
When a market has already moved this far to reflect an expected outcome, the actual delivery of that outcome produces a smaller additional move than you might assume. The upside from confirmation is thin. The downside from disappointment is large. That asymmetry is the whole story, and it is why the communication that follows the decision matters more than the decision itself.
How the yen moved before the decision
The trajectory tells you how much has already happened. USD/JPY closed near 160.18 on 1 September 2026, then fell to an intraday low of 152.89 on 8 September, a seven-month low. That is a substantial repricing in a single week, driven entirely by shifting expectations rather than any action the BoJ has taken.
The pair then steadied, closing near 153.54 on 13 September 2026. That is stabilisation, not reversal. The yen has done most of its pre-meeting work, which means the fresh information now sits in the tone, not the number.
When big ASX news breaks, our subscribers know first
Why raising rates by 25 or 50 basis points both point toward yen strength
Stand at the fork in the road for a moment. Both paths the BoJ might take on the hike itself lead to a stronger yen. They just get there by different mechanisms and with different force.
The 25 bps base case is hawkish on its own terms. It confirms the tightening trajectory, extends the momentum already in the currency, and requires no surprise to do so. BBH analyst Elias Haddad frames this as the base-case hawkish outcome, one that keeps the yen’s existing move intact.
The 50 bps scenario is an amplifier rather than a change of direction. It would catch a market positioned for 25 bps off guard, forcing faster carry-trade unwinding and a sharper move. A Reuters analysis on 8 September 2026 noted the BoJ currently has “little appetite” for a move of that size, which is exactly why it would land as a surprise if it happened.
| Outcome type | Rate move | JPY implication | Expected magnitude | Key reference |
|---|---|---|---|---|
| Base case (hawkish) | +25 bps to 1.25% | Extends existing yen strength | Moderate, largely priced | BBH, Elias Haddad |
| Upside surprise | +50 bps | Amplifies yen gains sharply | Large, forces short covering | Reuters, 8 Sep 2026 |
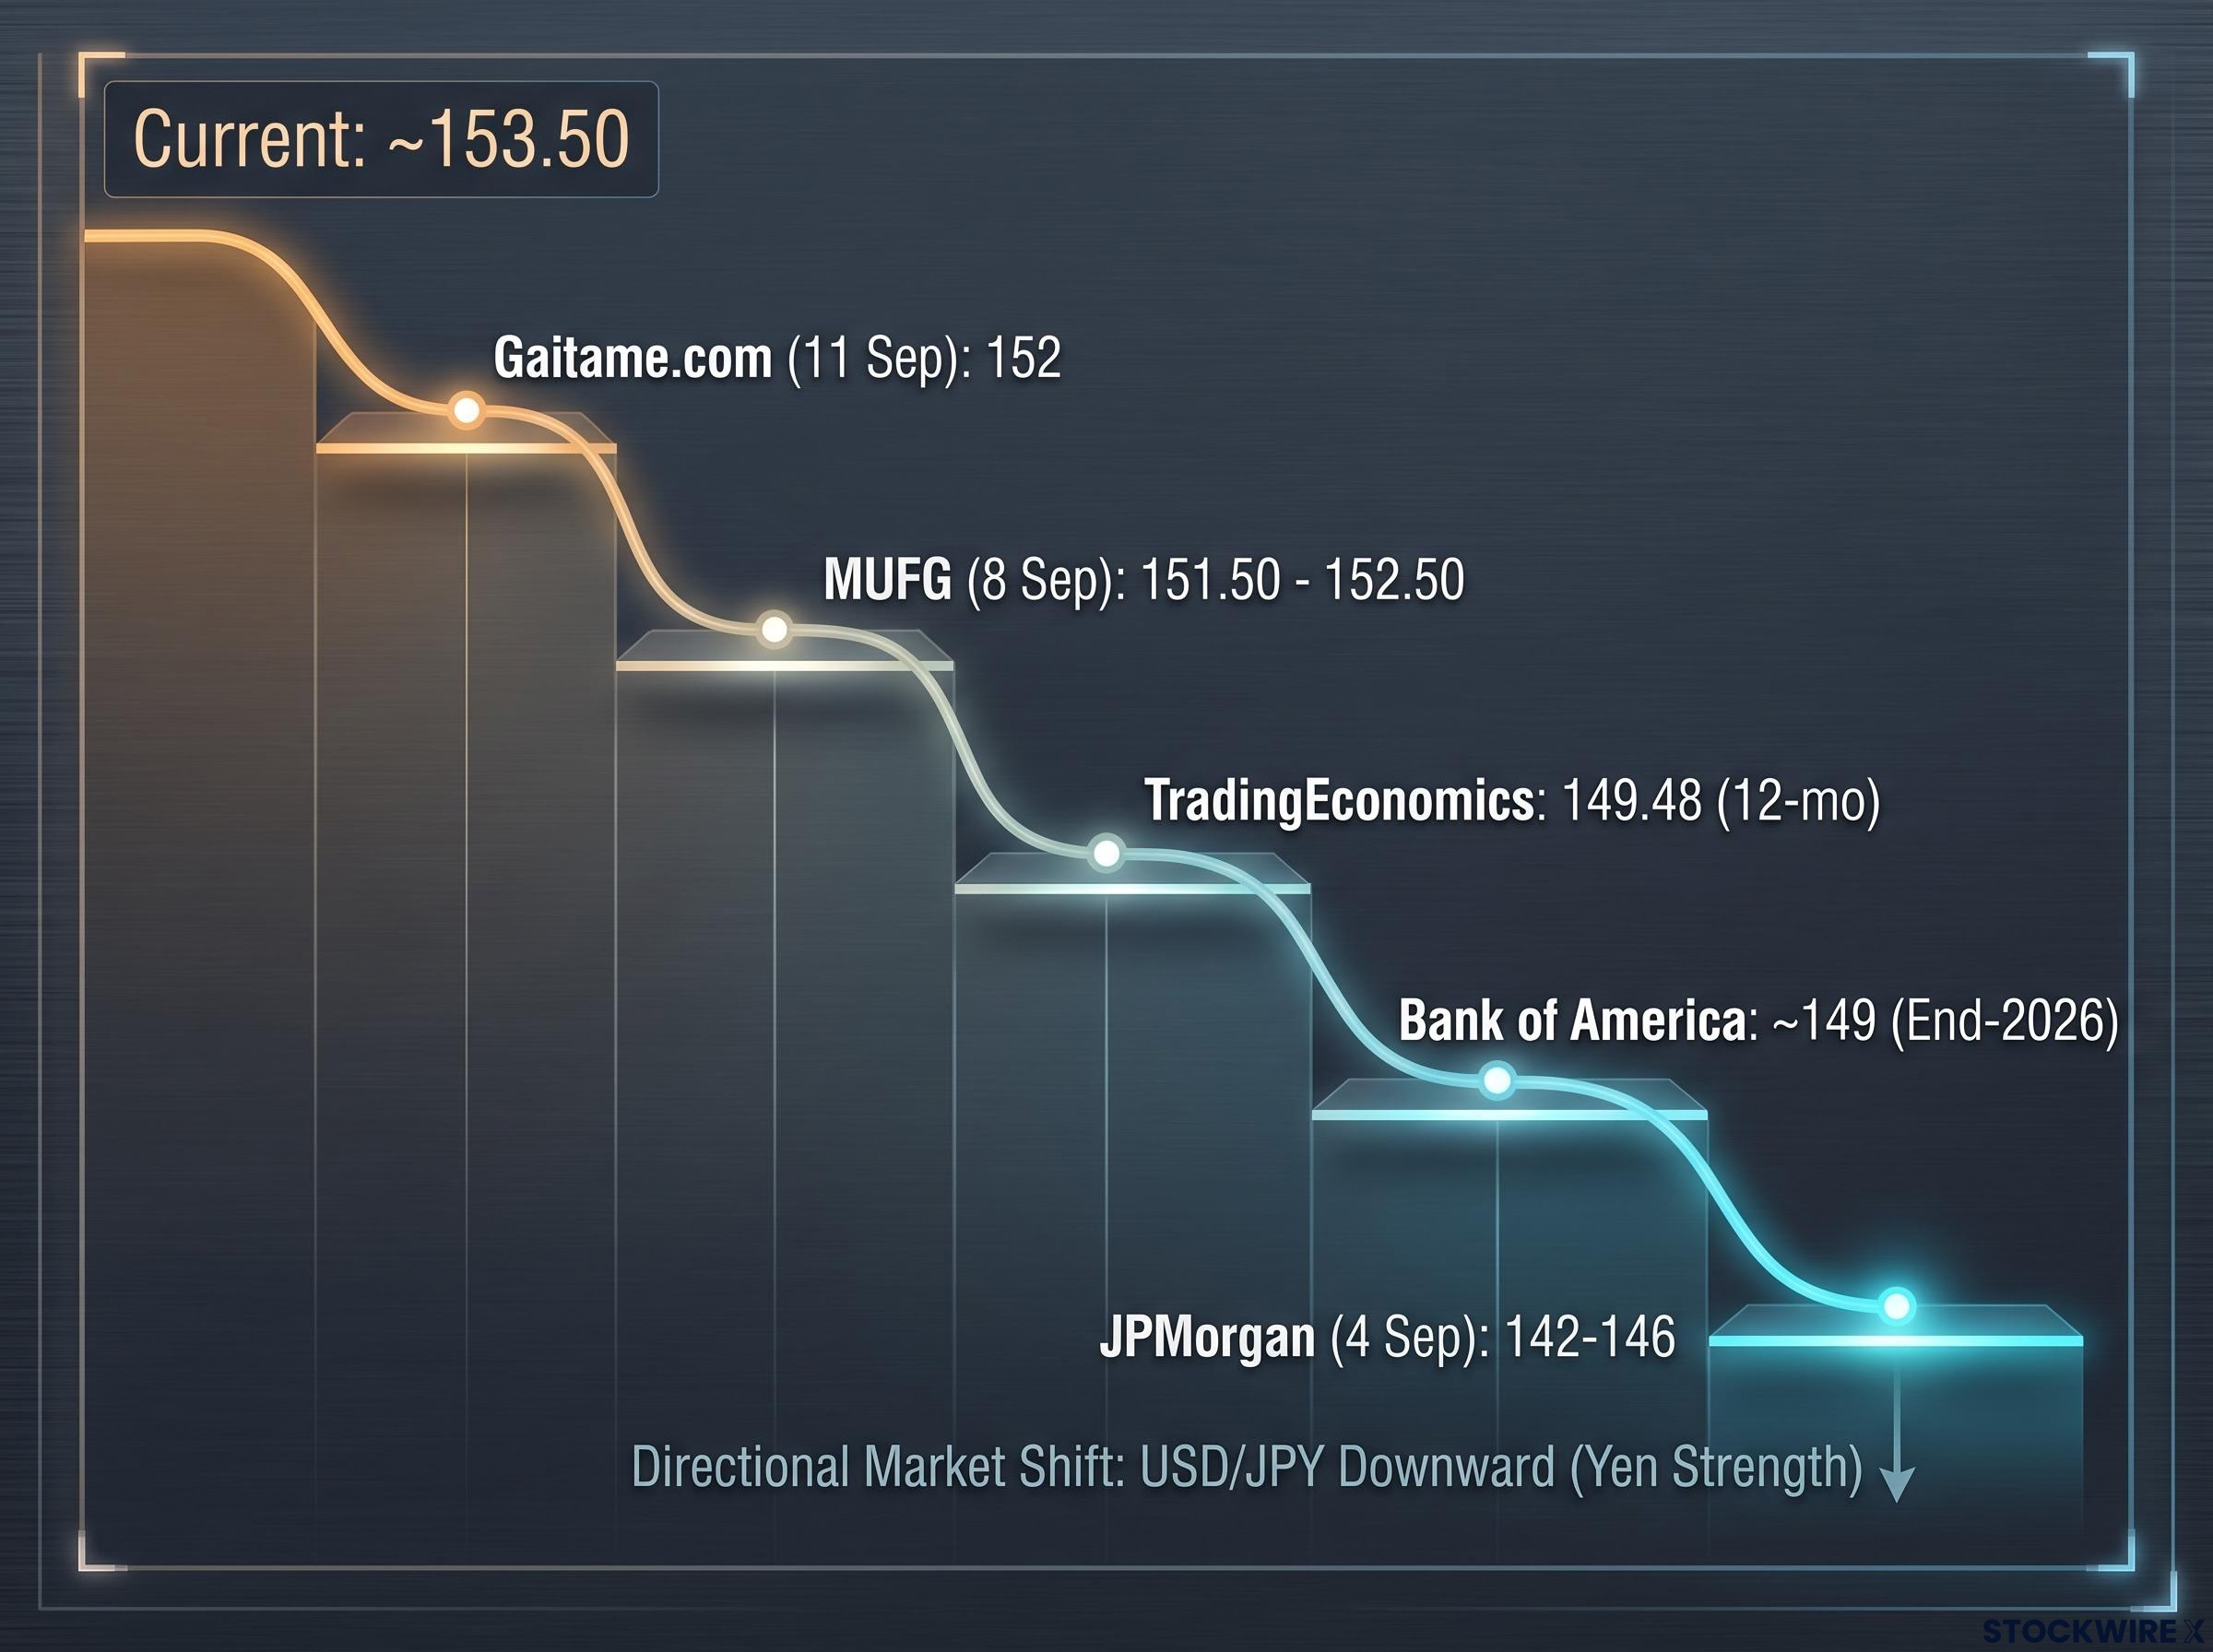
The institutional targets show how far the more aggressive scenario could run. MUFG’s technical analysis on 8 September 2026 flagged the January low below 152.50 or a retracement near 151.50 as the next downside targets for USD/JPY. Bank of America projected the yen reaching around 149 per dollar by end-2026. JPMorgan sits at the far end.
JPMorgan strategists Junya Tanase and Ikue Saito warned on 4 September 2026 that unwinding large speculative short positions could drive USD/JPY down into the 142 to 146 range.
There is a positioning signal underneath all of this. As of 14 September 2026, CFTC data cited by the Economic Times showed yen futures speculators had turned net long for the first time since February. That flip from net short to net long tells you the market’s directional consensus has changed sides, and the flip itself creates fuel, because any remaining short positions now face pressure to cover, which pushes the yen higher still.
The practical read for you is this: because both rate outcomes are constructive for the yen, the meeting is a question of degree, not direction. That is a meaningfully easier risk to frame. You are not guessing which way the currency moves on the hike. You are gauging how hard.
The single scenario that reverses the yen: what Ueda says matters more than what the BoJ does
There is one path that breaks the pattern, and it does not run through the rate decision at all. It runs through the press conference.
A hike is now table stakes. The genuine wildcard is the tone Governor Ueda sets afterward, because a single dovish phrase could unwind weeks of yen appreciation in hours. BBH analyst Elias Haddad identifies this as the primary pathway to yen weakness even if the 25 bps hike is delivered on schedule.
What does dovish communication actually sound like? It is language that emphasises gradualism, data dependence, or growth concerns in a way markets read as signalling a slower pace of tightening than currently priced. Ueda would not need to say the hike was a mistake. He would only need to qualify the path ahead enough that traders reprice it downward.
Here is how the reversal unfolds, step by step:
- The BoJ delivers the expected 25 bps hike to 1.25%.
- Ueda’s press conference leans on gradualism, data dependence, or export and growth risks.
- Markets reprice the roughly 75 bps of cumulative hikes implied by April 2027 lower.
- The yen sells off despite the hike, because traders are pricing a shallower path, not the single step just taken.
This is not a hypothetical. It has happened.
In March 2025, a speech by Governor Ueda was interpreted as dovish. USD/JPY rose to around 150.6 and the yen weakened by roughly 0.4%, all without any change to the policy rate.
The signal was already there on 2 September 2026, when Ueda said the BoJ would debate a September hike based on inflation risks but pointedly declined to pre-commit. That deliberate ambiguity guarantees his post-meeting words will be dissected line by line. Wells Fargo, in a Bloomberg survey on 9 September 2026, went further, flagging concern that the BoJ may struggle to deliver the hikes markets expect at all.
If Ueda’s tone sounds cautious, the hike that just happened stops mattering to the yen’s near-term direction. Markets trade the path, not the individual step. Understanding where the information sits in this meeting, in the conference rather than the communiqué, is what separates reading the currency from reading the headline.
The structural forces running underneath this week’s decision
Step back from the meeting-week binary for a moment, because the yen’s appreciation case does not actually depend on any single BoJ decision. There is a macro architecture beneath the headline, and it has its own momentum.
The first force is carry-trade unwinding. Speculators built large short yen positions for years when the interest rate differential made borrowing in yen cheap and profitable. As that differential narrows, those positions are being closed, and closing a short means buying the currency back, which creates self-reinforcing yen demand. BCA Research described the yen carry trade as a “ticking time bomb” back in February 2026 and recommended long yen positions on exactly this dynamic.
Institutional repatriation flows add a layer beneath the leveraged carry unwind: Japan’s GPIF, the world’s largest pension fund, announced a tilt toward domestic assets in July 2026, and Ministry of Finance weekly flow data confirms that organic repatriation is amplifying the move independently of speculative position closing.
The second force sits in Washington, not Tokyo. Softer expectations for further US Federal Reserve hikes have narrowed the US-Japan yield gap, and that gap is the mechanical driver of USD/JPY regardless of what the BoJ does. Comments from Fed Governor Christopher Waller on 3 September 2026 curbed expectations for further Fed tightening, a shift that directly favours the yen.
The third is official support. StoneX analysts noted on 7 September 2026 that suspected Ministry of Finance interventions coincided with USD/JPY declines and helped push September hike odds past 62%.
The coordinated yen intervention of August 2026 introduced a bilateral diplomatic dimension the BoJ cannot ignore when calibrating pace: with the US Treasury publicly labelling the yen undervalued and participating directly in reserve operations, the 158-162 zone now functions as a politically sanctioned ceiling with two sovereigns behind it.
| Driver | Mechanism | Current status | Yen impact | Key caveat |
|---|---|---|---|---|
| Carry-trade unwind | Shorts cover as differential narrows | Futures turned net long (14 Sep) | Supportive | Can trigger risk-off dollar demand |
| Fed trajectory | Narrowing US-Japan yield gap | Waller curbed hike expectations (3 Sep) | Supportive | Fed path can shift again |
| MoF intervention | Official yen buying | Suspected activity early Sep | Supportive | May not persist at same intensity |
The point for your framing is that this structural case does not require the BoJ to deliver every hike markets have priced. The narrowing yield differential and the carry reversal create gravity toward a stronger yen that operates independently of any single meeting. Even TradingEconomics macro models, which assume a gentle path, project USD/JPY at 153.41 by end-Q3 2026 and 149.48 in twelve months.
Where the risks to this thesis sit
The constructive case is not unconditional. Four vulnerabilities could complicate it:
- BoJ under-delivery: If the bank sticks strictly to cautious increments while inflation runs hotter than expected, markets may judge the response insufficient and stall the rally.
- Dovish Ueda communication: The reversal pathway covered above remains the most immediate risk, capable of blunting recent gains in hours.
- Ministry of Finance intervention shifts: Official support may not continue at the same intensity, and a change in that policy could alter the trajectory.
- Paradoxical risk-off dollar demand: A sharp carry unwind often coincides with broader market stress, and dollar funding demand during those moments can push USD/JPY the other way even as the yen strengthens elsewhere.
There is also the BoJ’s own internal constraint. The bank remains wary that excessive yen strength and higher borrowing costs could harm Japan’s export sector, which could prompt it to deliberately slow the pace of tightening. On the terminal rate, Morgan Stanley strategists caution that broad market pricing of a 2.0% to 2.25% peak by late 2027 may be too aggressive.
Reading the meeting outcome in real time
So how do you actually read the outcome as it lands? Three scenarios cover the ground, and knowing which one is unfolding tells you which analyst target range to trust.
| Scenario | Rate move | Ueda tone | JPY implication | Relevant target |
|---|---|---|---|---|
| Base case | +25 bps | Hawkish | Constructive for yen | ~149 (Bank of America) |
| Surprise | +50 bps | Hawkish | Strongly bullish for yen | 142-146 (JPMorgan) |
| Reversal | +25 bps | Dovish | Negative short-term | ~152 (Gaitame.com) |
The tone is the variable you listen for. A hawkish Ueda leans into the inflation trajectory and frames normalisation as continuing at pace. A dovish Ueda qualifies the path as data-dependent in a way that caps expectations, or dwells on growth and export risks. Same hike, opposite currency reaction.
Notice what the analyst spread actually represents. Gaitame.com Research Institute analyst Tsutomu Nakamura called 152 per dollar a realistic near-term target on 11 September 2026. Bank of America sees around 149 by end-2026. JPMorgan sees 142 to 146 if speculative short unwinding accelerates. HSBC’s overnight index swaps summary on 7 September 2026 implied roughly 75 bps of cumulative hikes by April 2027.
BBH analyst Elias Haddad frames the risk profile as tilted toward further yen appreciation regardless of whether the hike lands at 25 or 50 bps.
That target range from 152 to 142 is not disagreement about direction. Every one of those numbers points to a stronger yen. It is disagreement about timing and pace, and this week’s communication from Ueda is the primary input that collapses the range toward one end or the other. Watch the tone, and you will know which target is in play.
What this week’s outcome changes, and what the structural case makes irrelevant
Hold the two timeframes side by side. This meeting creates short-term volatility. The structural trajectory runs on its own clock underneath it.
The risk profile is asymmetric in the yen’s favour. Two of the three scenarios, the hawkish 25 bps base case and the 50 bps surprise, produce yen gains. Only one, a 25 bps hike with dovish Ueda commentary, produces a reversal, and the structural backdrop is likely to absorb even that over time.
For this week, Ueda’s press conference language is the decisive variable. For the horizon beyond it, the narrowing US-Japan yield differential, the carry unwind, and the Fed’s trajectory are the frame that tells you how durable any move actually is.
The variables to track from here are the cumulative hike path priced through April 2027 and the terminal rate debate, where Morgan Stanley’s caution sits against broader market pricing. Those are what will decide whether the yen’s appreciation stays a meeting-week story or becomes a multi-quarter one.
For readers wanting a framework for separating a genuine systemic unwind from a repricing event, our deep-dive into yen carry trade risk assessment walks through the three-question diagnostic covering position size, intervention type, and fundamental shift, using the 2024 unwind and Japan’s 2026 intervention campaign as the two reference cases.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results, and these forward-looking projections are speculative and subject to change based on market developments.