


Energy One rejects $17.00-per-share, $550m-plus takeover bid from Norway’s Volue
Energy One Limited (ASX: EOL) confirmed on 30 July 2026 that its Board has unanimously rejected a revised, unsolicited, indicative, non-binding and conditional proposal from Volue AS to acquire the company for $17.00 per share in all cash.
The energy trading software provider disclosed that Volue’s Oslo-based approach, reported by the Australian Financial Review as a $550m-plus bid, was rebuffed on the basis that it undervalues the company in a change-of-control context.
Two competing narratives frame the situation. Volue describes its offer as a “substantial premium” to recent trading. The Energy One Board considers the revised proposal “opportunistic” and inconsistent with the company’s standalone value.
The $17.00 per share cash offer, submitted on 22 July 2026, marks an escalation from Volue’s earlier proposal of $16.50 per share lodged on 6 July 2026. Both approaches contemplated a board-recommended scheme of arrangement.
When big ASX news breaks, our subscribers know first
The offer on the table — premium claims vs. the board’s verdict
Volue framed its revised proposal as delivering immediate all-cash value at a substantial premium to Energy One’s recent share price performance. The offer price assumes, among other things, that no dividends, distributions or reductions in capital would be paid from the date of the proposal.
The following table sets out Volue’s stated premium calculations against various reference prices.
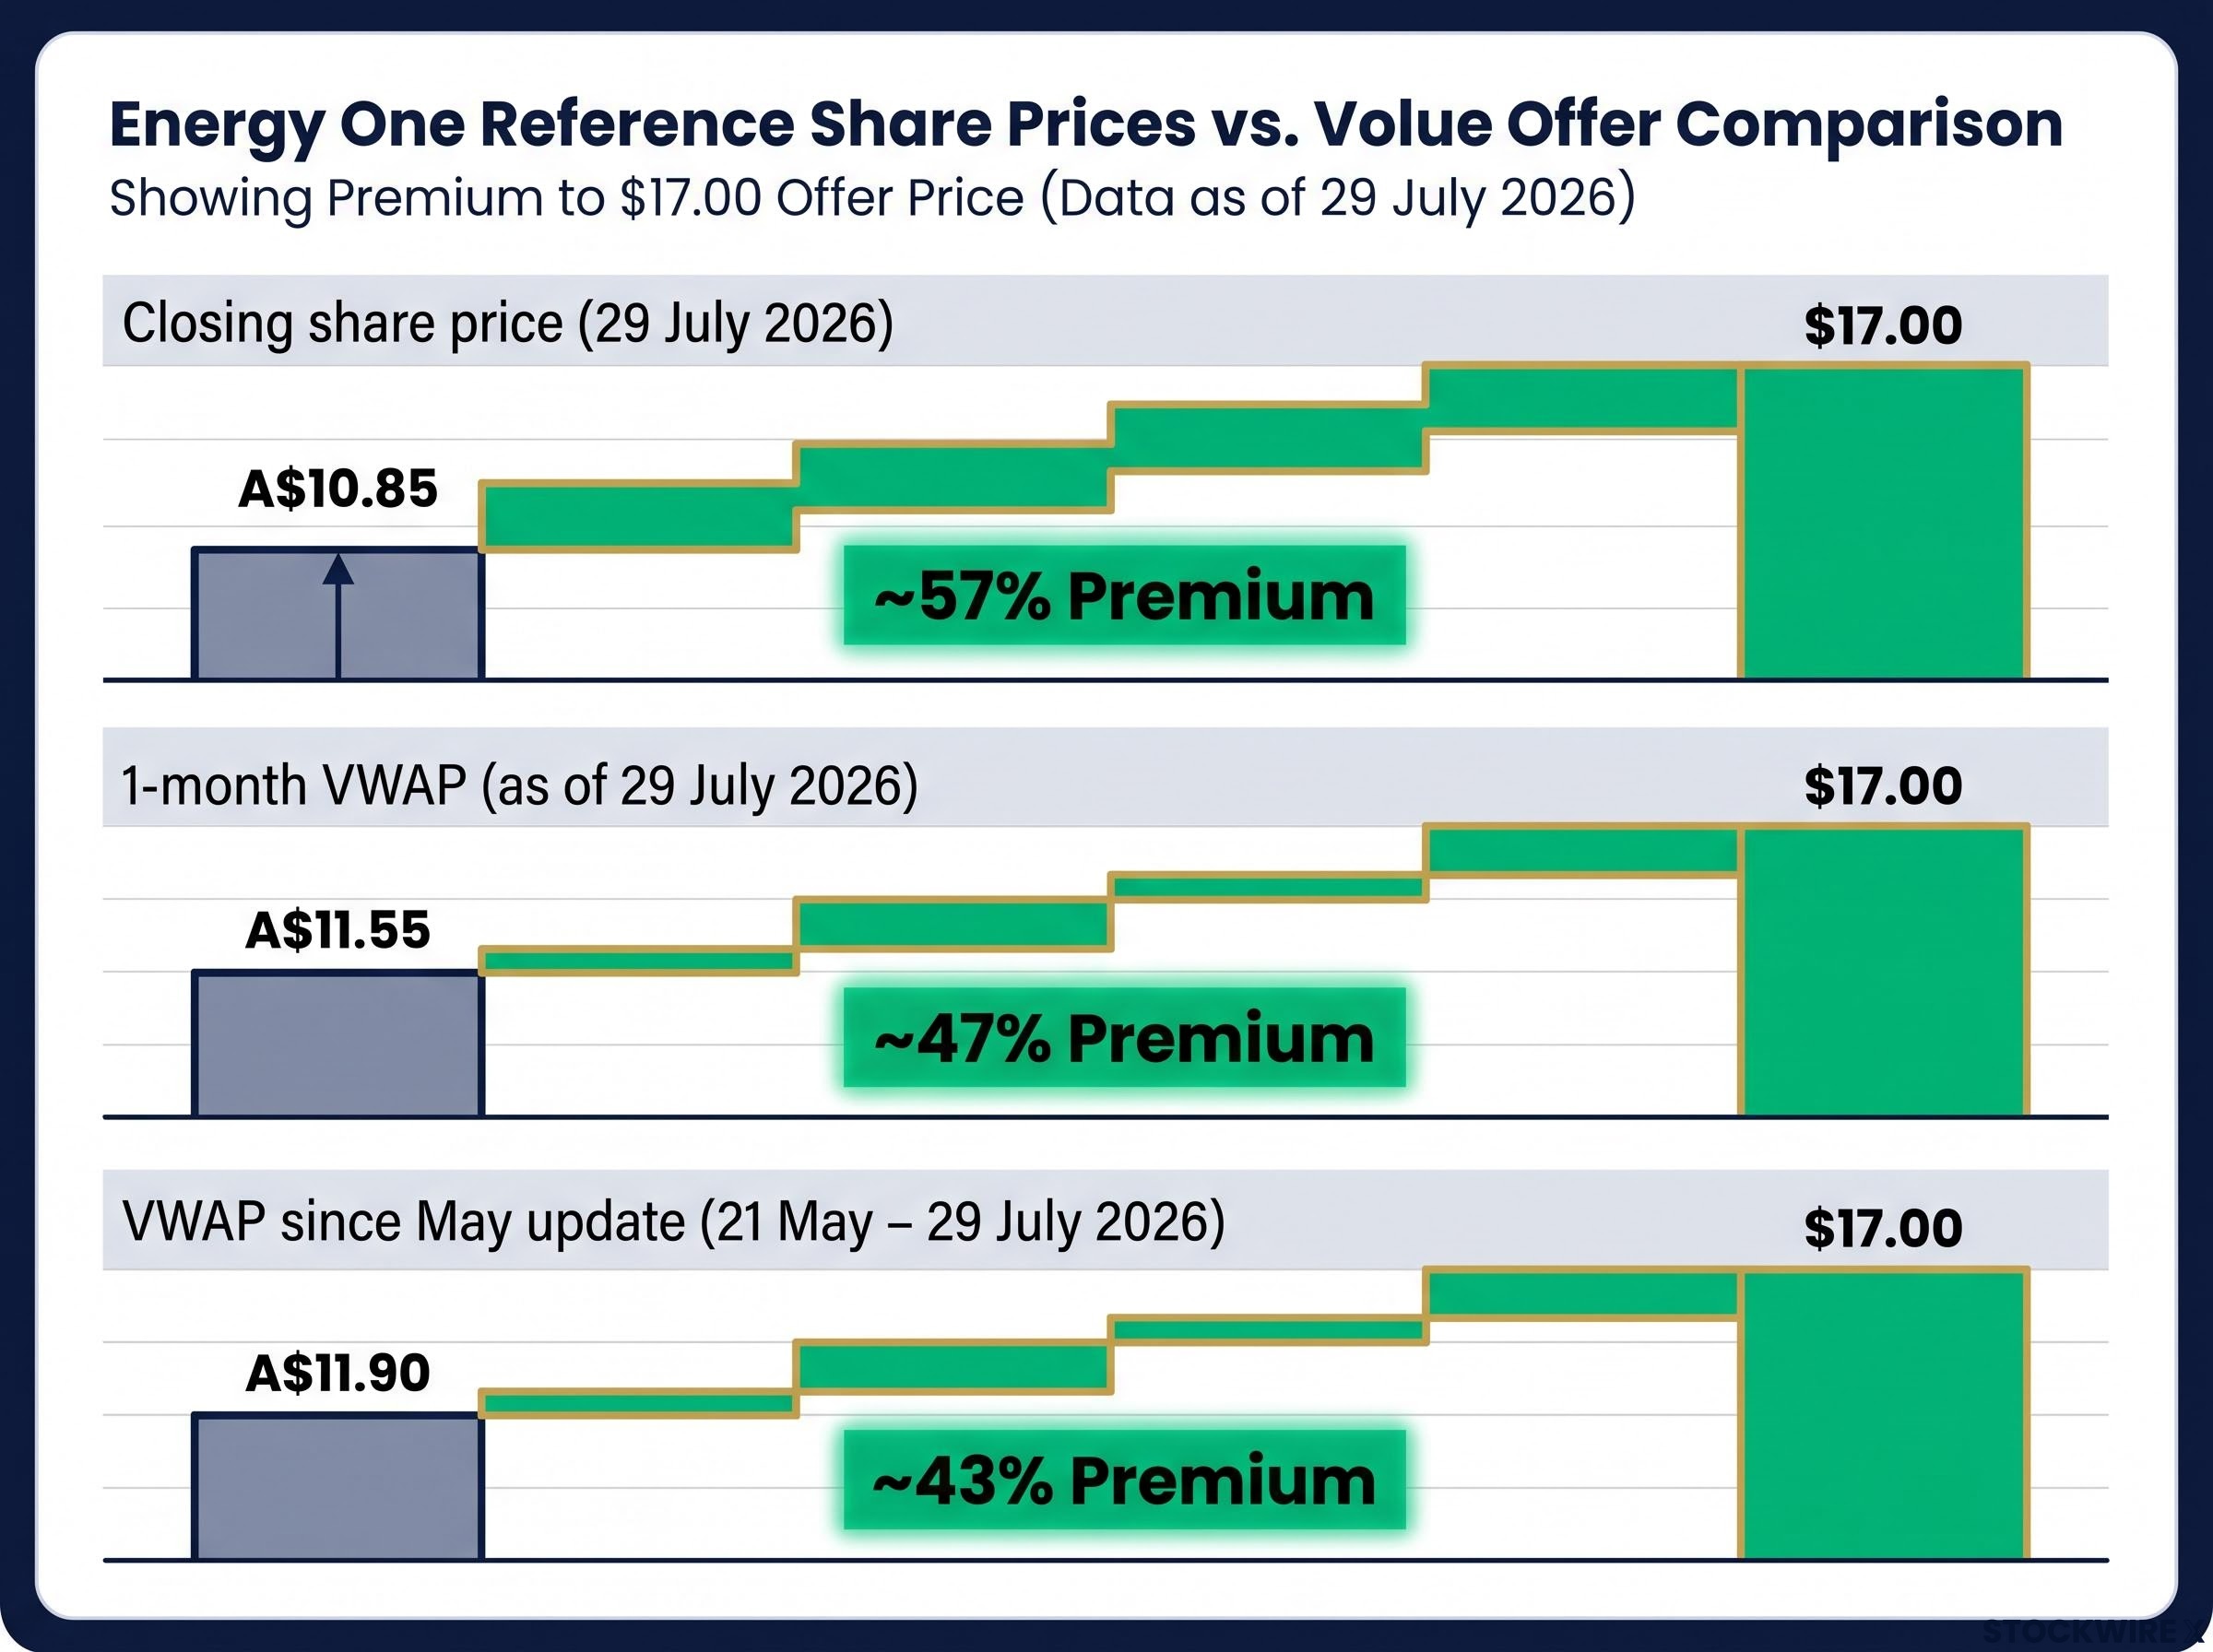
| Reference Metric | Reference Price | $17.00 Premium (Volue’s claim) | Source Date |
|---|---|---|---|
| Closing share price | A$10.85 | ~57% | 29 July 2026 |
| 1-month VWAP | A$11.55 | ~47% | as of 29 July 2026 |
| VWAP since May update | A$11.90 | ~43% | 21 May – 29 July 2026 |
Despite these premium claims, the Board declined to engage. The company also noted that a number of Energy One’s directors are meaningful shareholders, context relevant to why the proposal’s exclusivity and unanimous-recommendation conditions carry weight.
Why the board said no
The Energy One Board set out several grounds for its unanimous rejection of the proposal.
-
The proposal undervalues Energy One in the context of a change-of-control transaction.
-
It presents execution risk, including satisfactory completion of due diligence with access to management.
-
It faces regulatory hurdles, requiring FIRB approval and potentially antitrust approvals.
-
It carries onerous conditions, requiring exclusivity and the unanimous recommendation of the Board, with each director committing to vote all of their shares in favour.
The Board reinforced its confidence in the company’s standalone trajectory, describing Energy One as one of the world’s leading energy trading software and service suppliers, delivering strong top line and earnings growth, and margin expansion as it scales in Australia and Europe.
Energy One Board
“The Energy One Board considers that the revised indicative proposal is opportunistic, and does not reflect Energy One’s position as one of the world’s leading energy trading software and service suppliers. Energy One continues to deliver strong top line and earnings growth, and margin expansion as it scales in Australia and Europe. The Energy One Board is strongly confident that the management team will continue to deliver superior shareholder value when compared to the proposal from Volue AS.”
Understanding a scheme of arrangement (and why this bid is only step one)
For investors unfamiliar with takeover mechanics, understanding the structure of this approach clarifies why the rejection is material.
A non-binding, indicative, conditional proposal is not a firm offer. It carries no obligation to complete and remains subject to a series of conditions. In this instance, Volue has expressed intent and put a price on the table, but no binding commitment exists.
A scheme of arrangement is a board-recommended, court-approved method of acquisition. It requires shareholders to vote in favour at specified thresholds, and it depends on the target board recommending the deal. This differs from a hostile takeover under section 631 of the Corporations Act 2001 (Cth). Volue’s press release explicitly states that its proposal is not, and cannot be considered to be, a notification of an intention to make a takeover offer under section 631.
Because Volue is a foreign acquirer, the deal would also require regulatory clearances, including from the Foreign Investment Review Board (FIRB) and potentially antitrust approvals.
Volue’s proposal remains subject to the following conditions:
-
Completion of satisfactory confirmatory due diligence
-
A unanimous recommendation from the Energy One Board (or a committee of directors formed to consider the proposal)
-
Any regulatory or government approvals required, including from FIRB
-
Execution of a confidentiality, process and exclusivity deed
-
Final approval of the Volue Board
Without board recommendation and satisfied conditions, no transaction can proceed. This is precisely why the Board’s rejection is significant.
Who is Volue — and why it wants Energy One
Volue describes itself as a global leader in electrification technology, delivering an integrated platform spanning the full energy lifecycle from data and forecasting to trading, asset optimisation and grid management. The company reports more than 800 employees serving customers in more than 40 countries, and is headquartered in Oslo, Norway.
Volue is backed by a long-term investor group comprising Advent International, TA Associates, Generation Investment Management and Arendals Fossekompani.
In its press release, Volue outlined the strategic logic behind the approach. The company stated its ambition to build the world’s leading AI-enabled energy data and software platform, supporting sophisticated power producers and traders across forecasting, trading, optimisation, scheduling, settlement and market operations.
Volue said it holds deep admiration for Energy One’s positions in scheduling and nomination, its established ETRM franchise, and its market operations in Europe and Australia.
Volue AS
“Volue sees a rare opportunity to combine two highly complementary businesses into a global leader.”
What it means for shareholders and what happens next
Energy One shareholders do not need to take any action in response to the proposal at this stage. The company has stated it will keep shareholders updated in accordance with its continuous disclosure obligations.
The Board pointed to its own growth path as the standalone alternative. As previously flagged in its May 2026 update, Energy One continues to evaluate acquisition opportunities to increase scale, market position and customer offering in key markets, complementing its organic growth in line with its disciplined inorganic growth strategy.
On advisers, Lazard Australia is acting as financial adviser and Gilbert + Tobin as legal adviser to Energy One. Volue has retained Rothschild & Co as financial adviser and Clifford Chance as legal adviser.
The situation remains unresolved. Two possible catalysts lie ahead: a sweetened or renewed bid from Volue, or continued organic and inorganic execution by Energy One’s management team.
Key points for shareholders to watch include:
-
No action required by shareholders at this time
-
The Board continues its standalone growth strategy, combining organic growth with disciplined M&A
-
Further updates will follow via continuous disclosure
-
Volue has signalled willingness to engage “constructively and expeditiously”
With the Board firmly backing its standalone strategy and Volue signalling appetite to progress, the coming period will test whether the Norwegian suitor returns with an improved proposal or whether Energy One’s management delivers on its own growth ambitions.
Don’t Miss the Next ASX Tech Takeover Target
Big News Blast delivers FREE breaking ASX tech news directly to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ subscribers staying ahead of market-moving announcements before the broader market reacts. Click the “Free Alerts” button at StockWire X to start receiving alerts today.