Cleveland Fed President Beth Hammack said on Monday that the neutral rate is probably higher than most people assume, and that the Federal Reserve should apply more restraint to bring inflation back under control. Markets responded within hours.
The US dollar firmed against every major currency. Gold slipped toward $4,170, and US spot Bitcoin exchange-traded funds (ETFs) were already coming off a week of $681.10 million in net outflows.
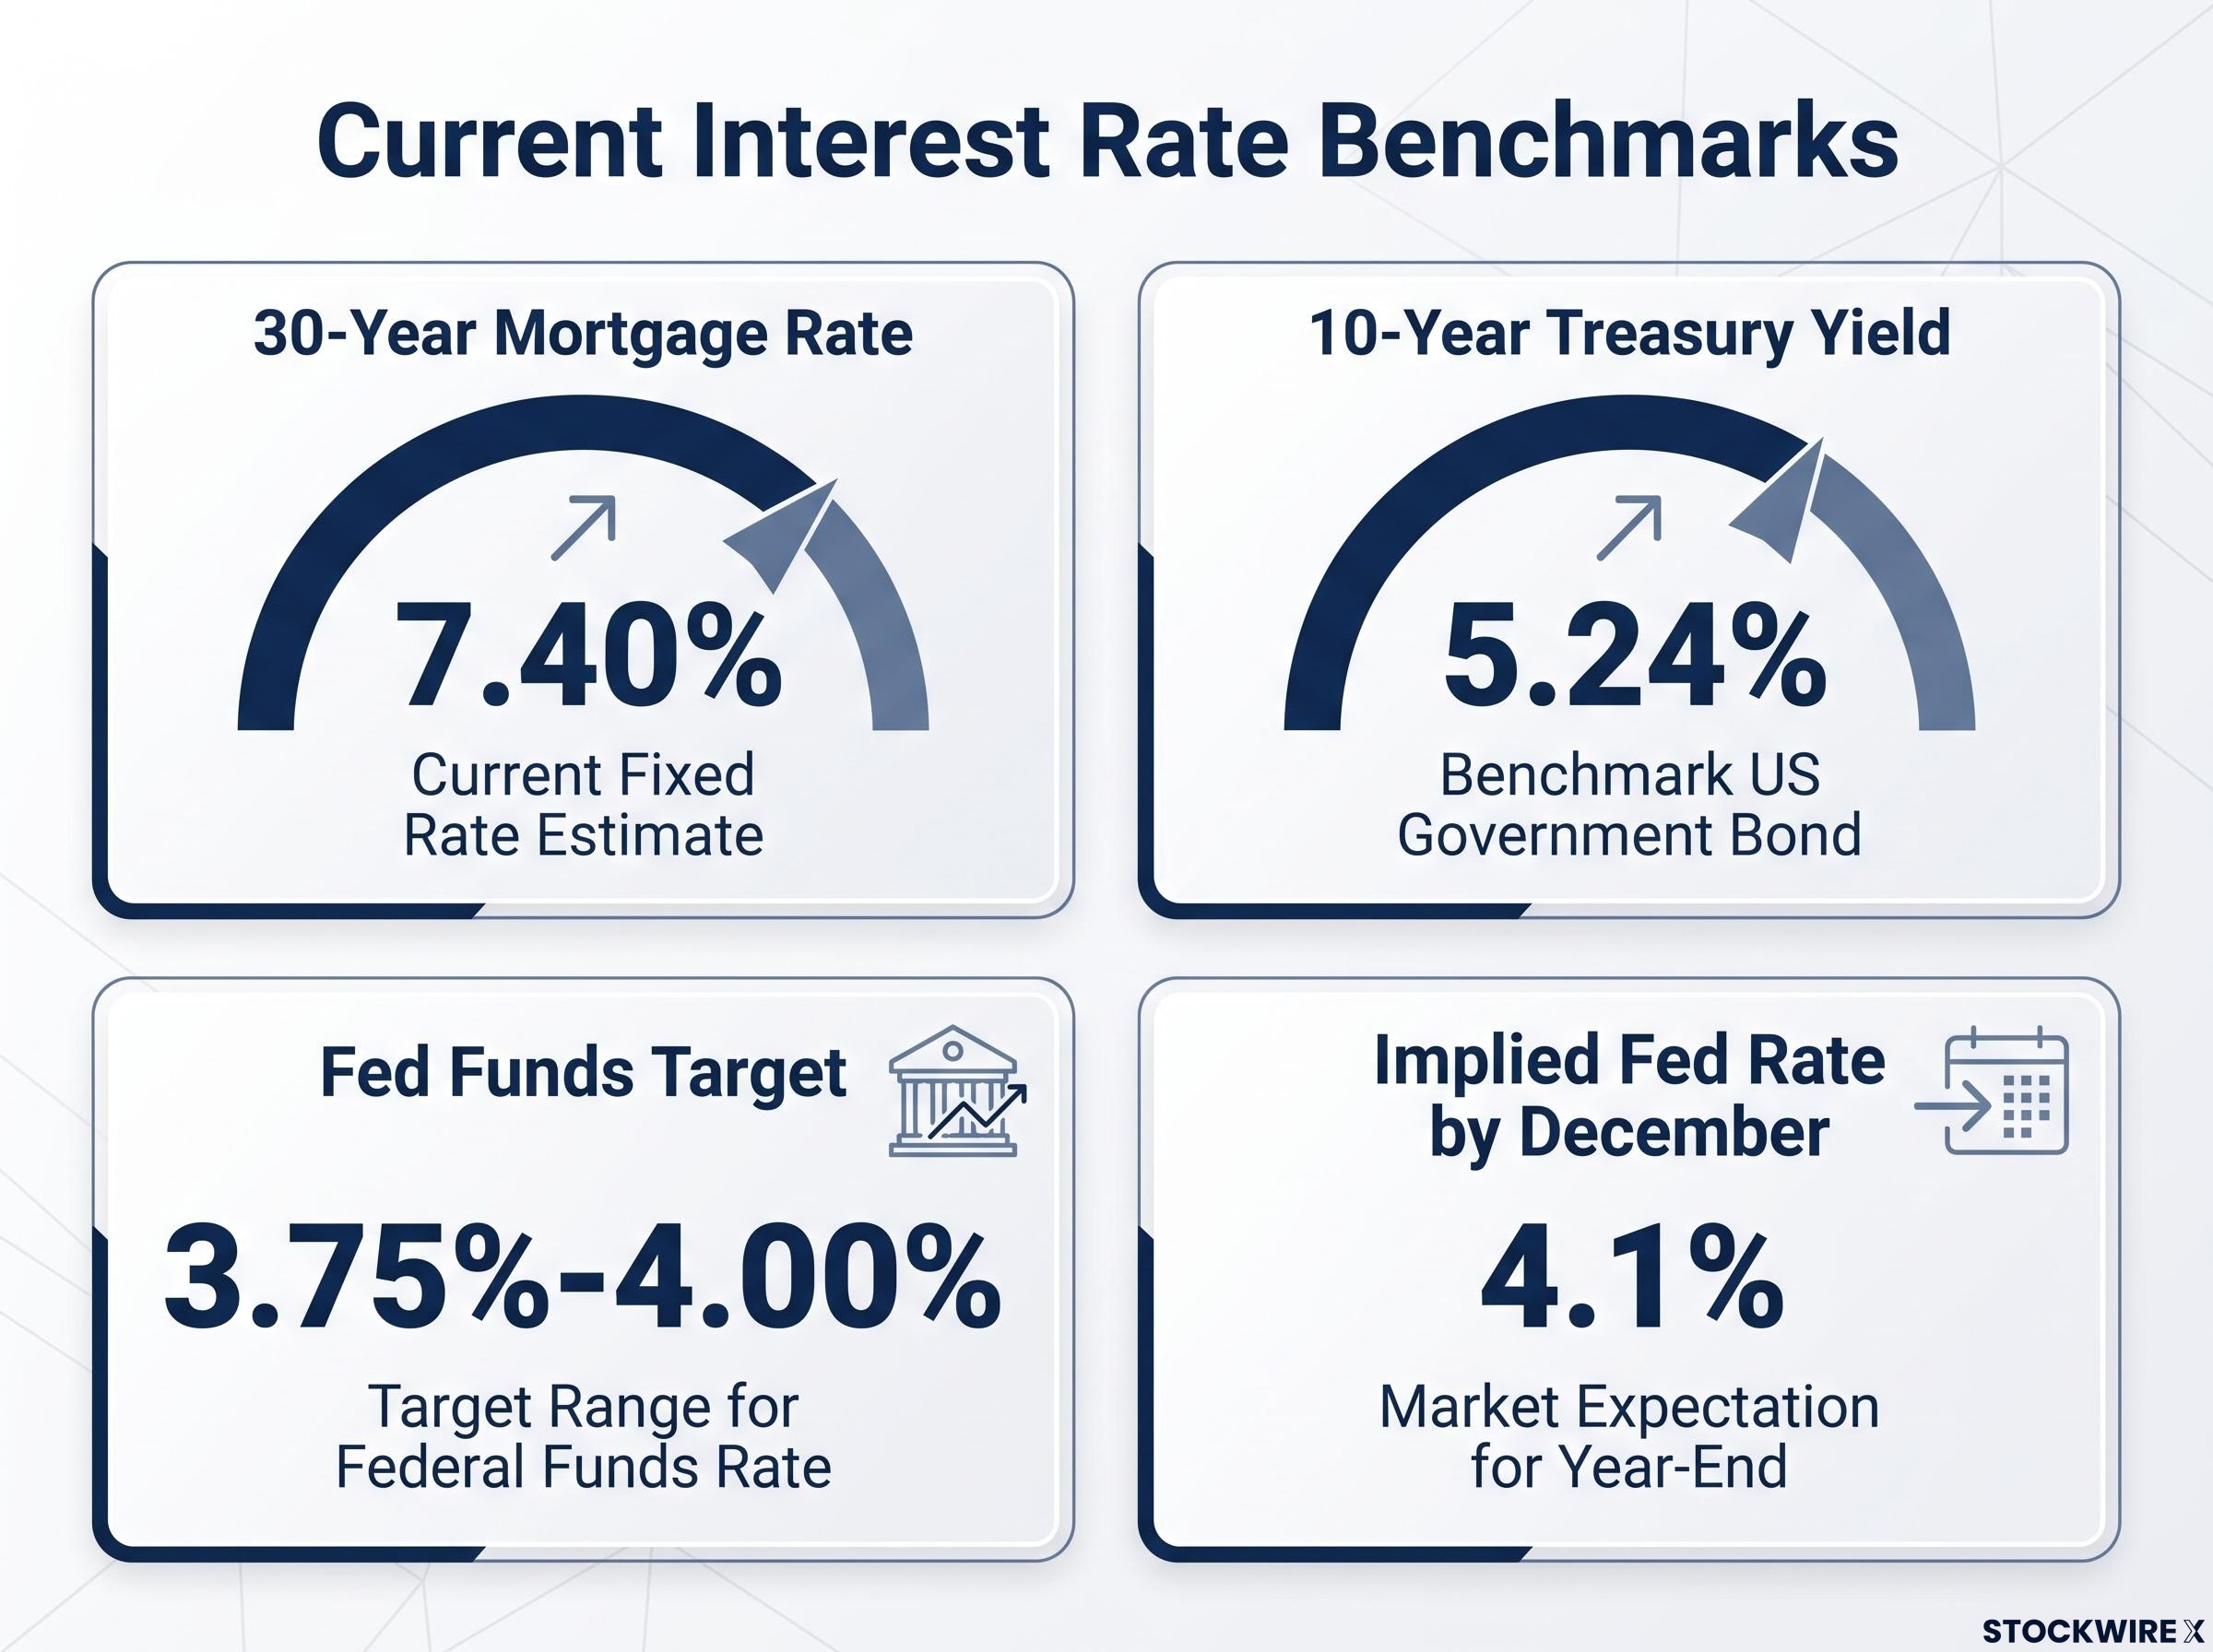
The fed funds target now sits at 3.75%-4.00% after the September hike, and the 30-year mortgage rate has climbed to 7.40%. If the neutral benchmark has moved up, today’s rates are squeezing the economy less than they appear to.
Here is what her view means for what you pay to borrow and for the assets you may hold.
Why would a higher neutral rate mean the Fed isn’t as tight as it looks?
Hammack made her case to the National Association for Business Economics in Cleveland. Her argument rests on one benchmark.
The neutral rate is the policy interest rate that neither speeds up nor slows down the economy. Nobody can observe it directly. Officials estimate it from models and data, which is why their estimates differ.
Hammack on neutral The Cleveland Fed President said neutral is hard to pin down but likely sits higher than commonly assumed. Her own projection is among the higher ones on the Federal Open Market Committee (FOMC). Where possible, she favours smaller adjustments made “relatively quickly”.
Her estimate sits above the committee’s. The Fed’s September Summary of Economic Projections (SEP) put the median longer-run rate at 3.2%, up from 3.1% in June. Hammack’s individual estimate was not identified, but she places herself above that median.
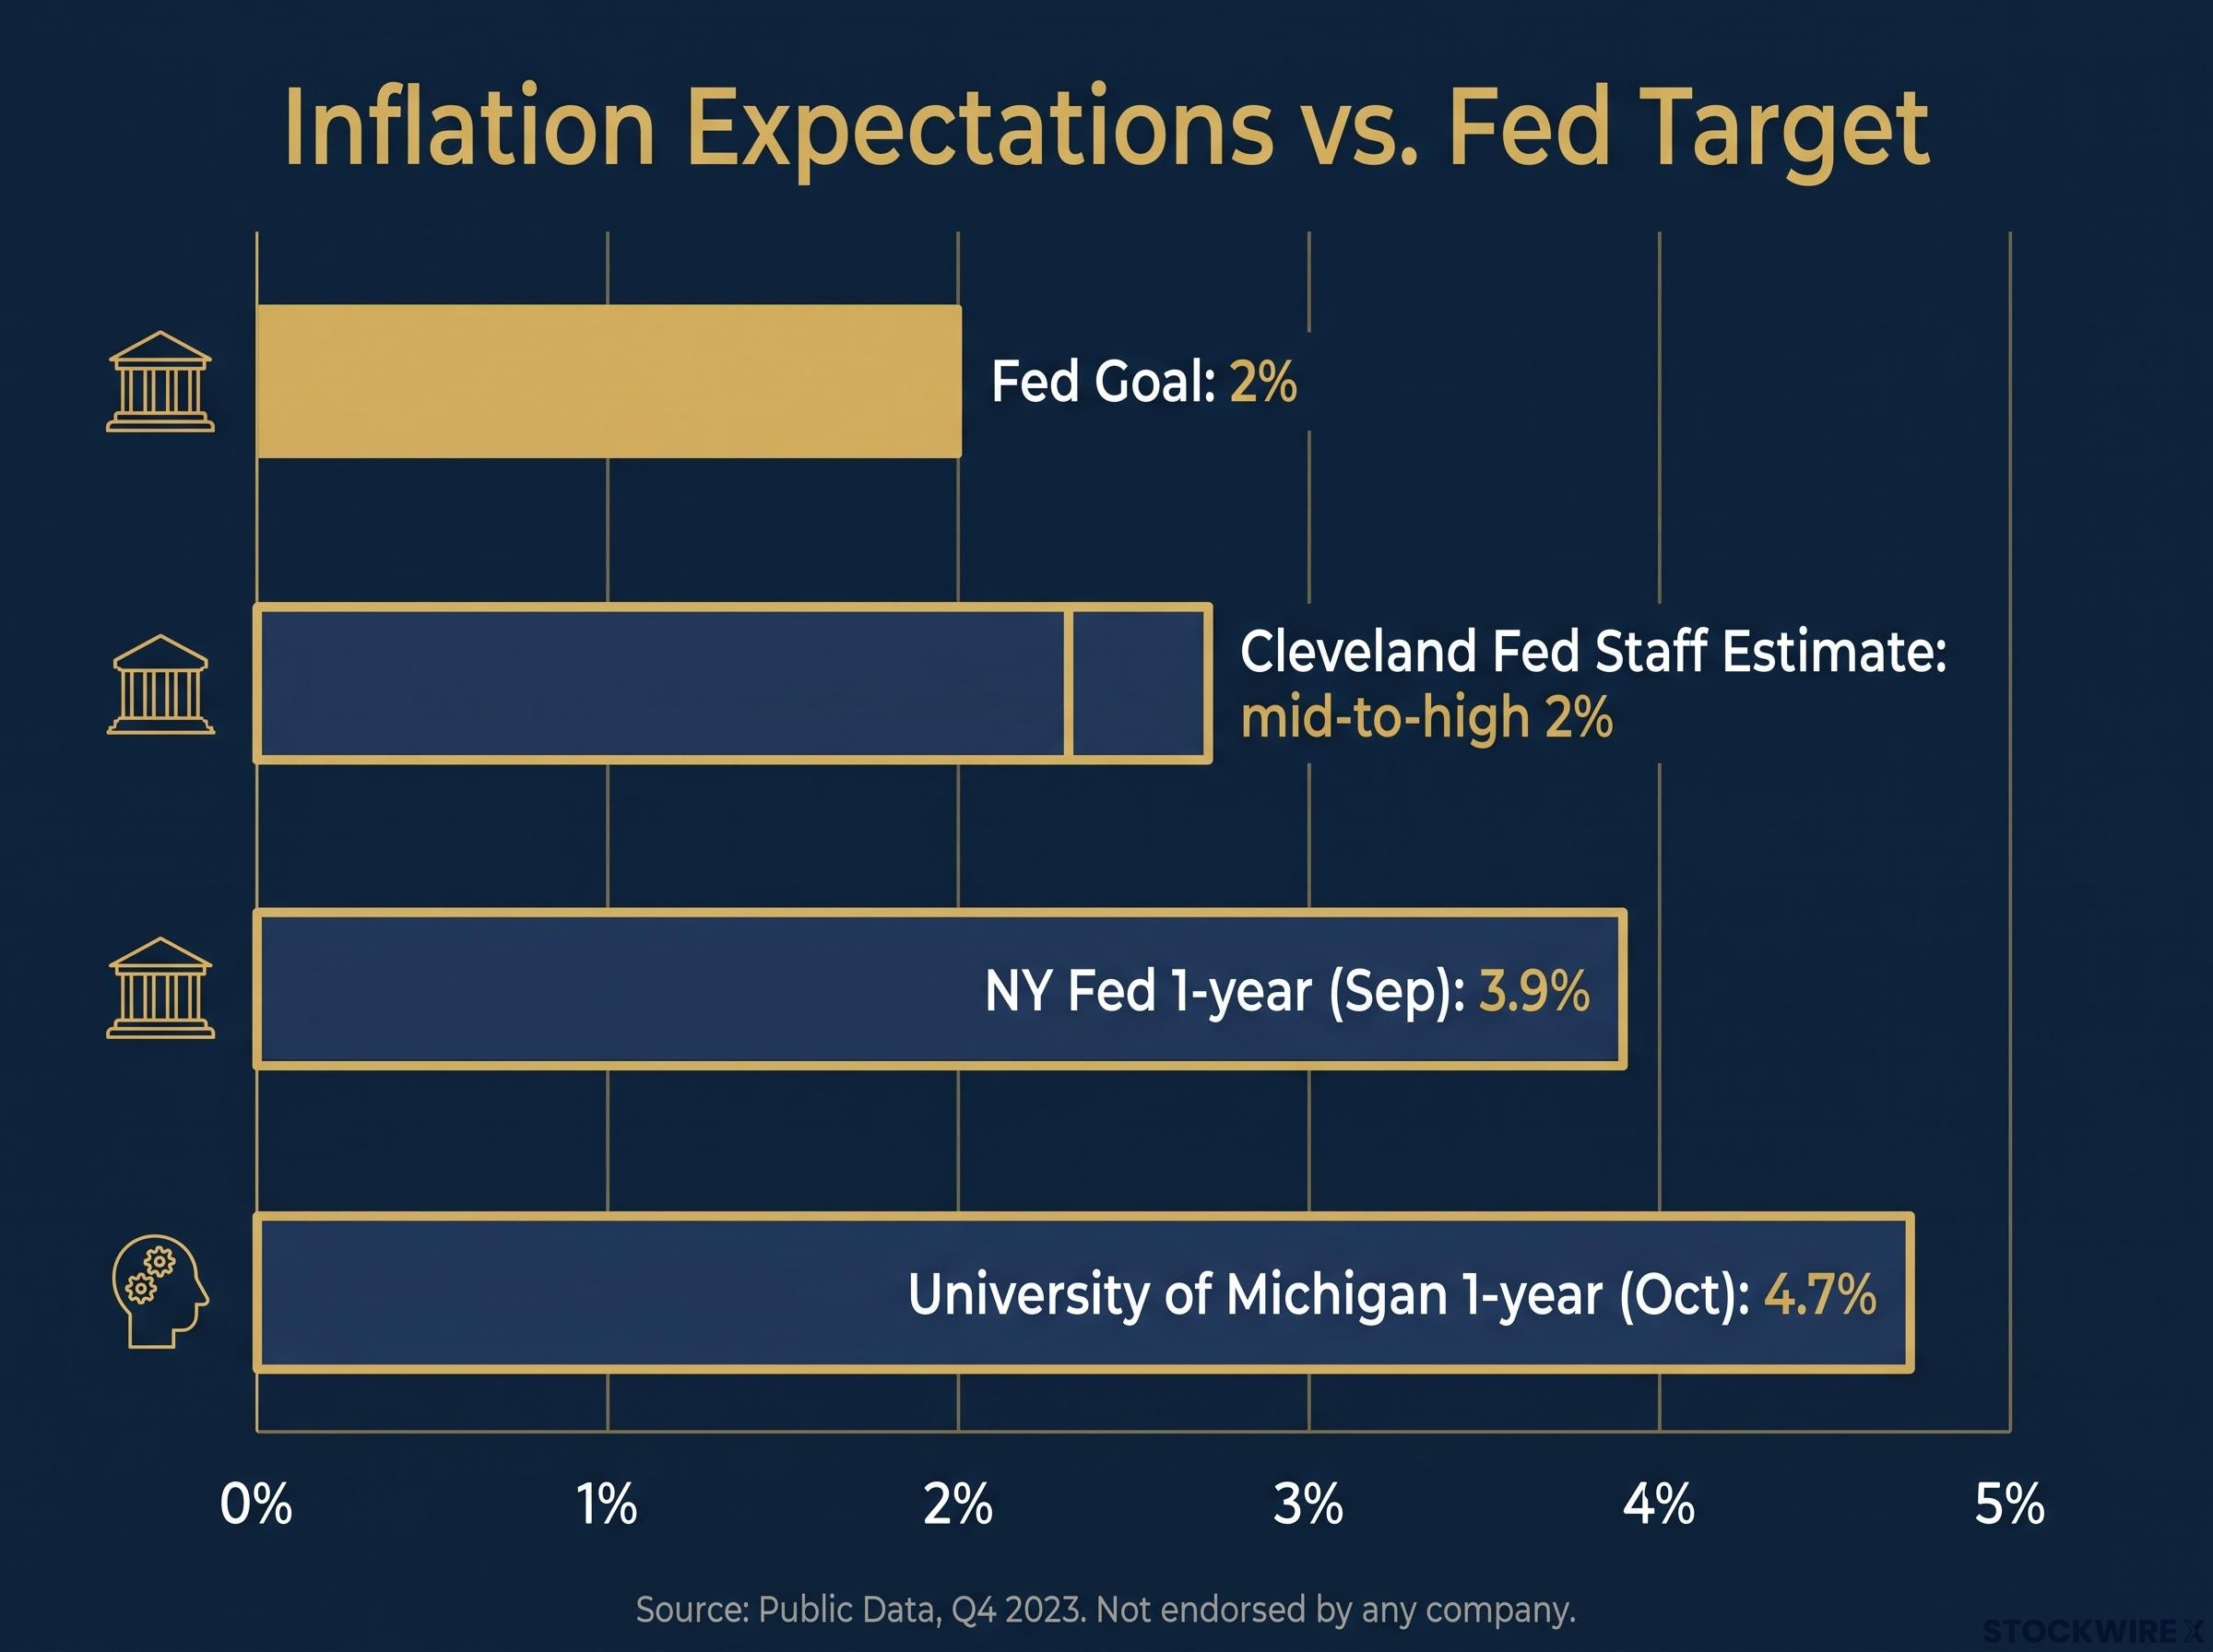
Her concern is inflation. Her staff estimate underlying inflation in the mid-to-high 2% range, still above the Fed’s 2% goal. The Fed’s dual mandate also covers maximum employment, and she said she does not want to put jobs at risk. She also said she is hearing early warning signs that inflation expectations could become a problem:
- New York Fed 1-year expectations: 3.9% in September, up 0.3 points
- University of Michigan 1-year expectations: 4.7% (preliminary October)
The short-horizon jump matters less than the steady five-year inflation reading, which is the longer-term gauge officials watch most closely when judging whether expectations are genuinely de-anchoring.
Economists disagree about why neutral may have risen. Brookings and the Institute of International Finance (IIF) argue that AI investment and government deficits could push it higher. The San Francisco Fed found the increase is not cleanly explained by either factor.
The practical point for you is this. If neutral is higher, the rate you assumed was squeezing the economy may be doing much less. That is why Hammack sees room for further hikes.
How did the dollar, gold and Bitcoin react to the Hammack comments?
The dollar moved first. It gained across the board, with its biggest rise against the Swiss franc, and USD/JPY held above 158.00.
Gold went the other way. Bullion pays no interest, so higher Treasury yields and a stronger dollar made it less attractive. Bets on at least one more hike added to the pressure.
| Asset | Move | Stated driver |
|---|---|---|
| US dollar | +0.54% vs CHF, +0.50% vs NZD, +0.38% vs EUR, +0.37% vs AUD, +0.22% vs GBP and JPY, +0.21% vs CAD | Expectations of further Fed hikes |
| Gold | Around $4,170-$4,176, off an intraday high near $4,217 | Higher yields, firmer dollar, hike bets |
| Bitcoin | Near $83,600 after a 3.1% weekly fall | Risk-off mood, weaker ETF demand |
| US spot Bitcoin ETFs | $681.10M net outflows last week | Ended a three-week inflow streak |
Rate pricing points the same way. Reuters reported that investors expect a hold at the 27-28 October meeting. The Fed’s minutes, however, show most officials see another hike by year-end, and the SEP median implies 4.1% by December.
Officials’ projections and market expectations often diverge, and the gap between the dot plot and futures pricing shows how differently the committee and investors read the same inflation data.
Two caveats limit what you can read into one day. Trading was thin because of public holidays in Japan and the US. A single week of ETF outflows also does not make a trend.
Even so, markets are pricing a Fed that keeps tightening into year-end. If you hold gold or crypto, your exposure is to rising real yields and a stronger dollar, not just to one speech.
What does tighter policy mean for mortgages, borrowers and the next Fed meeting?
Mortgage rates follow long-term Treasury yields more closely than the Fed’s overnight rate. Freddie Mac’s 30-year average rose to 7.40% from 7.28%, with the 10-year yield near 5.24%. That increase reflects a bond selloff and heavy Treasury issuance as well as Fed policy.
Hammack called current Treasury rates modest by historical standards. She said a return to 3% mortgages would likely signal that something had gone wrong in the economy.
For households, the costs spread beyond home loans:
- Credit cards and auto loans: borrowing costs rise
- Home equity lines of credit (HELOCs) and variable-rate debt: repayments adjust upward
- Fixed-rate mortgage holders: partly insulated
Fixed-rate holders are partly insulated, but the mortgage lock-in effect keeps many of them from selling or borrowing against equity, which thins housing supply and spreads the cost of high rates beyond new buyers.
Hammack said feedback from low-income workers has shifted from trading down to juggling which bills to pay. She added that higher rates probably would not deter hyperscalers, the largest cloud and AI spenders, though firms in other industries could feel the pressure.
Fast or gradual: where Fed officials split
The hawkish camp worries that inflation expectations could become embedded, as they did in the 1970s. The gradual camp worries about overtightening, because policy works with a delay and could hurt hiring, housing and consumer spending after inflation has already cooled. The 2022-2023 tightening showed the risks on both sides.
- Hammack: act early with smaller moves; dissented in favour of a July hike
- September FOMC majority: another hike likely by year-end, depending on data
- Jerome Powell (January): policy was within a broad range of neutral estimates
- Anna Paulson, Philadelphia Fed: more concerned about labour market weakness
Even if the Fed pauses on 27-28 October, a higher neutral rate means you should not plan around cheaper borrowing returning soon.
What to watch after Hammack’s neutral-rate signal
Hammack’s message is that policy may be closer to neutral than it looks. If so, how far the Fed goes depends on whether inflation expectations stay contained.
Three things will show which way that goes:
- The outcome of the 27-28 October FOMC meeting and any change in guidance
- The next New York Fed and University of Michigan inflation-expectations readings
- The direction of the 10-year Treasury yield and the Freddie Mac mortgage rate
These statements are speculative and subject to change based on market developments, and the Fed’s path will depend on incoming data.
Readers interested in why long-end yields keep climbing can read our detailed coverage of the Fed credibility gap, which explains the yield curve steepening.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.