BofA Securities has ranked STMicroelectronics, Infineon, Tower Semiconductor and Nordic Semiconductor ahead of Melexis, which it keeps at Underperform, as the quarter’s European semiconductor earnings round gets under way. The view rests on one pricing assumption. Large original equipment manufacturers (OEMs, the big companies that buy chips to build cars, servers and devices) are expected to pay prices flat to up 5%, against the traditional 1%-5% annual decline.
That improvement is already largely built into forecasts. The question for each company is no longer whether results beat, but whether they beat by enough to move the shares.
The note was reported on 23 October, after Nordic had already released its third-quarter numbers. Melexis reports on 28 October.
Here is what the market is already pricing in for each name, and the specific numbers that would count as a genuine positive surprise.
What does the market already expect from STMicro, Infineon and Tower?
BofA expects modest beats and raised outlooks from all three companies. Its view is that gross margin (the share of revenue left after direct production costs) has little room to improve, while revenue should edge up slightly on demand from data centres and AI, autos and industrial customers.
That is a high bar. Expectations of a beat already sit in the share prices, so the useful detail is where BofA’s own numbers run ahead of the crowd.
| Company | Key expectation | BofA figure | Latest reported quarter |
|---|---|---|---|
| STMicroelectronics | Higher data-centre guide, gross margin above 40% next year | About $3bn data-centre revenue, CY2027 | Q2: $3.49bn revenue, 34.8% gross margin |
| Infineon | AI power revenue of €3.5bn-€4bn | €4.1bn AI and server-CPU power, FY2027E | Q3: €4.172bn revenue, 40.8% gross margin |
| Tower Semiconductor | Modest beat and raise | No company-specific figure given | Q2: $460m revenue, 30% gross margin |
STMicro: optical and the 40% margin question
ST’s AI story runs through optical connectivity, the components that move data between servers using light. BofA thinks the data-centre guide could reach about $3bn for CY2027, above management’s targets at the Citi conference on 9 September: more than $1bn in 2026 and well above $2bn in 2027.
Margin is the tougher hurdle. Per BofA, investors want reassurance that gross margin can rise past 40% next year, whether from a richer product mix (BofA puts optical margins above 50%) or from firmer pricing with large OEMs. ST reported 34.8% for Q2 on 23 July and guided Q3 to $3.70bn at about 37.0%.
Infineon: AI power versus pricing limits
Infineon’s AI exposure comes from supplying power content for servers, not from accelerator chips themselves. BofA’s €4.1bn estimate sits above the €3.5bn-€4bn range it believes the market expects.
Pricing is messier. Autos make up about 75% of the ATV division (Infineon’s automotive unit) and should pass through 5%-10% foundry inflation. An IGBT glut (IGBTs are power switches used in vehicles and industrial equipment) and the politically delicate subsidies behind the Dresden fab may hold tier-1 price increases to roughly 5%. Q4 revenue is guided to about €4.7bn.
Tower: grouped, but thinly detailed
BofA places Tower with the beat-and-raise names but offers no company-specific thesis. Tower guided Q3 to about $520m, with results due in early November.
If the market already expects roughly $3bn from ST and €3.5bn-€4bn from Infineon, a result that simply confirms those numbers is unlikely to lift the shares. Watch for guidance above them.
Is the pricing shift real, and why does it matter more than the beats?
The pricing call carries more weight than any single revenue line. BofA’s view rests on three mechanisms:
- Foundry-cost pass-through: Infineon’s automotive business is expected to pass on 5%-10% in higher manufacturing costs.
- Large-OEM negotiations: pricing flat to up 5%, already largely in expectations.
- Power-semiconductor constraints: IGBT oversupply and Dresden subsidy sensitivity limit increases.
The pricing reset Large-OEM prices: flat to up 5%. Historical norm: a 1%-5% annual decline.
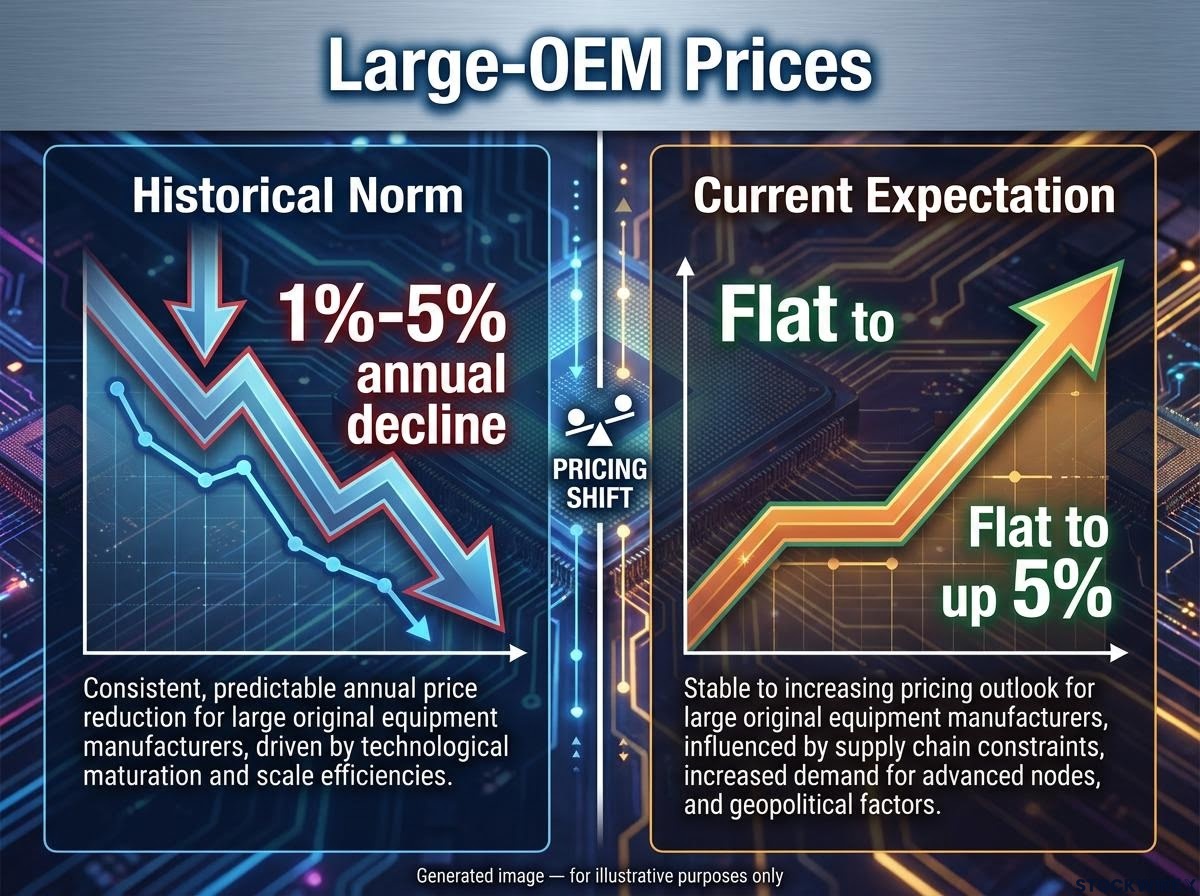
Part of the shift looks structural: AI demand, more cautious capacity building, and regionalised supply chains. Part is cyclical: recovery from the inventory downturn, foundry inflation and a temporary IGBT glut.
Separate industry commentary has pointed to 10%-25% increases from some automotive IGBT and silicon carbide suppliers during 2026. That figure is unconfirmed and should be read as supporting colour, not a market-wide measure.
Valuation adds a second caution. Morningstar warned in June and August that European AI-related chip valuations look demanding.
The exceptions matter: IGBTs, older power components and subsidised capacity sit outside the trend. For you, pricing commentary above the flat-to-5% range is the real signal on the calls. Anything inside it is already known.
Why does Nordic win favour while Melexis stays at Underperform?
The two companies sit at opposite ends of BofA’s ranking, and the gap comes down to earnings visibility and end-market exposure.
Nordic’s Buy rating rests on operating leverage and mix lifting EBITDA (earnings before interest, tax, depreciation and amortisation). Its Q3 revenue rose 32% year on year to $235m. BofA cites an EBITDA margin of 18.1%, up from 15.4% in Q2, while the company reported adjusted EBITDA of about $40m, or 16.9%-17%. The definitions likely differ, but both show clear improvement.
Melexis leans more heavily on global SAAR (the seasonally adjusted annual rate of vehicle sales) and vehicle production, both hit by weak China and Europe. According to ACEA, global car production fell 1% to 37.6m units in H1 2026, and China’s output dropped 5.8%, its first decline since 2020.
| Metric | Nordic Semiconductor | Melexis |
|---|---|---|
| Latest revenue | Q3: $235m | Q2: €217.1m |
| Gross margin | 52.8% | 40.5% |
| Guidance | Q4: $215m-$235m, margin above 50% | Q3: €220m-€225m; H2: €445m-€455m |
| BofA rating | Buy | Underperform |
Even good news has limits. Nordic’s share reaction to its strong quarter was described as muted, and a 15 October sell-off hit Infineon, Soitec and Aixtron. The key risks:
- Demanding valuations after the rally
- Doubts over how durable AI spending will prove
- IGBT oversupply
- Chinese competition and weak Chinese vehicle output
- A delayed auto recovery
Melexis is effectively a bet on an auto rebound that has not arrived, though it could gain disproportionately if one does. Nordic’s good news was visible before the print. Neither result tells you much without the expectations around it.
What a real surprise looks like this earnings season
Three outcomes would count as genuine positive surprises:
- Pricing commentary above the flat-to-5% large-OEM range
- An Infineon AI-power guide above €3.5bn-€4bn
- ST data-centre guidance materially above about $3bn
Melexis on 28 October will show whether auto demand is turning. Tower follows in early November. The primary BofA note was not accessible, so these figures rest on secondary reporting.
Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
—