Star Entertainment shares fell around 10% on Friday after the NSW Independent Casino Commission confirmed its Sydney casino licence would stay in suspension until 30 June 2027, keeping the company locked out of direct control of its flagship property. Healius moved the other way, jumping 5.5% on a binding $160 million deal to sell its Agilex Biolabs subsidiary.
The two moves sat at opposite ends of a session where the broader ASX 200 finished lower on Friday 25 September 2026. The index leaned down; individual names scattered in both directions.
That contrast is the story worth reading. When the market as a whole drifts lower, the stocks that break sharply from that direction are telling you something specific about each company’s standing.
Here is what actually drove the outliers, and what each move signals for the businesses behind them.
ElectroOptic Systems and Healius: what drove Friday’s standout gains
Start with the more dramatic chart. ElectroOptic Systems (EOS) added roughly 6% on the day, a modest number until you set it against the backdrop: the defence equipment maker surged more than 600% across the prior calendar year and is up around 20% year to date.
EOS operates in the defence space, including drone defence technology, and has ridden the tailwind of rising government defence spending. Friday’s gain was another leg on a re-rating that has been building for a long time, not a one-session pop.
Healius told a cleaner story, because there was a transaction behind it. The pathology and imaging group struck a binding agreement to sell wholly owned subsidiary Agilex Biolabs to a subsidiary of Novotech Health Holdings, a global contract research organisation backed by TPG-affiliated funds. A contract research organisation runs clinical trials and lab work on behalf of drug developers.
The terms are what moved the stock:
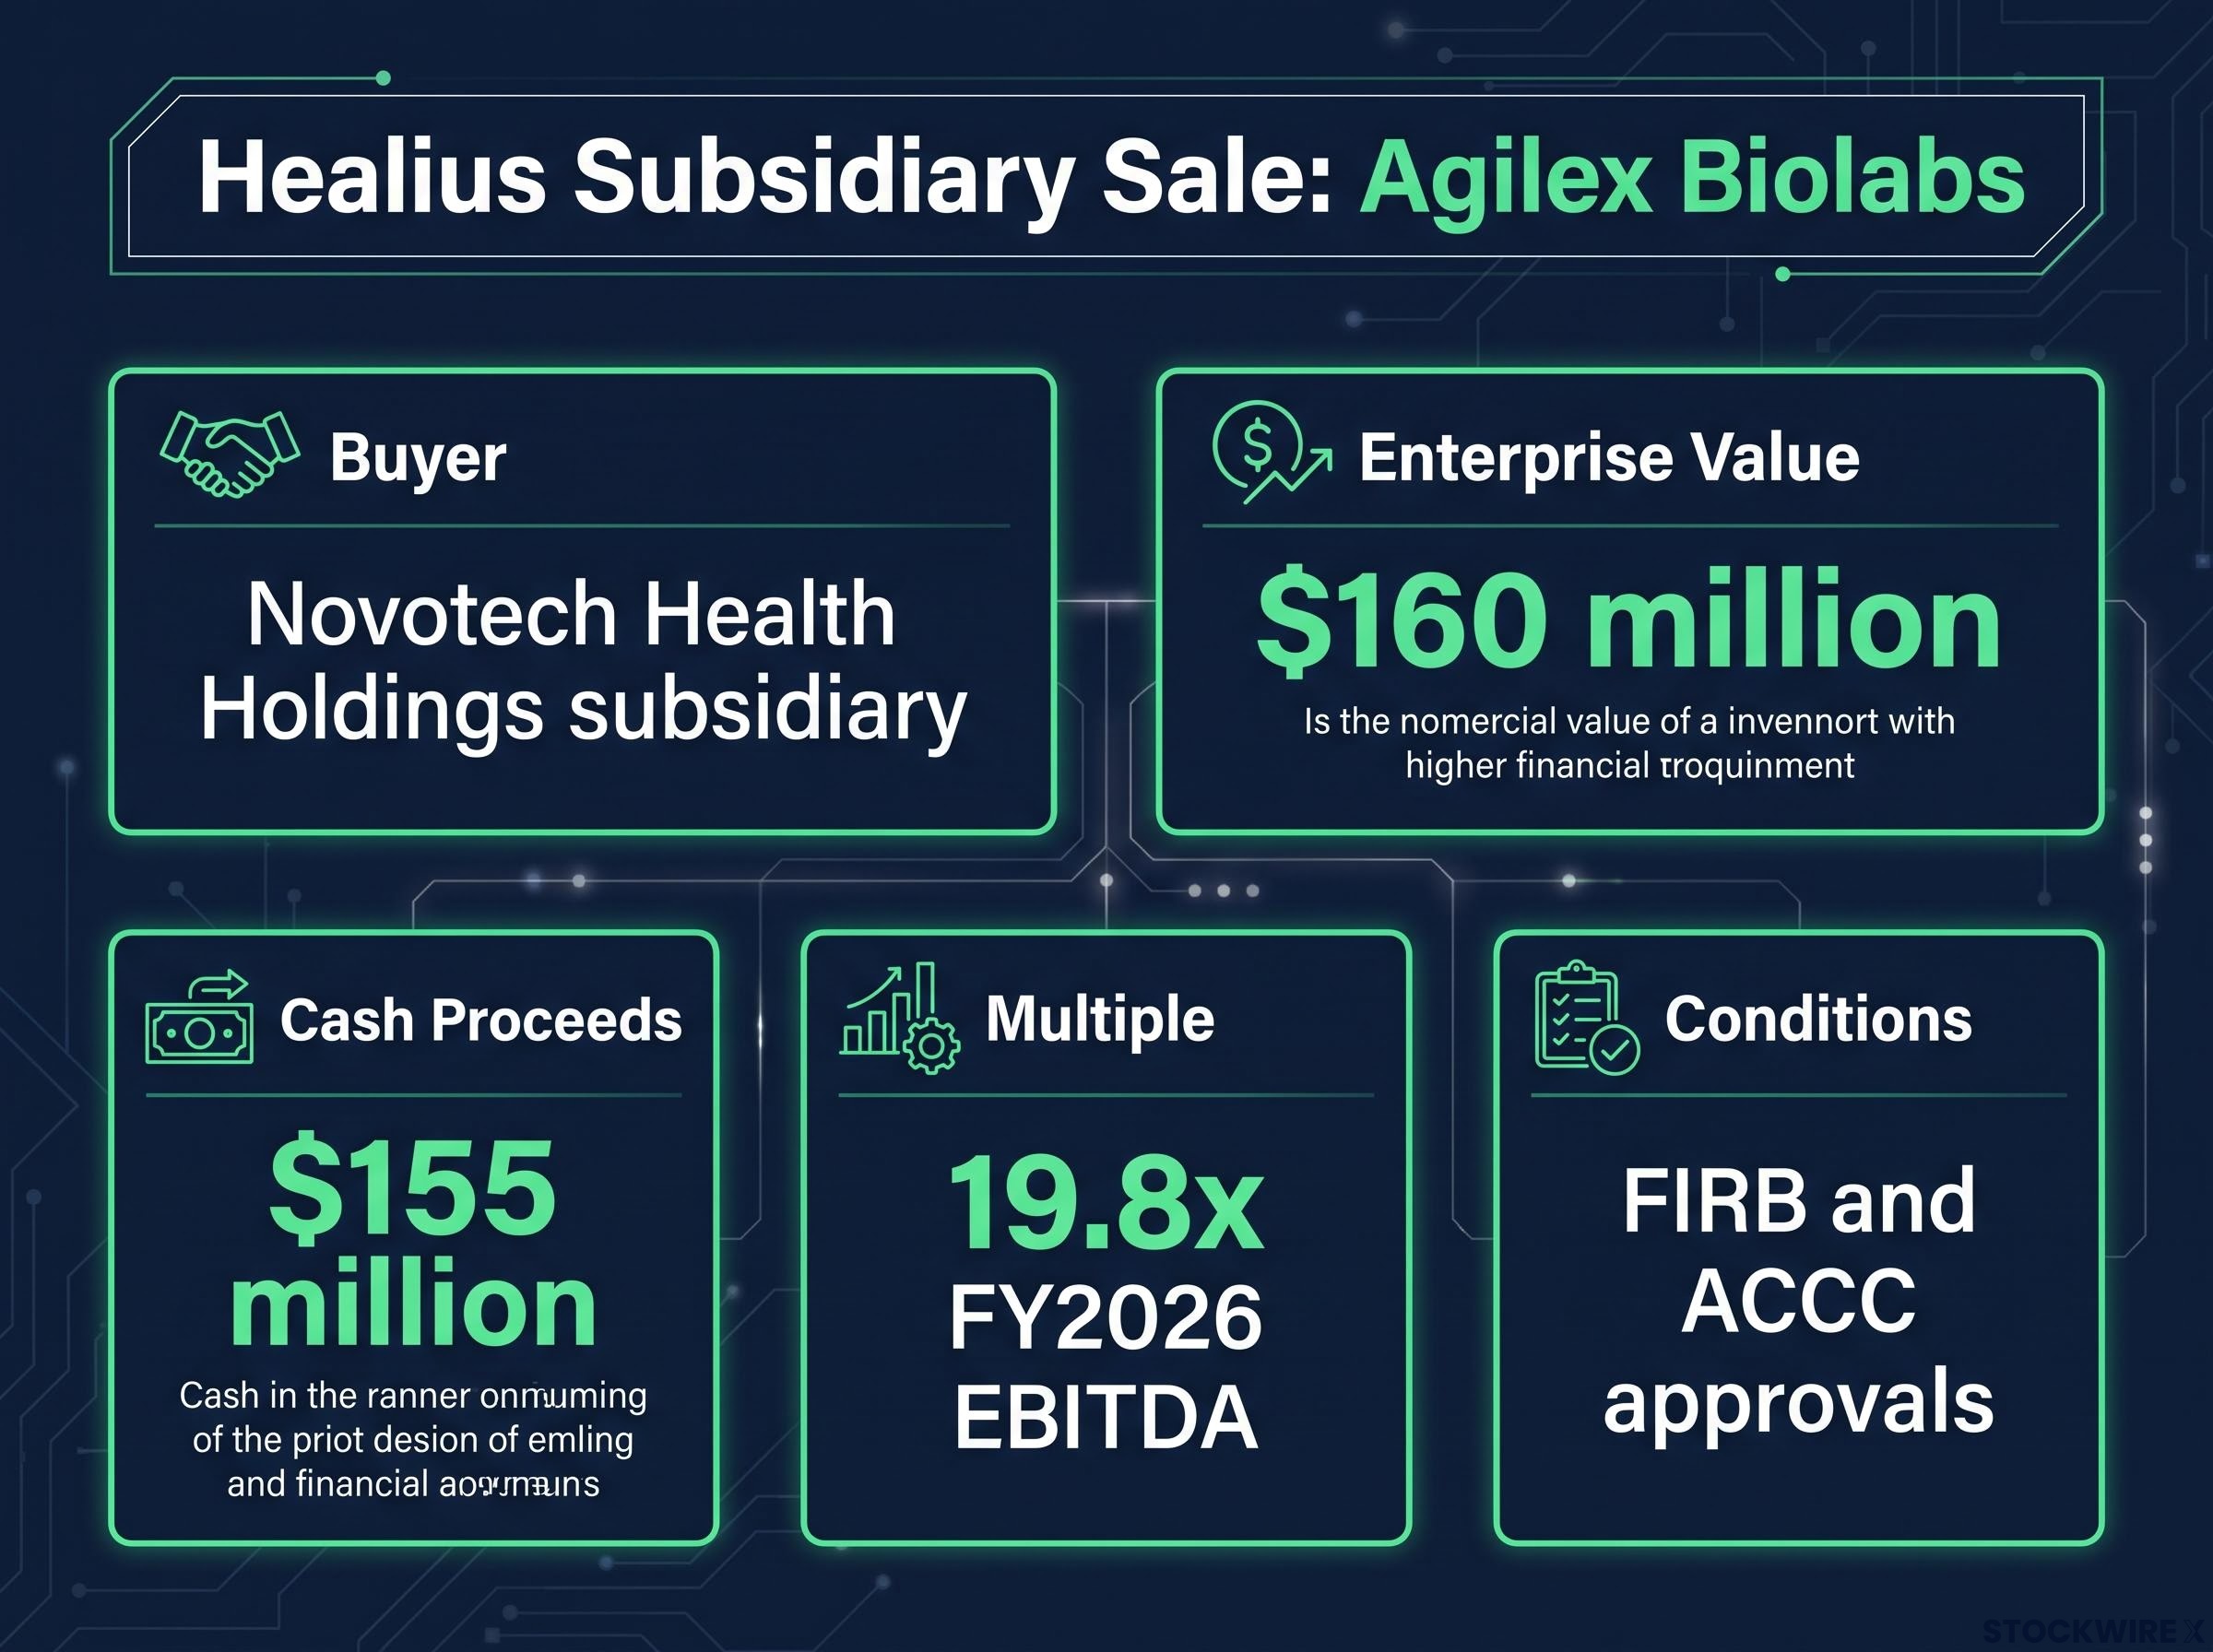
- Enterprise value of $160 million for Agilex Biolabs
- Cash proceeds of approximately $155 million expected after separation and transaction costs
- A multiple of 19.8x Agilex’s FY2026 EBITDA on a pre-AASB 16 basis
- No tax expected on the transaction
- Completion subject to Foreign Investment Review Board (FIRB) and Australian Competition and Consumer Commission (ACCC) approvals
- Core pathology and imaging operations unaffected
The multiple is the tell.
19.8x FY2026 EBITDA A high multiple on a non-core asset signals a sale made from strategic choice, not distress.
For anyone holding Healius, that number matters more than the headline price. Selling Agilex at nearly 20x earnings, with no tax leakage and around $155 million in clean cash coming in once conditions clear, tells you the company negotiated from strength rather than necessity. The proceeds give the balance sheet real flexibility, and management framed the deal as a refocus on core pathology and imaging rather than a fire sale.
Strategic divestments at strong multiples have been a recurring feature of the ASX in 2026: Maas Group secured $1.7 billion for its Construction Materials division earlier in the year, using proceeds to pivot toward digital infrastructure, a pattern that mirrors the logic behind Healius shedding Agilex to sharpen its pathology and imaging focus.
Two stocks, two very different reasons to climb on a red day. One rode a structural demand thesis; the other banked a concrete deal at a strong price.
Star Entertainment and NetWealth: regulatory and legal shocks hit hardest
The falls were sharper, and both came from outside the profit-and-loss statement.
Star Entertainment: still operating, still not in control
Star’s roughly 10% drop followed the NICC and the NSW government confirming that the appointed manager’s term would run a further nine months, out to 30 June 2027 unless ended earlier. In plain terms, Star still does not hold its own Sydney casino licence.
The Star Sydney remains open and continues to generate revenue. But the licence sits with NICC-appointed manager Nicholas Weeks, not with the company that owns the building.
This is not a new problem. It is a deepening one.
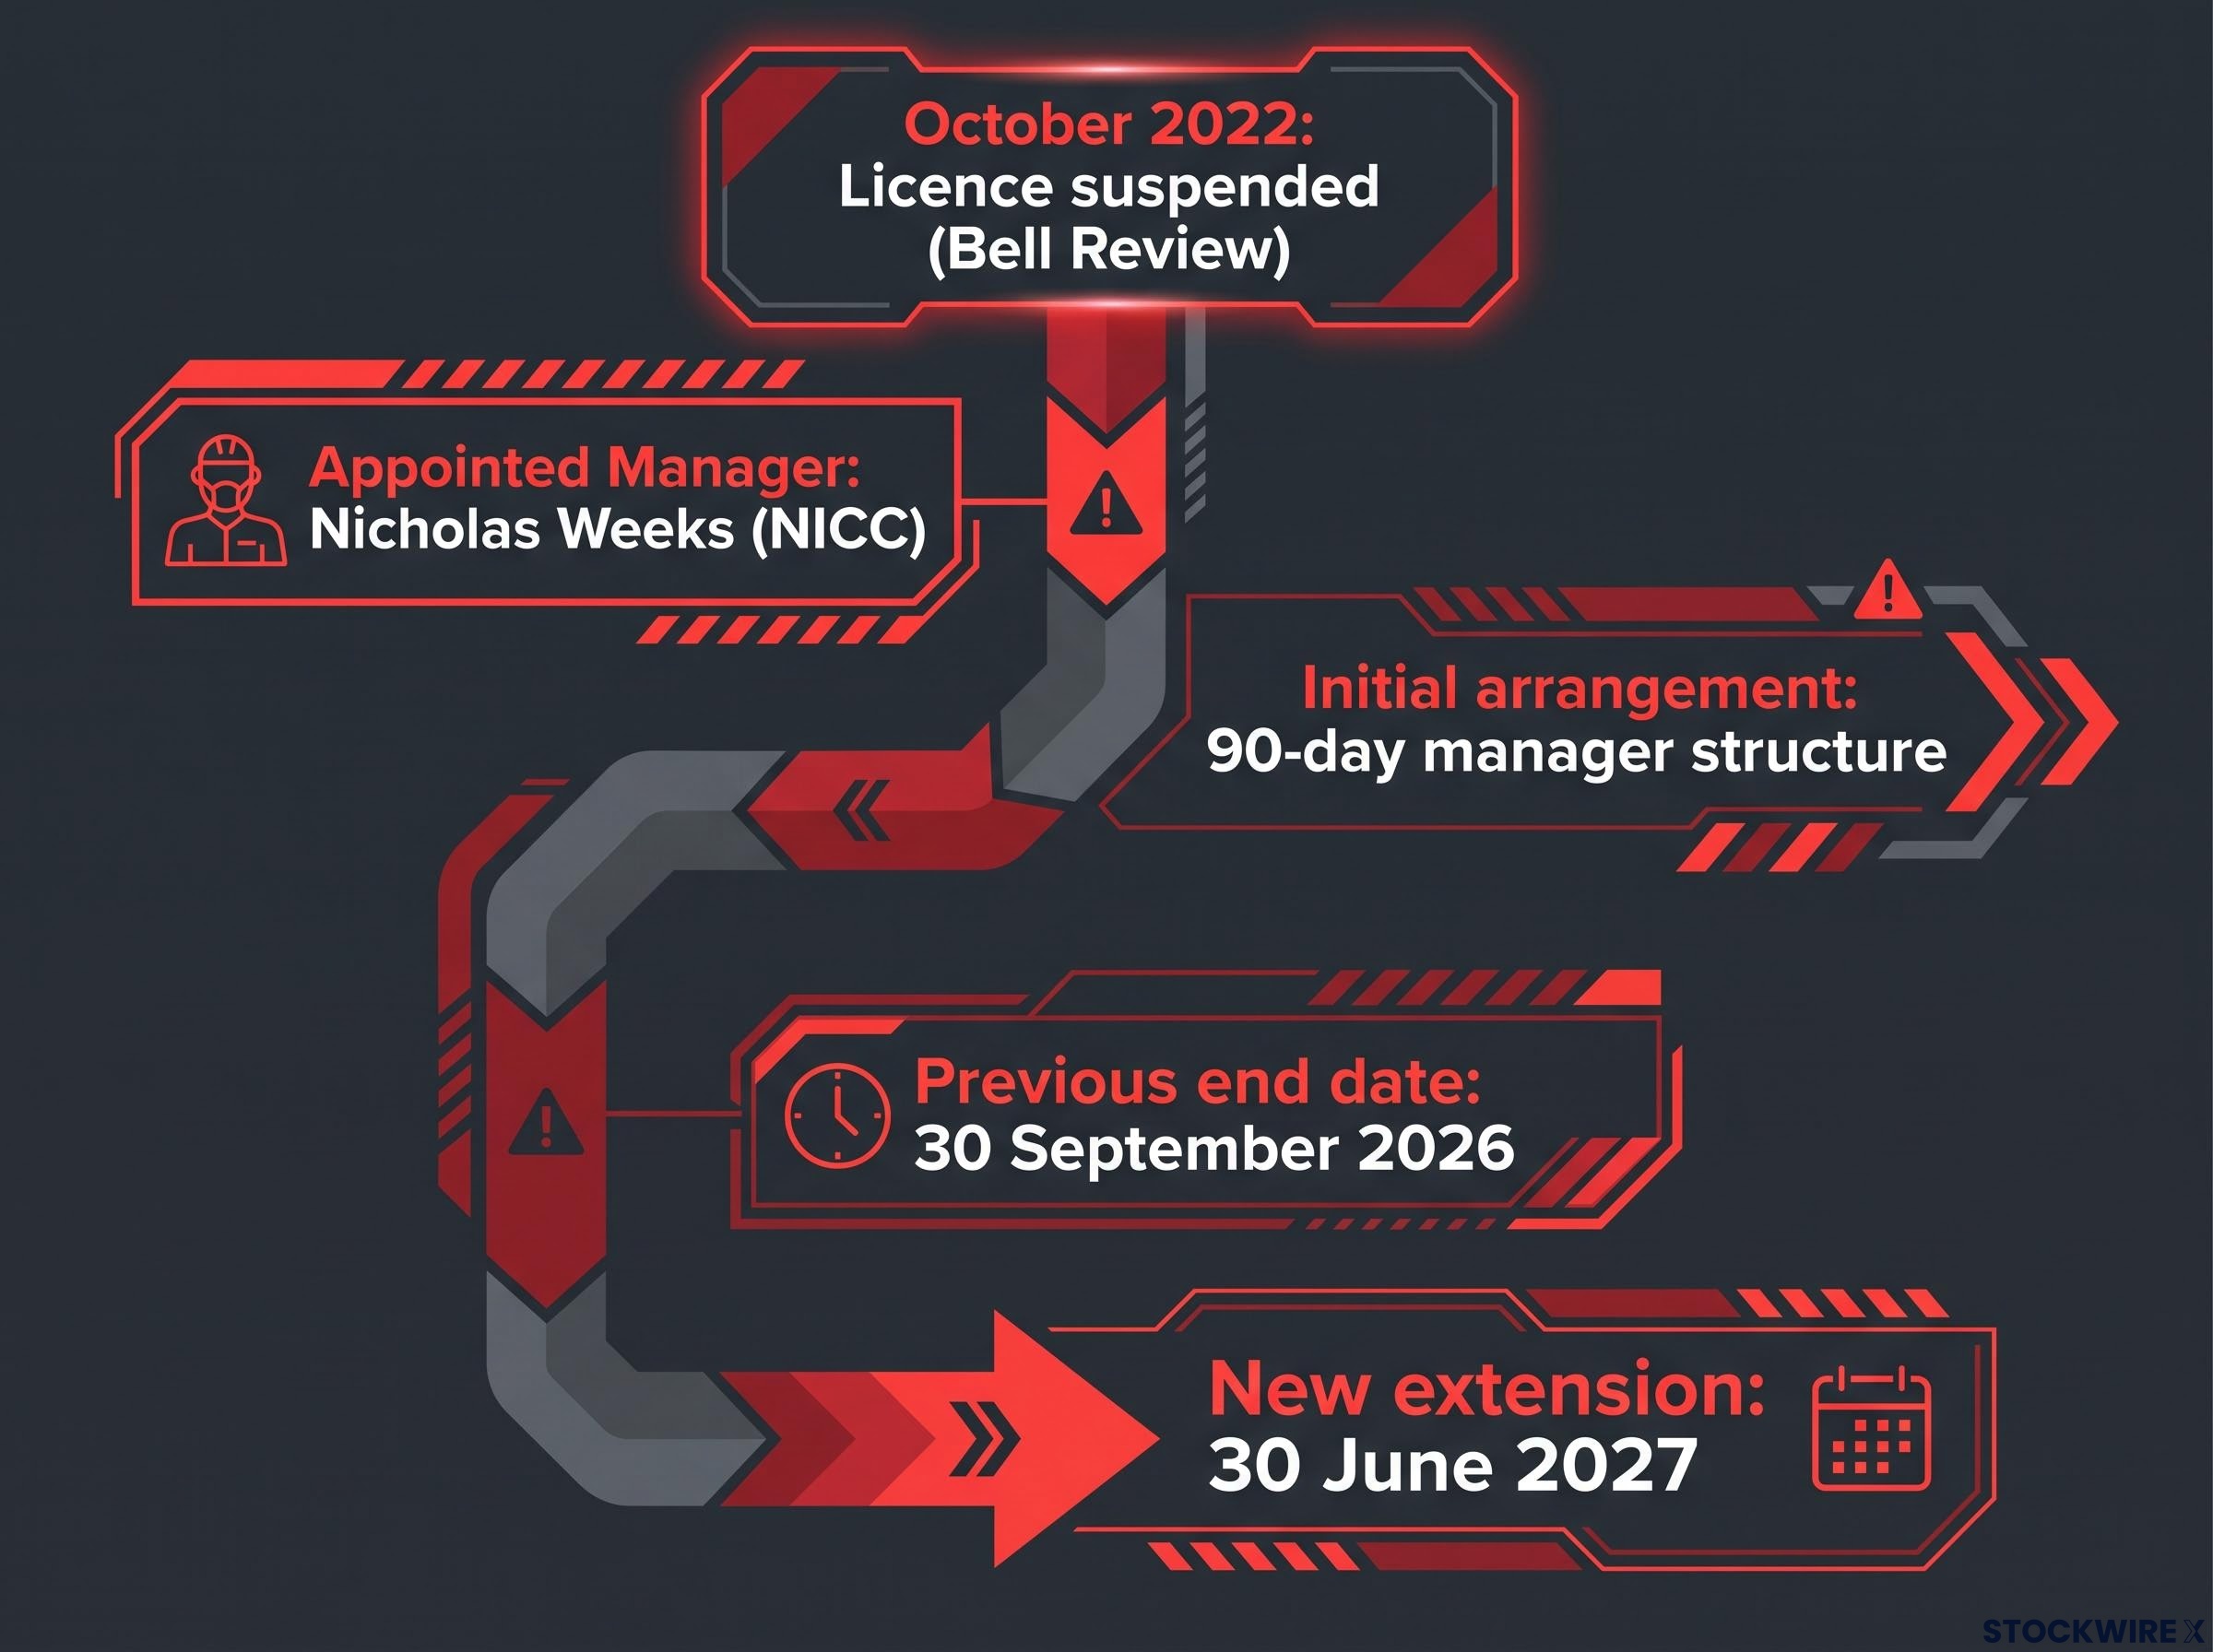
- The licence was suspended in October 2022 following the Bell Review into governance and cultural failings
- The appointed-manager structure began as a 90-day arrangement and has been extended repeatedly since
- The latest extension pushes the end date from 30 September 2026 to 30 June 2027
Governance and culture concerns remain central to the NICC’s ongoing assessment of whether Star can again meet the regulatory suitability threshold. The Australian Financial Review characterised the decision as the regulator concluding Star was “not ready to take back control” of the property.
Casino regulatory settlements elsewhere in the sector show how these processes can resolve: SkyCity Entertainment reached a A$21 million agreement with South Australia’s gambling commissioner in June 2026, structured across three instalments and tied to board governance reforms, offering a reference point for what a negotiated outcome actually looks like.
“Not ready to take back control.” The AFR’s read on why the NICC extended rather than returned the licence.
For investors, the 10% fall reflects more than a single day’s news. It is the compounding weight of four years of regulatory limbo, and the market is now actively pricing the real possibility that the licence may not return to Star on any near-term timeline.
NetWealth: class action detail remains limited, but the market reaction was not
NetWealth shares fell approximately 8.1% after news of a class action tied to a fund failure that occurred in 2024. The fund had been available on NetWealth’s platform, and the company is contesting the action.
Beyond that, the detail is thin. The specific fund, the alleged loss amounts, and the plaintiff behind the action have not been publicly confirmed in available reporting.
That gap is worth flagging. This is a developing situation, and the share price reaction ran ahead of the confirmed facts, which is itself the signal here: markets reprice legal risk on the shape of the threat before the magnitude is known.
The rest of the session: dividends, gold, and IAG’s legal resolution
Away from the four big movers, Friday delivered a scattered mix of dividend mechanics, commodity pressure, and one meaningful legal clean-up.
IAG was the most forward-looking of the group. Shares closed up around 0.5% after the insurer settled a long-running Federal Court dispute connected to the collapse of Greensill Capital, stating the resolution would not materially affect its financial position or FY27 results. Clearing that litigation removes an overhang that had been sitting on the stock, and investors nudged it higher even though the move was small.
Elsewhere, several names traded on dividend flows and softer gold.
| Company | Move | Driver | Key detail |
|---|---|---|---|
| Woodside | +0.3% | Dividend payment day | Among several payers settling dividends on the day |
| Nick Scali | -3.7% | Ex-dividend timing | Ex-dividend date falls the following week |
| IAG | +0.5% | Legal settlement | Greensill-related dispute settled; no material FY27 impact |
| Newmont | -2% | Gold price weakness | Part of broader gold mining pressure |
| Other payers | Mixed | Dividend payment day | Woolworths, GQG Partners, McMillan Shakespeare, Amcor, Credit Corp |
For readers, the useful distinction here is between noise and signal. A dip like Nick Scali’s ahead of an ex-dividend date is mechanical and expected; IAG shedding a piece of litigation risk is the kind of development that genuinely changes the risk profile of a holding.
Ex-dividend mechanics, including the ASX T+2 settlement cycle, explain why a stock like Nick Scali trades lower in the days before a dividend date: buyers who settle after the record date do not qualify for the declared payment, so the share price adjusts to reflect the value leaving the company.
What Friday’s movers reveal about where the market is pricing risk right now
Line the session up and a pattern emerges. On a day the index fell, the market sorted stocks with unusual precision by how much unresolved uncertainty each one carried.
The heaviest falls clustered around risks with no visible resolution date. Star’s 10% slide came from a regulatory process now stretching past four years, while its Sydney casino keeps generating revenue: a live tension the market is openly pricing. NetWealth dropped 8.1% on a class action whose material details are still unconfirmed, which tells you investors will react to the shape of a legal threat well before its size is known.
The strongest gains came from clarity. Healius had a concrete deal at 19.8x earnings; EOS had a demand thesis so durable it produced a 600%-plus return over the prior year.
On a down day, the market rewarded resolved catalysts and punished open-ended uncertainty, and the size of the punishment was not always tied to the size of the news.
If you hold any stock with unresolved regulatory or legal exposure, Friday is the concrete reminder: those risks do not price gradually, they crystallise in a single session.
Unresolved regulatory exposure and legal overhang are among the risk factors a structured share-selection process screens for before entry: a stock’s earnings profile can look attractive while an undisclosed or ongoing suitability determination quietly suppresses any re-rating.
The variables to watch from here are specific. For Star, it is the NICC’s suitability determination, with no next milestone publicly set. For NetWealth, it is the class action process, still developing.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.