
NEXTDC complies with both financial covenants, with A$526.8 million of ICR headroom
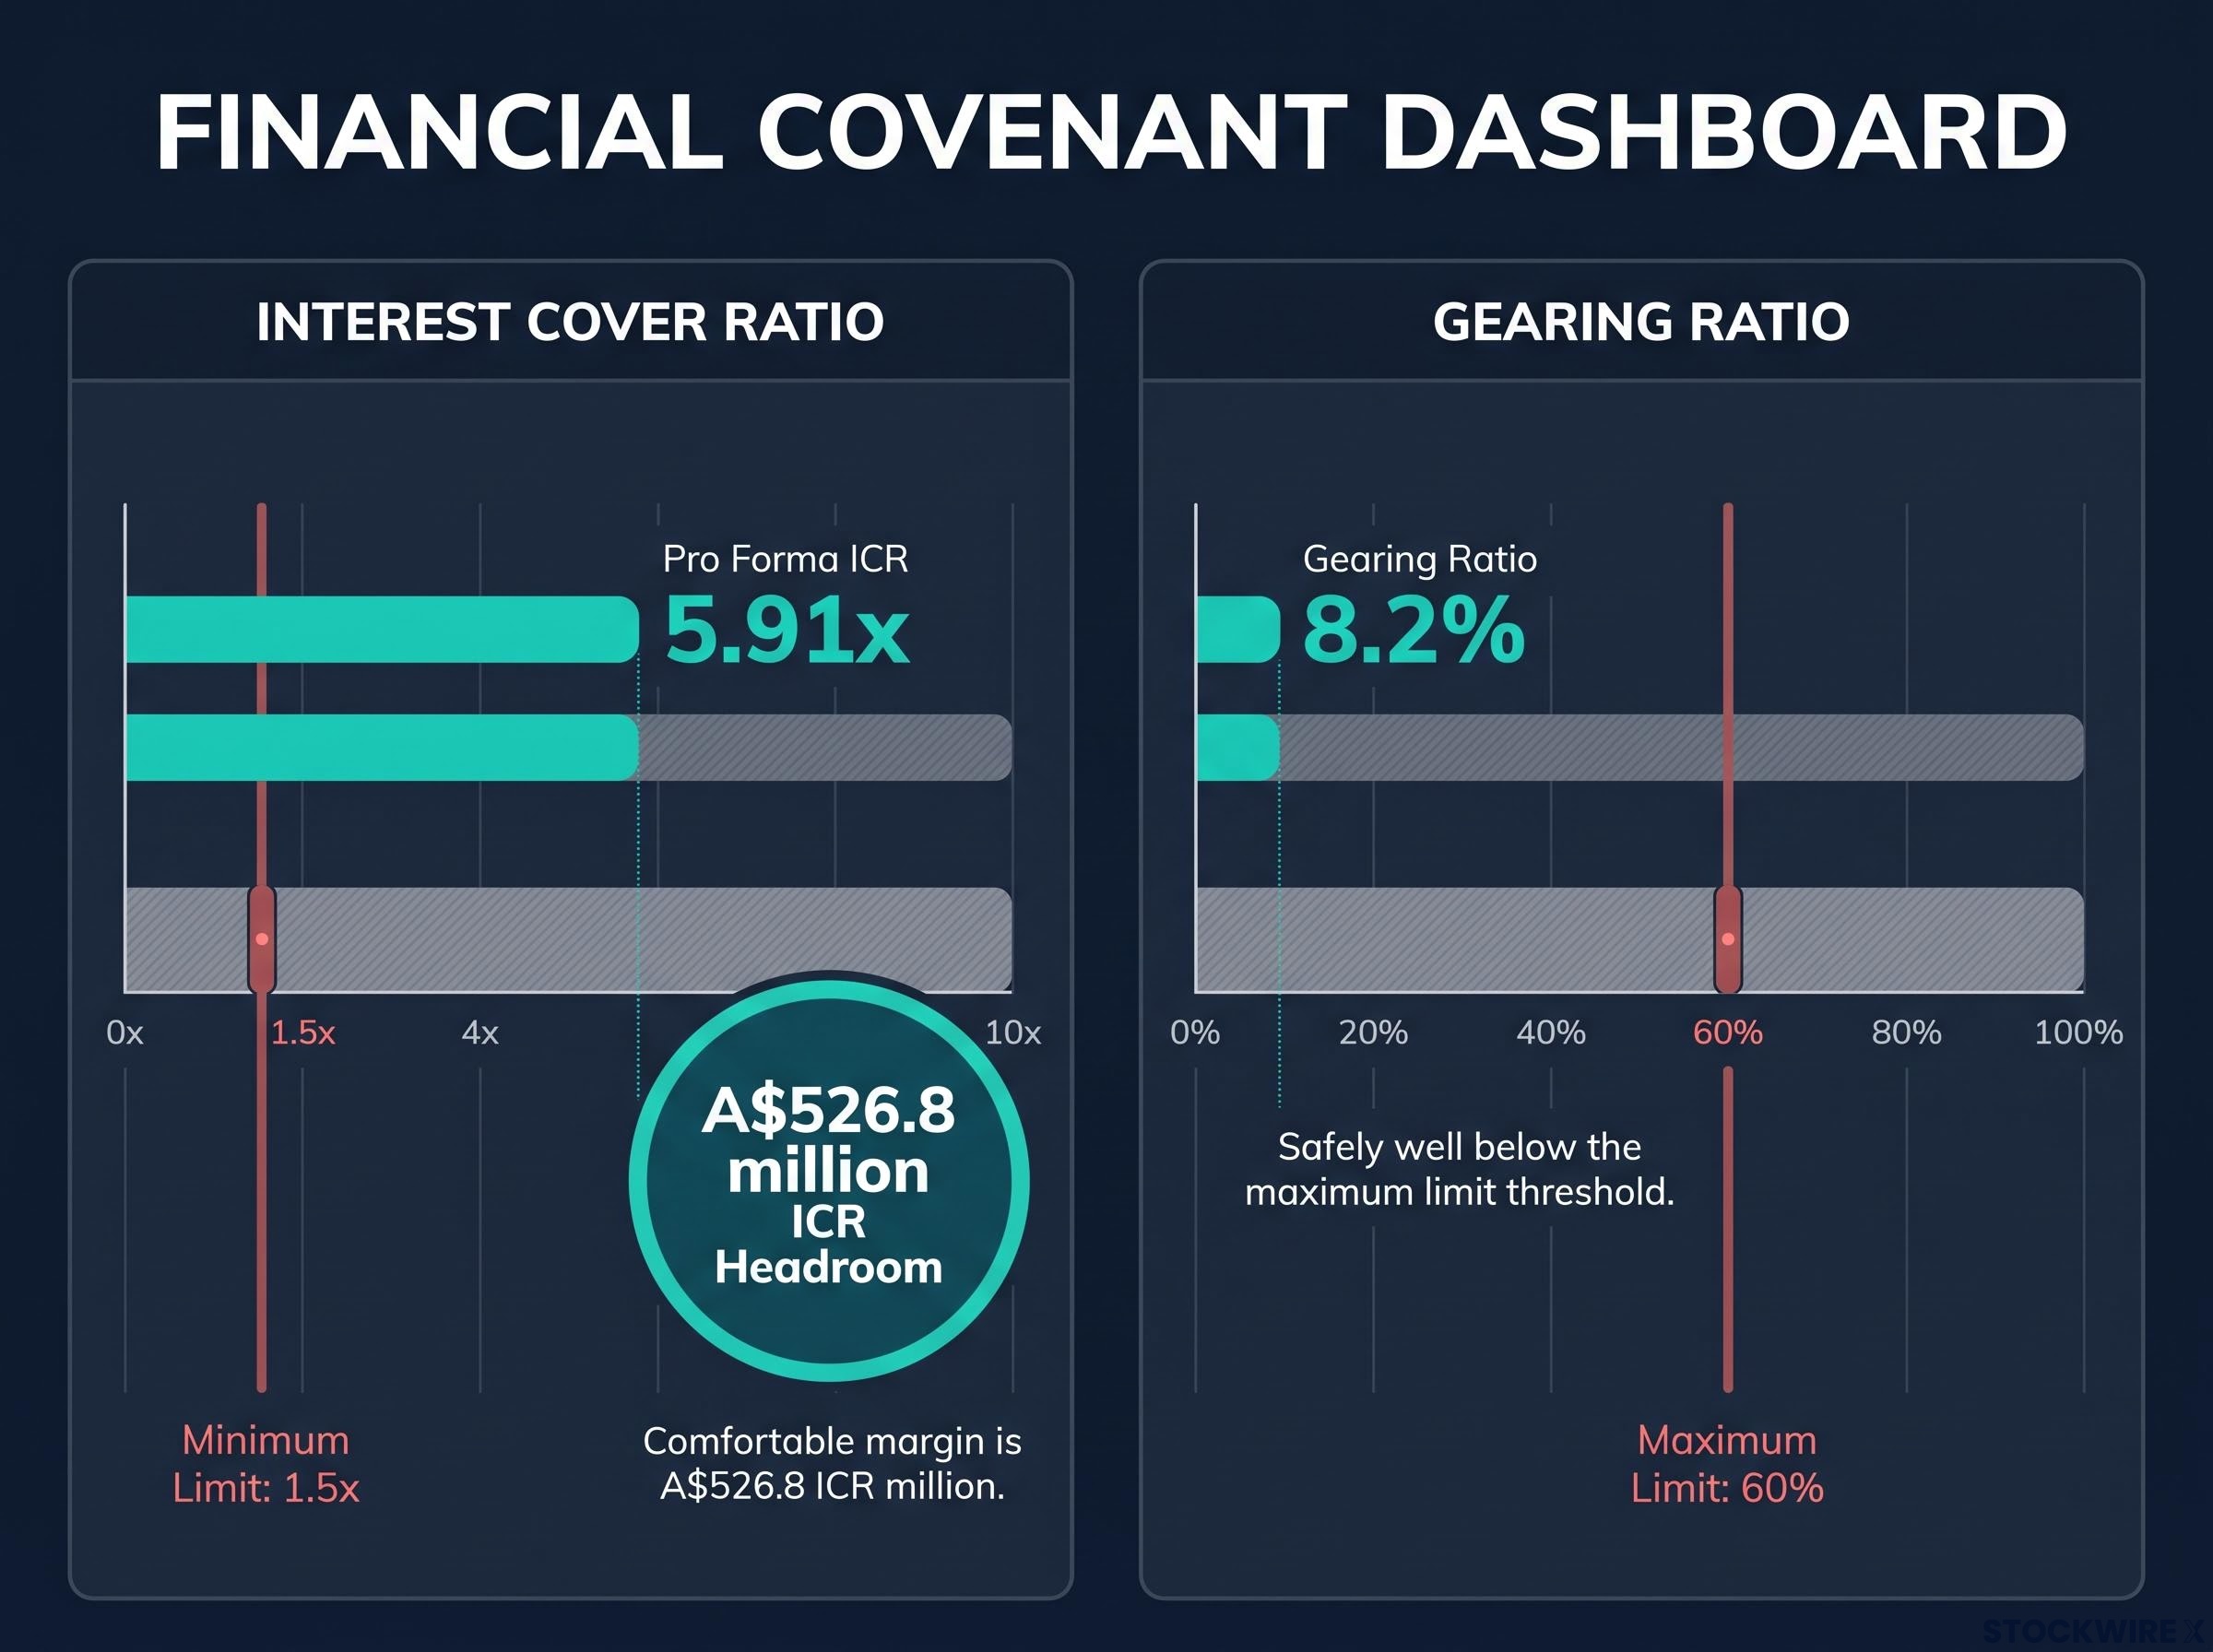
NEXTDC (ASX: NXT) has submitted its covenant compliance report to its senior debt financiers for 30 June 2026, the most recent half yearly test date, and complied with both NEXTDC financial covenants. The release also sets out covenant headroom to help stakeholders understand the tests more broadly.
Key figures from the 28 October 2026 release:
- Interest Cover Ratio (ICR): 5.91x, pro forma, against a minimum of 1.5x
- Gearing Ratio: 8.2%, against a maximum of 60%
- Liquidity: A$8,675 million at 30 September 2026
The ICR is pro forma for the increased contracted utilisation announced on 21 July 2026, which is not included in the compliance report. The Gearing Ratio is as certified. For investors, the figures show wide buffers against both tests.
When big ASX news breaks, our subscribers know first
How the covenant numbers stack up
Pro forma ICR at 30 June 2026
The ICR headroom is A$526.8 million of Covenant EBITDA, which is how much that EBITDA could fall, with net interest expense unchanged, before the ICR reached 1.5x.
| A$ million | Pro forma |
|---|---|
| EBITDA for the 12 months, before Contracted EBITDA | 262.1 |
| Pro Forma Contracted EBITDA | 444.0 |
| Pro Forma Covenant EBITDA (A) | 706.0 |
| Net interest expense (B) | 119.5 |
| Pro Forma ICR (A ÷ B) | 5.91x |
| Covenant EBITDA needed for the minimum of 1.5x (C) | 179.2 |
| Pro Forma Headroom (A less C) | 526.8 |
These figures are pro forma and are not the final CTDP ICR certified under the CTDP. They are also not a forecast of the ratios at the next test date.
The pro forma Contracted EBITDA adds the additional 73MW of contracted utilisation announced on 21 July 2026. Billing for it is forecast to start in the second half of FY27.
The 740MW of contracted utilisation reported at 30 June 2026 includes that 73MW addition, leaving a pro forma forward order book of 565MW still to convert to billing.
Gearing Ratio as certified
Net senior debt of A$834.3 million divided by total assets at book value of A$10,182.3 million gives a Gearing Ratio of 8.2%, against a maximum of 60%.
Both covenants are tested at 30 June and 31 December each year. They are measured for NEXTDC’s Australian group, not the whole NEXTDC group.
Covenants explained: what they test and what they exclude
Maintenance covenants are lending conditions that a borrower must meet at set test dates. NEXTDC’s two tests work as follows:
- ICR: Covenant EBITDA divided by net interest expense, for the 12 months to the test date
- Gearing Ratio: net senior debt divided by total assets at book value, as at the test date
Covenant EBITDA includes “Contracted EBITDA”, defined as the expected fully ramped up annualised (but not yet billed) EBITDA from new customer contracts in place at each test date, if billing is expected to commence within 24 months of that date.
Other key points on scope:
- The covenants sit in the Common Terms Deed Poll dated 3 November 2024, as amended
- They apply to the senior loan facilities benefiting from the CTDP, which currently represent all of NEXTDC’s senior debt
- Subordinated Capital (Subordinated Notes, Hybrid Securities and Convertible Notes) is not included in those covenants and has no maintenance financial covenants of its own
The Subordinated Notes and Hybrid Securities are subject to an incurrence covenant, under which certain debt or hybrid issuances, material asset disposals and equity distributions may be made only if the Adjusted Gearing Ratio does not exceed 85%.
M3 Melbourne exclusion and liquidity position
Conservative treatment of affected M3 contracts
Given the uncertainty around the M3 power delays outlined in the 21 October 2026 announcement, NEXTDC has excluded any pro forma Contracted EBITDA of the affected customer contracts at M3 Melbourne, along with any potential service level credits associated with them. As a result, EBITDA for the 12 months to 30 June 2026 only includes earnings from capacity under those contracts that has already been billed.
Grid supply at M3 Melbourne is expected to increase in stages. The first increase depends on works by Jemena Electricity Networks (Vic) Ltd, and NEXTDC expects it during FY28 based on Jemena’s current indicative estimate.
The exclusion does not apply to NEXTDC’s other existing customer contracts at M3 Melbourne, whose capacity is fully commissioned and operational.
For readers wanting to understand the grid supply issue in more depth, our full explainer on the M3 Melbourne power delay covers the Jemena works timeline, the cut to FY27 guidance and the capex reduction that followed.
Liquidity of A$8,675 million at 30 September 2026
Liquidity is made up of:
- A$1,275 million of cash
- A$7,400 million of undrawn senior debt facilities and Hybrid Securities, which is committed, subject to customary conditions
| A$ million | Limit | Drawn | Undrawn |
|---|---|---|---|
| Total senior debt facilities | 8,700 | 2,000 | 6,700 |
| Total Subordinated Capital | 3,550 | 2,850 | 700 |
| Total | 12,250 | 4,850 | 7,400 |
The undrawn Subordinated Capital is the A$700 million Hybrid Securities B Delayed Draw Series. The covenant ratios at 30 June 2026 are not a measure of how much senior debt NEXTDC can draw under its existing facilities. That ability depends on the timing of drawdowns and on the expected billing profiles of new customer contracts at that time.
What happens next for NEXTDC’s covenant testing
Several dated items follow from the release:
- 31 December 2026: next covenant test date. NEXTDC continues to expect to comply with both covenants.
- 31 December 2026 covenant compliance report: NEXTDC expects to include the additional 73MW of contracted utilisation.
- Second half of FY27: billing for the additional contracted utilisation is forecast to start.
- FY28 (the financial year ending 30 June 2028): the first grid supply increase at M3 Melbourne is expected, based on Jemena’s current indicative estimate, with delivery and billing of the dependent contracted capacity to follow shortly thereafter.
- 15 May 2027: the A$700 million Hybrid Securities B Delayed Draw Series may be drawn until this date.
NEXTDC will continue to assess the effect of the M3 grid delays on its debt facilities, including its ability to draw its undrawn debt facilities while continuing to comply with its financial covenants.
Get Tech News Before the Market Moves
Join 20,000+ investors getting FREE breaking ASX news within minutes of release, complete with in-depth analysis and the full announcement. Click the “Free Alerts” button at Big News Blast to receive tech sector alerts the moment market-moving news breaks, so you stay ahead of the crowd.