
NEXTDC revises FY27 guidance as M3 Melbourne power delay defers contracted revenue
NEXTDC (ASX: NXT) revised its FY27 net revenue, Underlying EBITDA and capital expenditure guidance on 21 October 2026, after Jemena Electricity Networks (Vic) Ltd works delays deferred the next increase in grid supply to its M3 Melbourne data centre. The revision excludes the affected M3 contracts from net revenue and Underlying EBITDA guidance.
The company reported liquidity of A$8,675 million at 30 September 2026 and said it remains in compliance with its financial covenants. It has also said it will refocus capital expenditure on near term contracted customer capacity.
The affected capacity “remains under contract, subject to the customer’s rights”, according to the company. The announcement frames the issue as one of timing, with delivery and billing deferred, and does not describe a confirmed loss of the contracts.
Craig Scroggie, Chief Executive Officer and Managing Director
“With M3 revenue deferred, we have paused projects not backed by customer contracts and put that capital behind the capacity our customers have already contracted…”
When big ASX news breaks, our subscribers know first
Revised FY27 guidance at a glance
The revised net revenue and Underlying EBITDA ranges are materially lower than the guidance issued on 27 August 2026. Capital expenditure guidance has also been reduced.
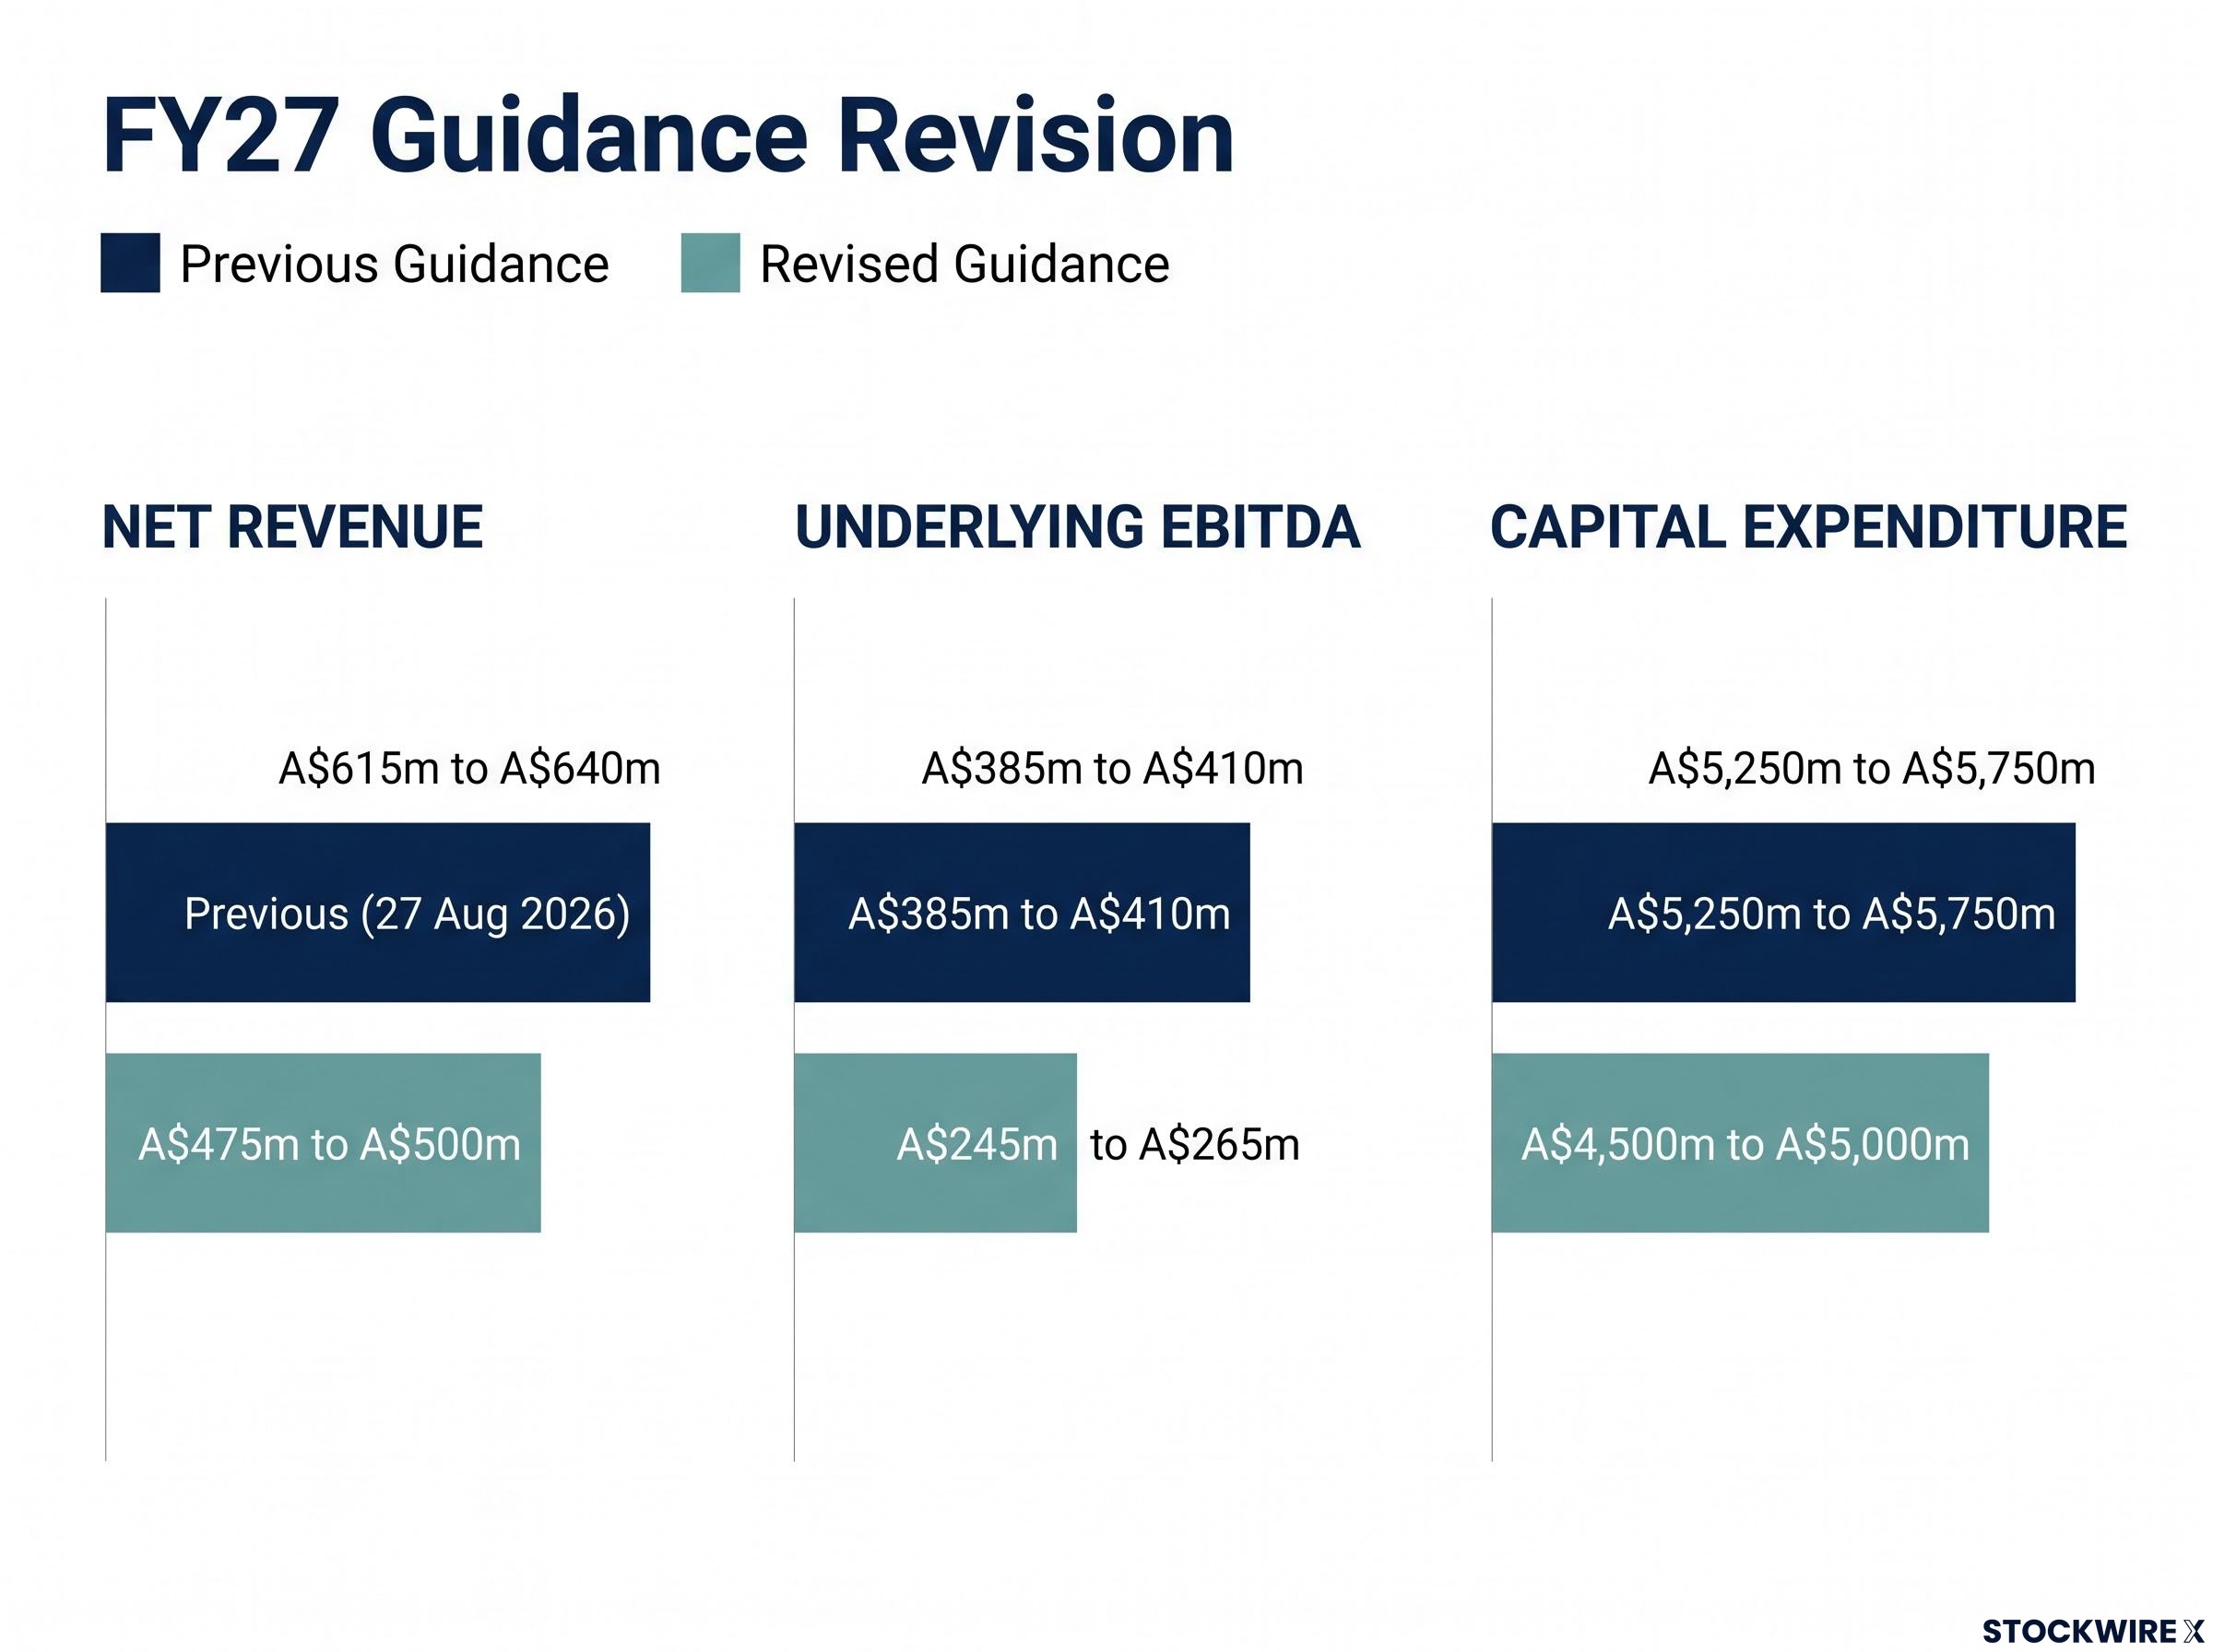
The August guidance was set alongside NEXTDC’s FY26 full-year results, which beat the top end of guidance and projected more than 50% growth on FY26 actuals.
| Metric | Previous guidance (27 Aug 2026) | Revised guidance | Change |
|---|---|---|---|
| Net revenue | A$615m to A$640m | A$475m to A$500m | Excludes affected M3 contracts |
| Underlying EBITDA | A$385m to A$410m | A$245m to A$265m | Excludes affected M3 contracts |
| Capital expenditure | A$5,250m to A$5,750m | A$4,500m to A$5,000m | Reduction of A$750m, or 13% to 14% |
What drives the revision
The revised net revenue and Underlying EBITDA guidance excludes the revenue and attributable EBITDA of the affected customer contracts at M3 Melbourne, including capacity already billing and any potential service level credits. The August guidance included approximately A$140 million of each of net revenue and Underlying EBITDA from those contracts, and their exclusion is the main reason for the reductions.
Capacity already billing is excluded because, while parts of Jemena’s works are suspended, existing grid supply at M3 cannot be relied on to support the full contracted power ramp in data halls already delivered.
NEXTDC’s actual FY27 results will include the contribution of the affected contracts. Service level credits payable on those contracts could reduce Underlying EBITDA below the revised guidance, which is given on a constant currency basis and before any fair value movement on investment property.
Investors exploring how contracted demand converts into billing can read our detailed coverage of the 565MW forward order book, which tracks the 740MW contracted utilisation position and the FY30 conversion timeline.
Understanding the M3 Melbourne power delay
A data centre earns revenue from capacity it can power. Where a grid distributor controls the supply of electricity to the site, network works by that distributor can determine when contracted capacity is delivered and billed.
For investors, this means revenue is linked to power availability, not only to completed buildings. The timing of third-party infrastructure is therefore a key variable. Jemena is the electricity distributor that supplies power to M3.
Timeline and key dependencies
- Jemena suspended parts of its 66kV line augmentation works in September 2026, citing safety concerns and lack of access to work sites arising from community and stakeholder opposition, and the local council, as the relevant road authority, not giving its consent while further community consultation takes place.
- Jemena has formally notified NEXTDC that it does not expect to recommence the works before February 2027.
- Based on Jemena’s current indicative estimate, NEXTDC expects the next increase in grid supply during FY28, with delivery and billing of the dependent contracted capacity to follow shortly thereafter.
- Later increases depend on upstream transmission projects to install new transformers at the Brooklyn Terminal Station. NEXTDC now expects the first of these to be completed later than previously expected, though they do not separately affect the revised FY27 guidance.
- The Victorian Government’s planning decision on M3 Stages 6 and 7 (application PA2604231, lodged February 2026) is not now expected until 2027. Caretaker conventions are due to begin on 3 November 2026, ahead of the State election on 28 November 2026.
Customer contracts and management response
NEXTDC said it has a good relationship with the affected customer and will continue to engage constructively with it. Construction of the M3 data halls is continuing within the existing buildings.
The company is working with the customer on a revised power ramp and with Jemena to bring forward the delivery of power to M3.
The affected contracts provide for service level credits where capacity is delivered late or is not fully powered and, in some circumstances, give the customer rights to terminate. NEXTDC is assessing the potential implications under those contracts, including whether relief is available to it under the force majeure and other relevant provisions.
NEXTDC also intends to continue and build on its community engagement around M3 through a community engagement plan for the construction and operation of M3, overseen by the Board.
Capital discipline and balance sheet strength
Capex refocused on contracted capacity
Revised FY27 capex of A$4,500m to A$5,000m includes approximately A$500m of reimbursable customer fitout and approximately A$230m of capitalised interest. The previous guidance did not include capitalised interest.
Before capitalised interest, the revised guidance is approximately A$4,270m to A$4,770m. That represents a like for like reduction of approximately A$980m, or 17% to 19%, which differs from the headline 13% to 14% reduction.
NEXTDC has put all new development projects and land acquisitions on hold for the foreseeable future and is eliminating all material discretionary capital expenditure. The Board has committed to announcing the outcome of its capex review by the Annual General Meeting on 20 November 2026, and will also evaluate capital recycling opportunities, including the potential sale of selected development sites not required in the near term.
Liquidity and covenants
Liquidity at 30 September 2026 was A$8,675 million. This is non-IFRS financial information and has not been subject to audit or review. Its components were:
- A$1,275 million of cash
- A$6,700 million of undrawn senior debt facilities
- The A$700 million Hybrid Securities B Delayed Draw Series, which is committed, subject to customary conditions, and may be drawn until 15 April 2027
NEXTDC remains in compliance with its maintenance financial covenants as at 30 June 2026, the most recent half-yearly test date, and expects to comply at the next test date of 31 December 2026. These covenants are a gearing ratio of not more than 60% and an interest cover ratio of at least 1.5 times.
The earliest scheduled debt maturity is December 2029, being the A$1,500 million Facility A revolving loan facility maturing on 3 December 2029. Holders of the Convertible Notes may require NEXTDC to redeem them on 17 September 2029.
One caveat applies. NEXTDC’s ability to draw all of its A$6,700 million undrawn senior debt facilities while continuing to comply with those covenants will depend on the timing of drawdowns and on expected billing profiles, and delays to grid supply at M3 Melbourne could be a material change to those profiles.
The Subordinated Notes, Hybrid Securities and the A$1,100 million of 1.75% Subordinated Convertible Notes due 2031, issued on 17 September 2026, carry no maintenance financial covenants.
What investors should watch next
The announcement points to several upcoming events:
- Investor briefing at 9:30am (AEDT) on 21 October 2026.
- Annual General Meeting and capex review outcome on 20 November 2026.
- The Victorian State election on 28 November 2026, and the later M3 Stages 6 and 7 planning decision, not expected until 2027.
- Half-year results to 31 December 2026, which will reflect the fair value effect on investment properties, not yet quantified.
- An update on the FY27 contribution of the affected contracts, which NEXTDC said it will provide when it can reliably estimate it.
Get Tech News Before the Market Moves
Join 20,000+ investors receiving FREE breaking ASX tech news within minutes of release, with in-depth analysis and the full announcement included. Click the “Free Alerts” button at Big News Blast to get market-moving updates the moment they break and stay ahead of the market.