
Dexus Q1 FY27 highlights: office occupancy at 94.2% and industrial leasing spreads of 36%
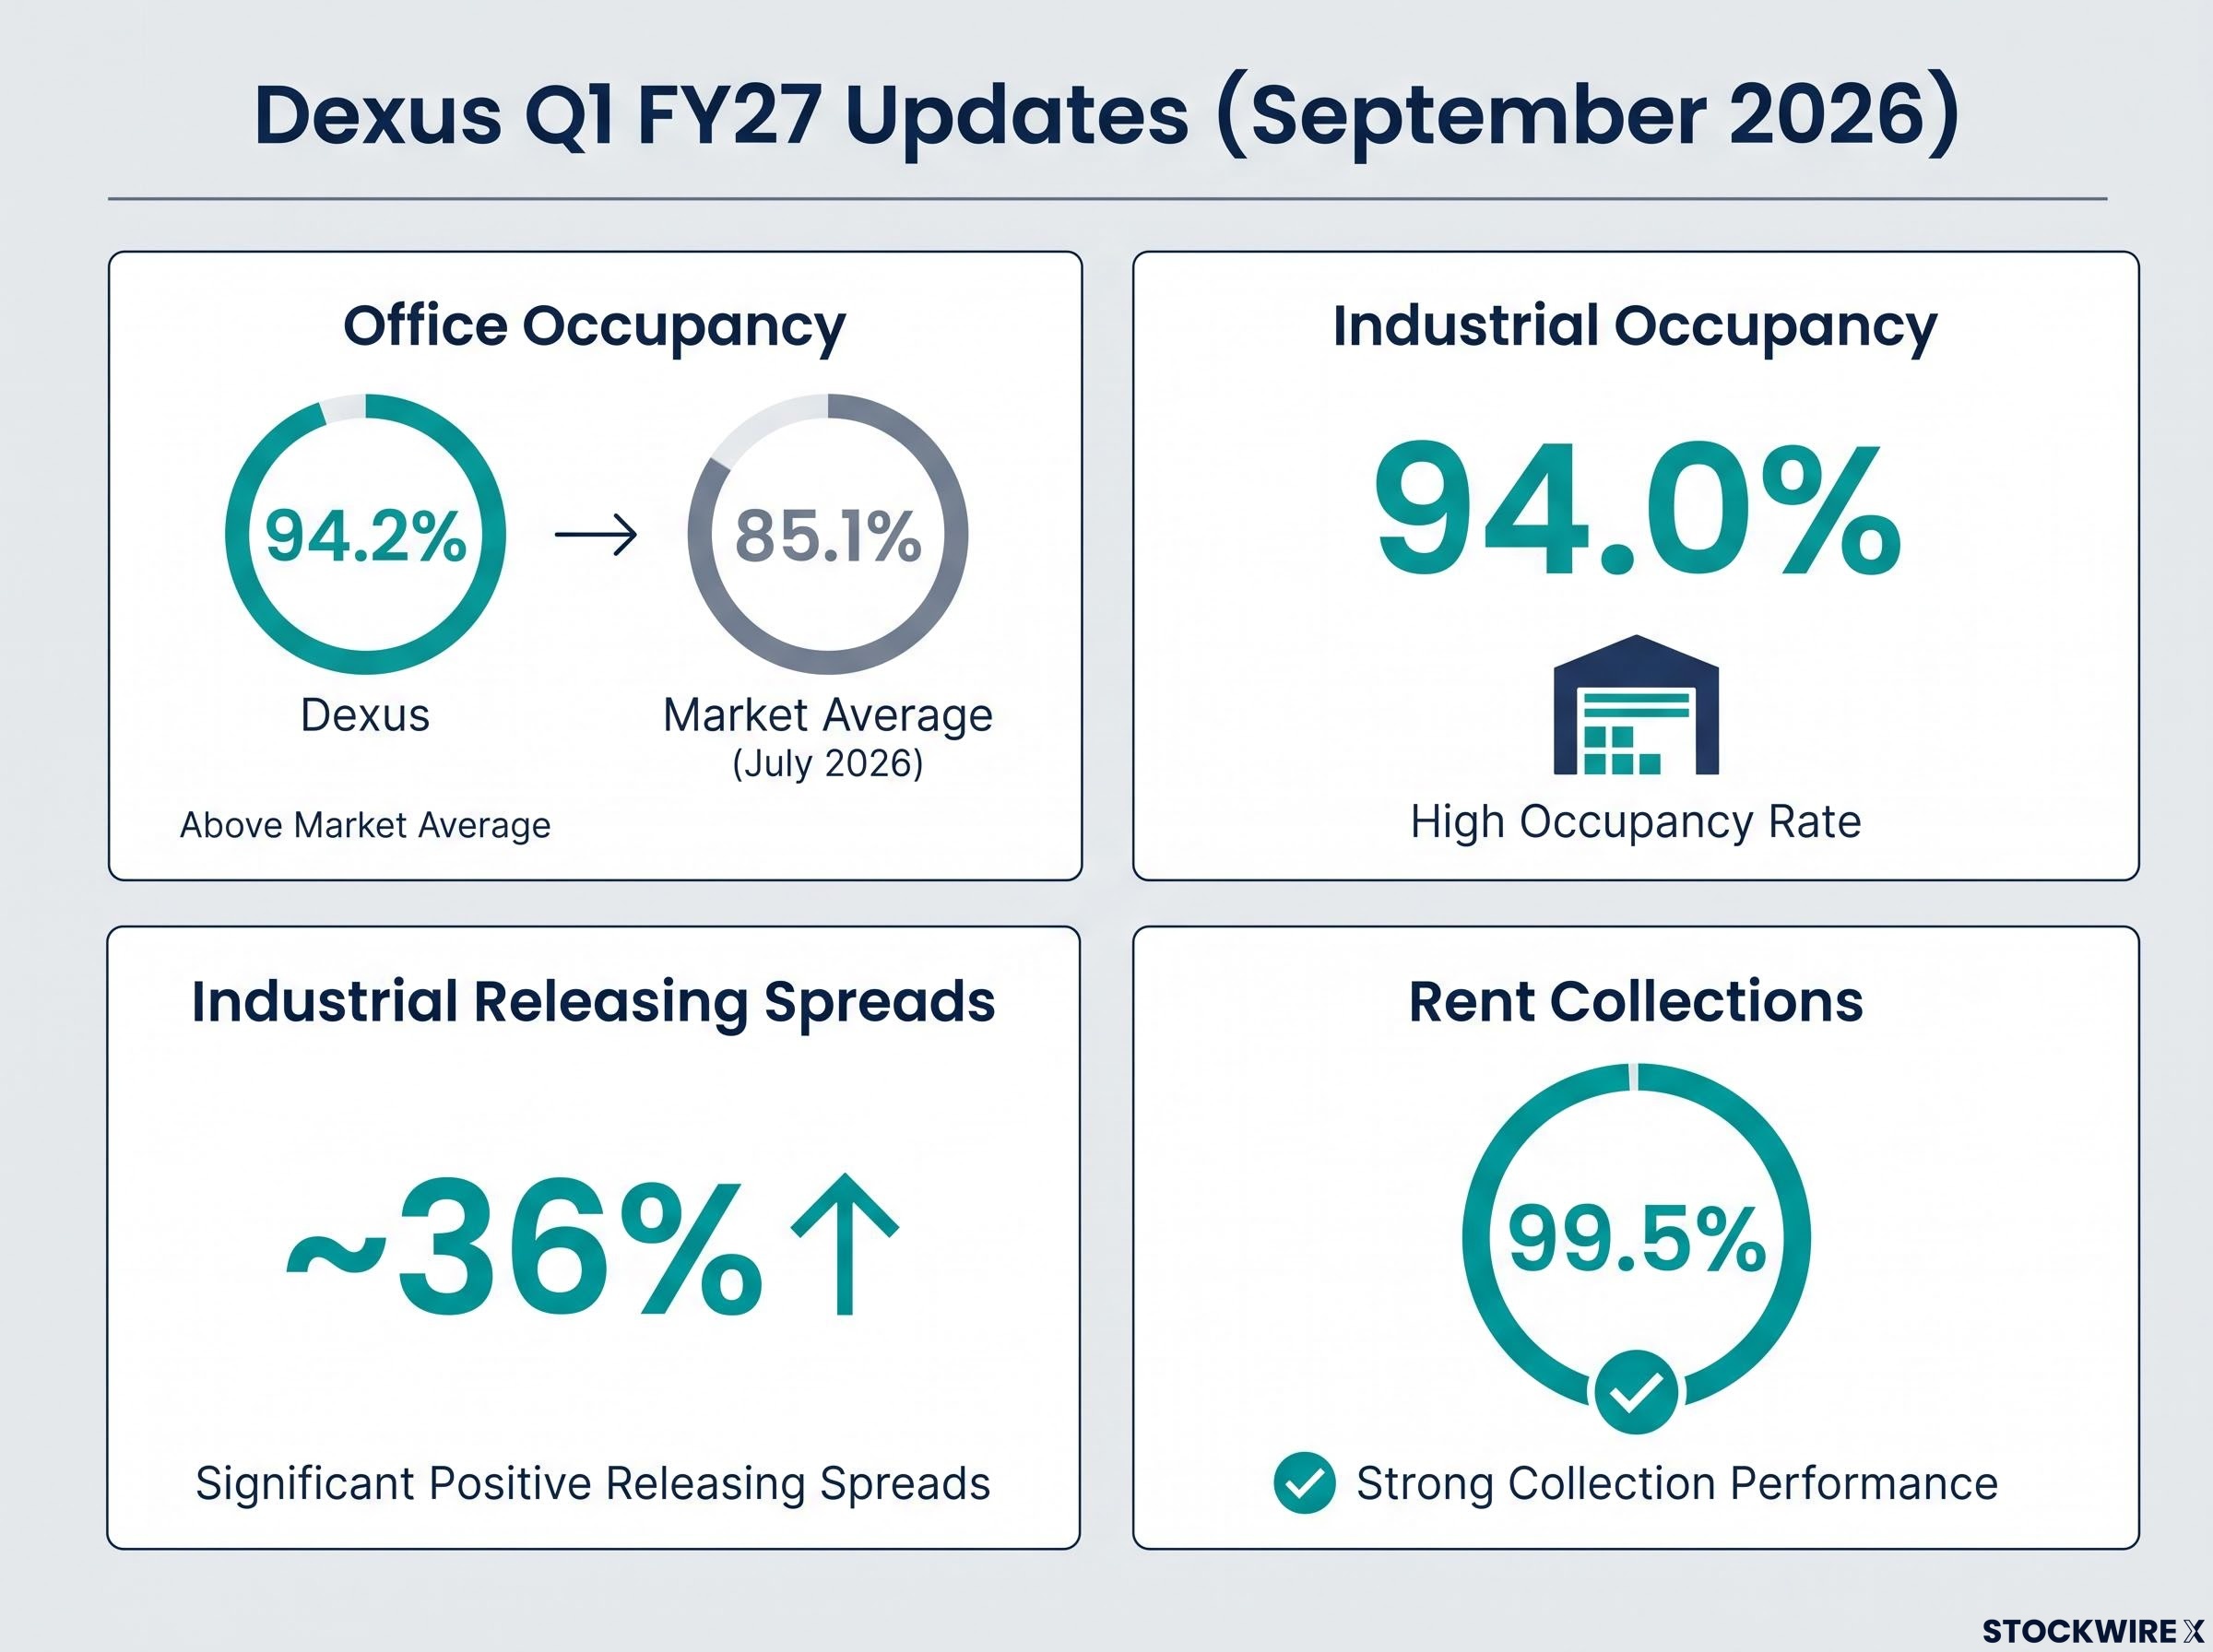
In its Q1 FY27 update for the September 2026 quarter, Dexus recorded office occupancy by income of 94.2%, industrial occupancy of 94.0% and industrial releasing spreads of circa 36%. Rent collections were 99.5%.
Dexus put its office occupancy well above the market average of 85.1%, a figure drawn from the Australian CBD vacancy average published by the Property Council of Australia at July 2026.
Dexus’s FY26 annual results showed office occupancy of 95.7% against the same 85.1% market average, alongside a resumed securities buyback aimed at a 35% discount to NTA.
Ross Du Vernet, Group Chief Executive Officer & Managing Director
“This quarter’s results show continued strength in operational performance across our property portfolio, outperformance in our largest flagship funds, and progress attracting capital into the funds platform. However, the shifting macroeconomic environment and interest rate outlook may slow the recovery.”
Capital raising across the funds platform was a further feature of the quarter:
- Circa $230 million of third party equity commitments from domestic and offshore investors since 30 June 2026, including DRP, secondaries and equity commitments
- More than $165 million of that total came from secondary unit transactions across the platform
When big ASX news breaks, our subscribers know first
Portfolio performance across office and industrial
Dexus’s $15.3 billion portfolio (data as at 30 June 2026) comprises predominantly $9.8 billion in office and $3.6 billion in industrial. The key metrics below compare the September 2026 quarter with 30 June 2026.
Office portfolio resilience
| Metric | Office 30 Sep 2026 | Office 30 Jun 2026 | Industrial 30 Sep 2026 | Industrial 30 Jun 2026 |
|---|---|---|---|---|
| Occupancy by income | 94.2% | 95.7% | 94.0% | 94.6% |
| Weighted average lease expiry (by income) | 4.0 years | 4.1 years | 4.2 years | 4.3 years |
| Average incentives | 23.8% | 26.4% | 20.1% | 20.6% |
Office occupancy eased slightly over the quarter. Dexus attributed the dip to expiries at Australia Square in Sydney and 240 St Georges Terrace in Perth, partly offset by leasing at 1 Farrer Place in Sydney and 180-222 Lonsdale Street in Melbourne.
Average incentives reduced to 23.8%, primarily reflecting lower incentive deals in the Sydney prime core market and a higher proportion of effective deals. Excluding effective deals, incentives were 29.6% (compared to 29.9% at FY26). Circa 78% of the office portfolio is located in core CBD locations.
Industrial leasing momentum
Dexus secured 113,600 square metres of industrial leasing, including 23,500 square metres of development leasing. Four development commitments were secured at ASCEND Industrial Estate, Jandakot.
The portfolio remains 8.1% under-rented, which Dexus said creates opportunities as vacancies are leased and rents are reset on expiries. Those vacancies and expiries together represent approximately 21.4% of portfolio income to FY28.
Developments
Atlassian Central in Sydney is on schedule for completion in late 2026, with the structure complete and façade nearing completion. At Waterfront Brisbane, the core has reached level seven.
At ASCEND, construction continues at seven industrial projects across 71,000 square metres. Two of those were newly committed since FY26, and both are 100% pre-leased.
Capital recycling, funds platform and a refocused strategy
Transactions and the Anthropic data centre lease
Contracts were exchanged during the quarter to sell 101 George Street, Parramatta for a gross sale price of $143.9 million, of which Dexus has a 50% interest. The price reflects a 7.1% discount to last stated book value, and the sale represents Dexus’s exit from the Parramatta suburban office market.
After quarter-end, Dexus achieved initial settlement on the sale of 30-34 and 36 Hickson Road, Millers Point and 123 Albert Street, Brisbane, which were previously announced within its FY26 results.
A consortium including Australian Data Centres, in which Dexus holds an 85% interest, entered into lease documentation with an Australian subsidiary of Anthropic. The lease covers delivery of the first stage of the proposed development of a hyperscale data centre campus in the Western Downs region of Queensland, subject to customary approvals, including Dexus Board approval. Dexus may participate in the capital raising as an investor but has not as yet made a decision to do so.
Investors exploring the data centre opportunity further can read our detailed coverage of the Anthropic data centre lease, which sets out the consortium structure, Dexus’s indirect exposure through its 85% ADC interest and the conditions still attached to Stage 1.
Funds management
Dexus manages $36.1 billion of funds (data as at 30 June 2026). Flagship funds DWPF and DWSF outperformed their benchmarks across all reported time periods, with DWPF delivering a one-year return of 10.0% and DWSF 14.4% (post fees).
Dexus Real Estate Partnership 2 (DREP2) closed FY26 with total commitments of circa $870 million, including $200 million raised via a dedicated sidecar. It has now committed capital into four opportunities and is 35% allocated.
The responsible entity of the Dexus Healthcare Property Fund (DHPF) has engaged an independent advisor to review the full range of options, including asset sales, alternative capital and ownership structures, or a wind-up. DHPF’s third party funds under management (FUM) is $1.1 billion, and Dexus has a $180 million co-investment interest.
What the infrastructure review means
A funds management platform earns fees by managing property and infrastructure on behalf of outside investors. Third party FUM is the capital those investors have placed with the manager, so client demand for liquidity (the ability to exit or redeem) bears on the fee revenue a listed manager can earn.
The infrastructure funds and mandates, which transitioned to Dexus through its 2023 acquisition of AMP Capital’s real estate and infrastructure platform, represent $7.3 billion of third party FUM, $260 million of co-investment interests and $35 million of management fee revenues (excluding performance fees, post-tax and before associated costs). Macquarie Capital was engaged to support the review.
The review confirmed that clients across a number of funds are seeking liquidity. The focus during FY27 for the Dexus Diversified Infrastructure Trust (DDIT) and the Dexus Core Infrastructure Fund (DCIF) will be to progress asset sales to provide liquidity to clients.
Dexus is refocusing on office, industrial and retail, plus a targeted alternatives platform. That platform is currently focused on data centres and select living subsectors, as well as multi-sector investment opportunities such as healthcare precincts.
Outlook and what happens next for Dexus
Ross Du Vernet, Group Chief Executive Officer & Managing Director
“The infrastructure review has given us a clear basis to simplify the platform and focus our capital and capability where Dexus can deliver the strongest long-term outcomes.”
Barring unforeseen circumstances, Dexus reiterated its expectation for the 12 months ending 30 June 2027 of AFFO of 37.5 to 39.5 cents per security and distributions of 37.0 cents per security. On the buyback, Du Vernet said “We continue to view the buyback as a key lever to create value for security holders over the medium term…”, with meaningful progress linked to divestments and the release of capital from major transactions.
Upcoming events stated in the update:
- 101 George Street, Parramatta settlement: due in November 2026.
- APAC appeal: the appeal filed by Dexus Bloc shareholders on 25 June 2026 is due to be heard from 30 November to 2 December 2026. For funds and mandates with a stake in Australia Pacific Airports Corporation, the path forward will depend in part on its outcome.
- Atlassian Central completion: on schedule for late 2026.
- Waterfront Brisbane North Tower podium level five: delivery on track for later this financial year.
- Anthropic data centre first stage: subject to customary approvals, including Dexus Board approval.
Don’t Miss the Next Real Estate Mover on the ASX
Join 20,000+ investors getting FREE breaking ASX news from Big News Blast within minutes of release, complete with in-depth analysis. Click the “Free Alerts” button to receive real-time updates the moment market-moving announcements land, and stay ahead of the market on property and other non-resource sectors.