
EQT clears due diligence hurdle in Cleanaway takeover pursuit
Cleanaway Waste Management (ASX: CWY) has confirmed that EQT Infrastructure confirmed nothing has arisen in its due diligence review without identifying any issues that would cause it to walk away from the proposed acquisition. The update, released on 14 September 2026, relates to EQT’s confidential, non-binding indicative proposal dated 3 August 2026 to acquire 100% of Cleanaway shares via a scheme of arrangement.
EQT’s $9.4 billion proposal, lodged on 3 August 2026 at $3.13 per share, represented a 32.1% premium to Cleanaway’s last closing price and prompted the Board to signal its intention to recommend the deal, subject to execution of a binding implementation deed and a favourable independent expert conclusion.
The announcement follows the Transaction Process Deed entered into between the two parties on 13 August 2026, which governed the exclusivity period and process. That hard exclusivity period, running 20 Business Days after 17 August 2026, has now concluded. No offer price has been disclosed in this announcement, and Cleanaway has been explicit that no certainty exists a binding deal will result.
When big ASX news breaks, our subscribers know first
Three key confirmations from EQT
As contemplated by the Transaction Process Deed, EQT has provided Cleanaway’s board with written confirmation on three points:
- Nothing arising from its due diligence review is likely to cause EQT not to proceed with the Potential Transaction on the terms set out in the Proposal.
- EQT does not intend to make any variations to the terms of the Proposal that would make the Potential Transaction less favourable to Cleanaway shareholders.
- EQT commits to proceeding with the Potential Transaction for consideration no less than the indicative offer price, and to entering into an implementation deed on or before the expiry of the exclusivity period under the Transaction Process Deed.
With those confirmations delivered, the parties are now working towards the negotiation and execution of an implementation deed. Confirmatory due diligence is continuing in parallel.
What a scheme of arrangement means for shareholders
A scheme of arrangement is a court-approved mechanism through which a company can be acquired. Unlike a traditional takeover bid, where individual shareholders choose whether to accept an offer, a scheme applies to all shareholders collectively if certain approval thresholds are met.
The typical process involves several steps. First, the target company’s board considers whether to recommend the scheme and commissions an independent expert report to assess whether the transaction is in shareholders’ best interests. Shareholders then vote on the scheme at a meeting convened by the court. For a scheme to pass, approval is generally required from a sufficient majority of votes cast. If shareholders approve, the court then considers whether to sanction the scheme. Once court approval is granted and the scheme is implemented, all shareholders receive the agreed consideration automatically — there is no need for individual shareholders to separately decide whether to sell their shares.
For Cleanaway shareholders, this means that if a scheme proceeds, is recommended by the board, and is approved by both shareholders and the court, participation is not optional — all shareholders receive the offer consideration on the same terms. At this stage, however, Cleanaway has confirmed that shareholders do not need to take any action in relation to the Proposal.
What happens next — and what remains uncertain
The immediate next step is the negotiation and execution of an implementation deed, with EQT’s confirmatory due diligence continuing alongside that process. A key date reference for context:
- 3 August 2026: EQT’s non-binding indicative proposal submitted to Cleanaway
- 13 August 2026: Transaction Process Deed announced on ASX
- 17 August 2026: Hard exclusivity period commenced (20 Business Days)
- 14 September 2026: EQT provides written due diligence confirmations; hard exclusivity concludes
Despite the progress signalled by EQT’s confirmations, Cleanaway’s board has been unambiguous about the uncertainty that remains. The company cautioned that there is no certainty that the Proposal will lead to a binding proposal capable of being put to Cleanaway shareholders, or that any transaction will proceed.
No named executive statement was included in this announcement. The above represents the company’s own cautionary language, authorised by Cleanaway’s Board of Directors.
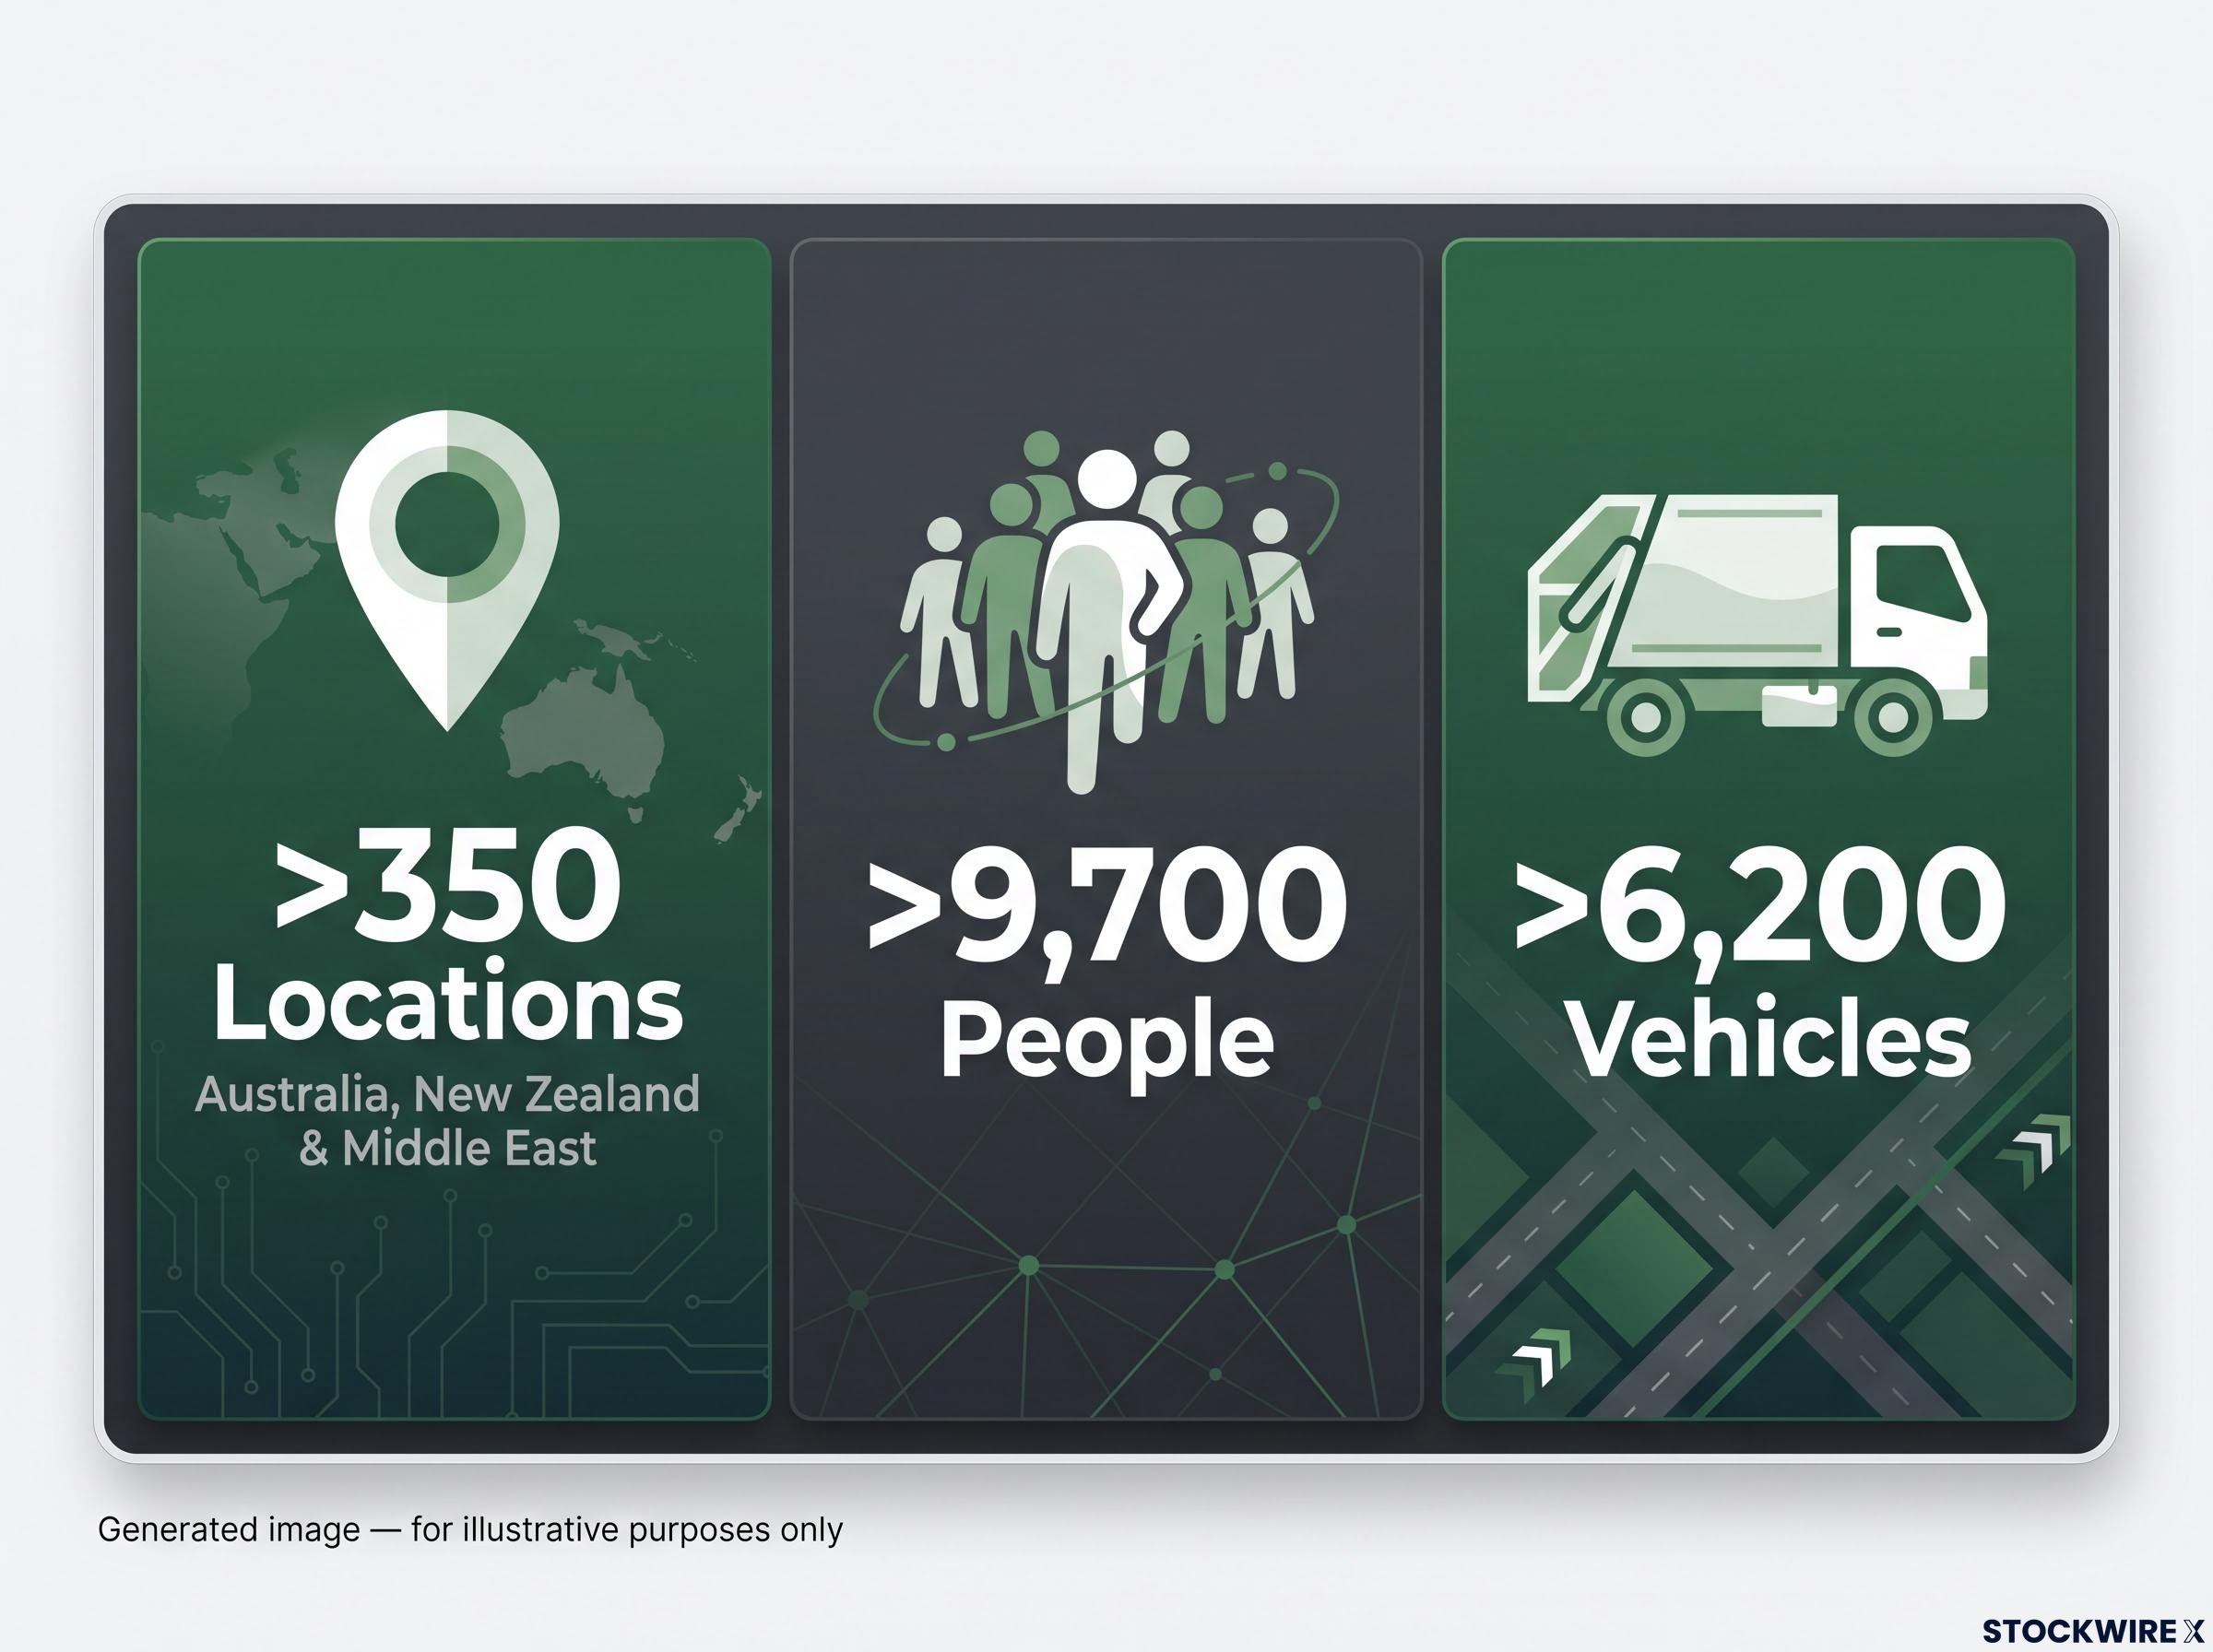
As context for the scale of what is being considered, Cleanaway is Australia’s leading total waste solution provider, operating across more than 350 locations in Australia, New Zealand and the Middle East with a team of more than 9,700 people and a fleet of over 6,200 vehicles.
Cleanaway’s FY26 earnings result showed underlying EBIT growing 14.2% to $470.2 million, with free cash flow surging 63.7% to $213.8 million, providing the financial backdrop against which EQT is conducting its confirmatory due diligence.
Cleanaway has indicated it will provide further updates to the market as appropriate.
Don’t Miss the Next Major ASX Industrials Deal
Big News Blast delivers FREE breaking ASX news directly to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ subscribers who stay ahead of market-moving announcements the moment they drop. Click the “Free Alerts” button at StockWire X to get started today.