
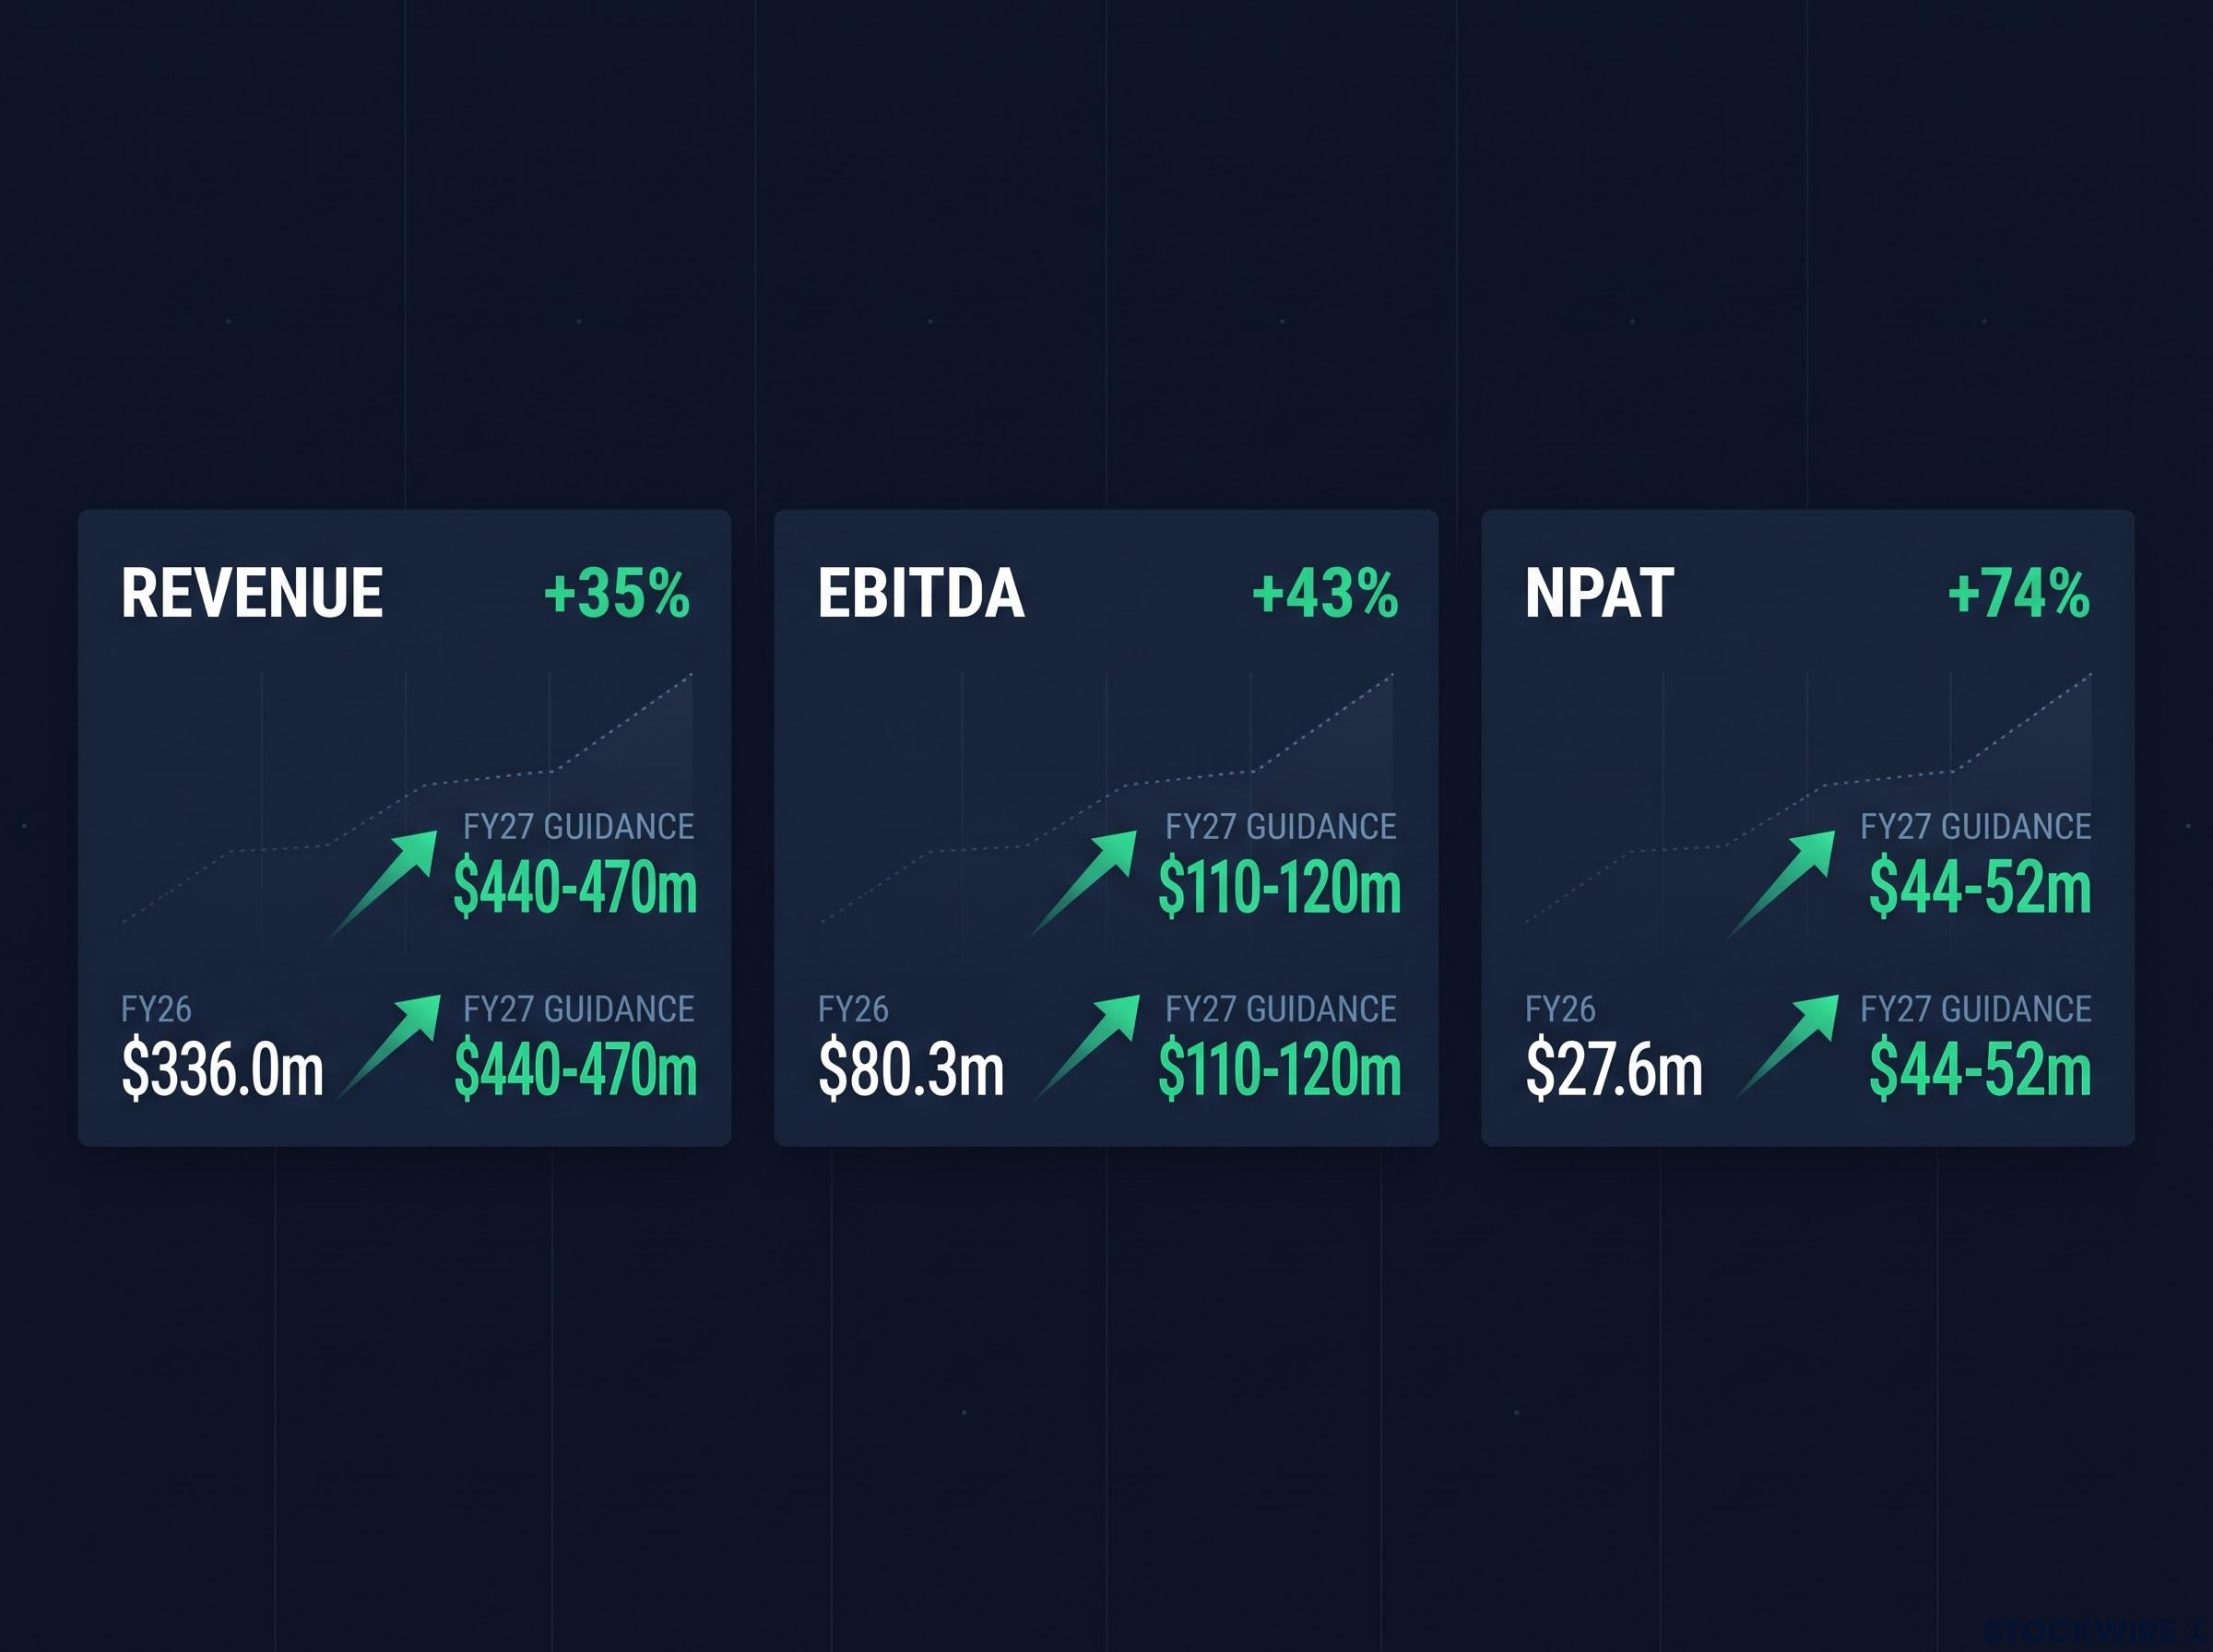
Acrow Limited (ASX: ACF) has upgraded its FY27 guidance, lifting revenue guidance to $440-470 million (previously $410-430 million) and underlying EBITDA guidance to $110-120 million (previously $105-115 million), growth of 43% on FY26 at the mid-point. The company also provided FY27 guidance for underlying EBIT, NPAT and EPS for the first time. Acrow Limited guided to NPAT of $44-52 million, 74% above FY26 at the mid-point.
The 11 November 2026 update covers trading for the first four months of FY27. It was released alongside the CEO’s AGM presentation.
CEO Steven Boland
“FY26 was a year of investment in people, equipment and acquisitions, and FY27 is delivering the return on that investment…”
Guidance upgrade by the numbers
All percentage changes below are based on the mid-point of the guidance ranges. EBIT, NPAT and EPS had no previous guidance, so no earlier range is shown.
| Metric (underlying) | FY26 actual | FY27 previous guidance | FY27 new guidance | % change on FY26 |
|---|---|---|---|---|
| Revenue | $336.0m | $410-430m | $440-470m | +35% |
| EBITDA | $80.3m | $105-115m | $110-120m | +43% |
| EBIT | $51.3m | n/a | $76-87m | +59% |
| NPAT | $27.6m | n/a | $44-52m | +74% |
| EPS | 8.86c | n/a | 10.5-12.3c | +28% |
The first half of FY27 was also adjusted:
- 1H FY27 underlying EBITDA guidance was narrowed upward to $52-55 million (previously $50-55 million), 41% above 1H FY26 at the mid-point.
- 1H FY27 revenue guidance is now $210-220 million (previously $195-215 million).
When big ASX news breaks, our subscribers know first
What is driving the upgrade
On the basis of trading to date, the order book and current market conditions, the Board upgraded the guidance. The company said the upgrade reflects three factors:
- Stronger than anticipated organic growth in Industrial Access, including an expanded scope on both the Snowy 2.0 scaffold contract and the Perdaman contract, and continued growth in maintenance and shutdown activity.
- A continued recovery in Queensland formwork activity and cross-selling of the Company’s Jumpform, Screens and SuperDeck® fleets.
- The contribution of AusGroup Industrial Services (AGIS) from 1 September 2026, with integration proceeding to plan.
Trading update for the first four months
The upgraded forecast reflects continued organic growth in the first quarter across both the Industrial Access and Construction Services divisions. It also includes a full quarter of contribution from the SuperDeck® business and one month from AGIS, following completion of the acquisition effective 1 September 2026.
The path to that contribution ran through regulatory approval for AGIS, which cleared its last hurdle with no review application lodged, removing deal risk ahead of the September completion.
Formwork activity in Queensland has continued to recover from the improvement seen in the second half of FY26. Industrial maintenance and shutdown activity remains strong across the company’s eastern seaboard and Western Australian operations.
Understanding guidance upgrades and what drives them
Companies often guide to a few headline numbers, and each one measures a different layer of profit. EBITDA is earnings before interest, tax, depreciation and amortisation, a measure of operating earnings before financing costs and the write-down of assets over time.
EBIT is earnings before interest and tax, so it takes depreciation and amortisation into account. NPAT is net profit after tax, the profit left after all costs, interest and tax. EPS, or earnings per share, divides that profit by the number of shares on issue.
Acrow’s earlier FY27 guidance covered revenue and underlying EBITDA. Adding EBIT, NPAT and EPS extends the guidance to the profit measures that sit below EBITDA.
Management’s initial FY27 targets, set in April on the back of record monthly contract wins and a record hire revenue pipeline, have since been lifted twice.
The Board said its upgrade was based on trading to date, the order book and current market conditions.
Capital expenditure and balance sheet outlook
Acrow continues to budget for capital expenditure of $30.0 million in FY27, down from $36.5 million in FY26. The budget is unchanged from the previous update.
Net debt/EBITDA is expected to reduce to approximately 1.3 times at 30 June 2027, from 1.6 times at 30 June 2026 (pro-forma for the FY26 acquisitions). The company attributed the expected reduction to earnings growth and the reduced capital expenditure programme.
Net debt excludes lease liabilities, and EBITDA is underlying EBITDA less lease principal repayments, consistent with prior reporting.
Boland said four months into the year both divisions are growing organically, and that the pipeline across industrial maintenance, Queensland construction and national infrastructure continues to build. He added:
CEO Steven Boland
“…the business is positioned for sustained earnings and cash flow growth.”
Want Alerts Like This on the Industrials Stocks You Follow?
StockWire X Market Intelligence scores every announcement in our coverage for how significant it’s likely to be for investors, and which way it points, then alerts you on the stocks you follow. The first 1,000 founding members lock in 50% off for life: A$247 a year instead of the standard A$495. Join the founding waitlist today.