
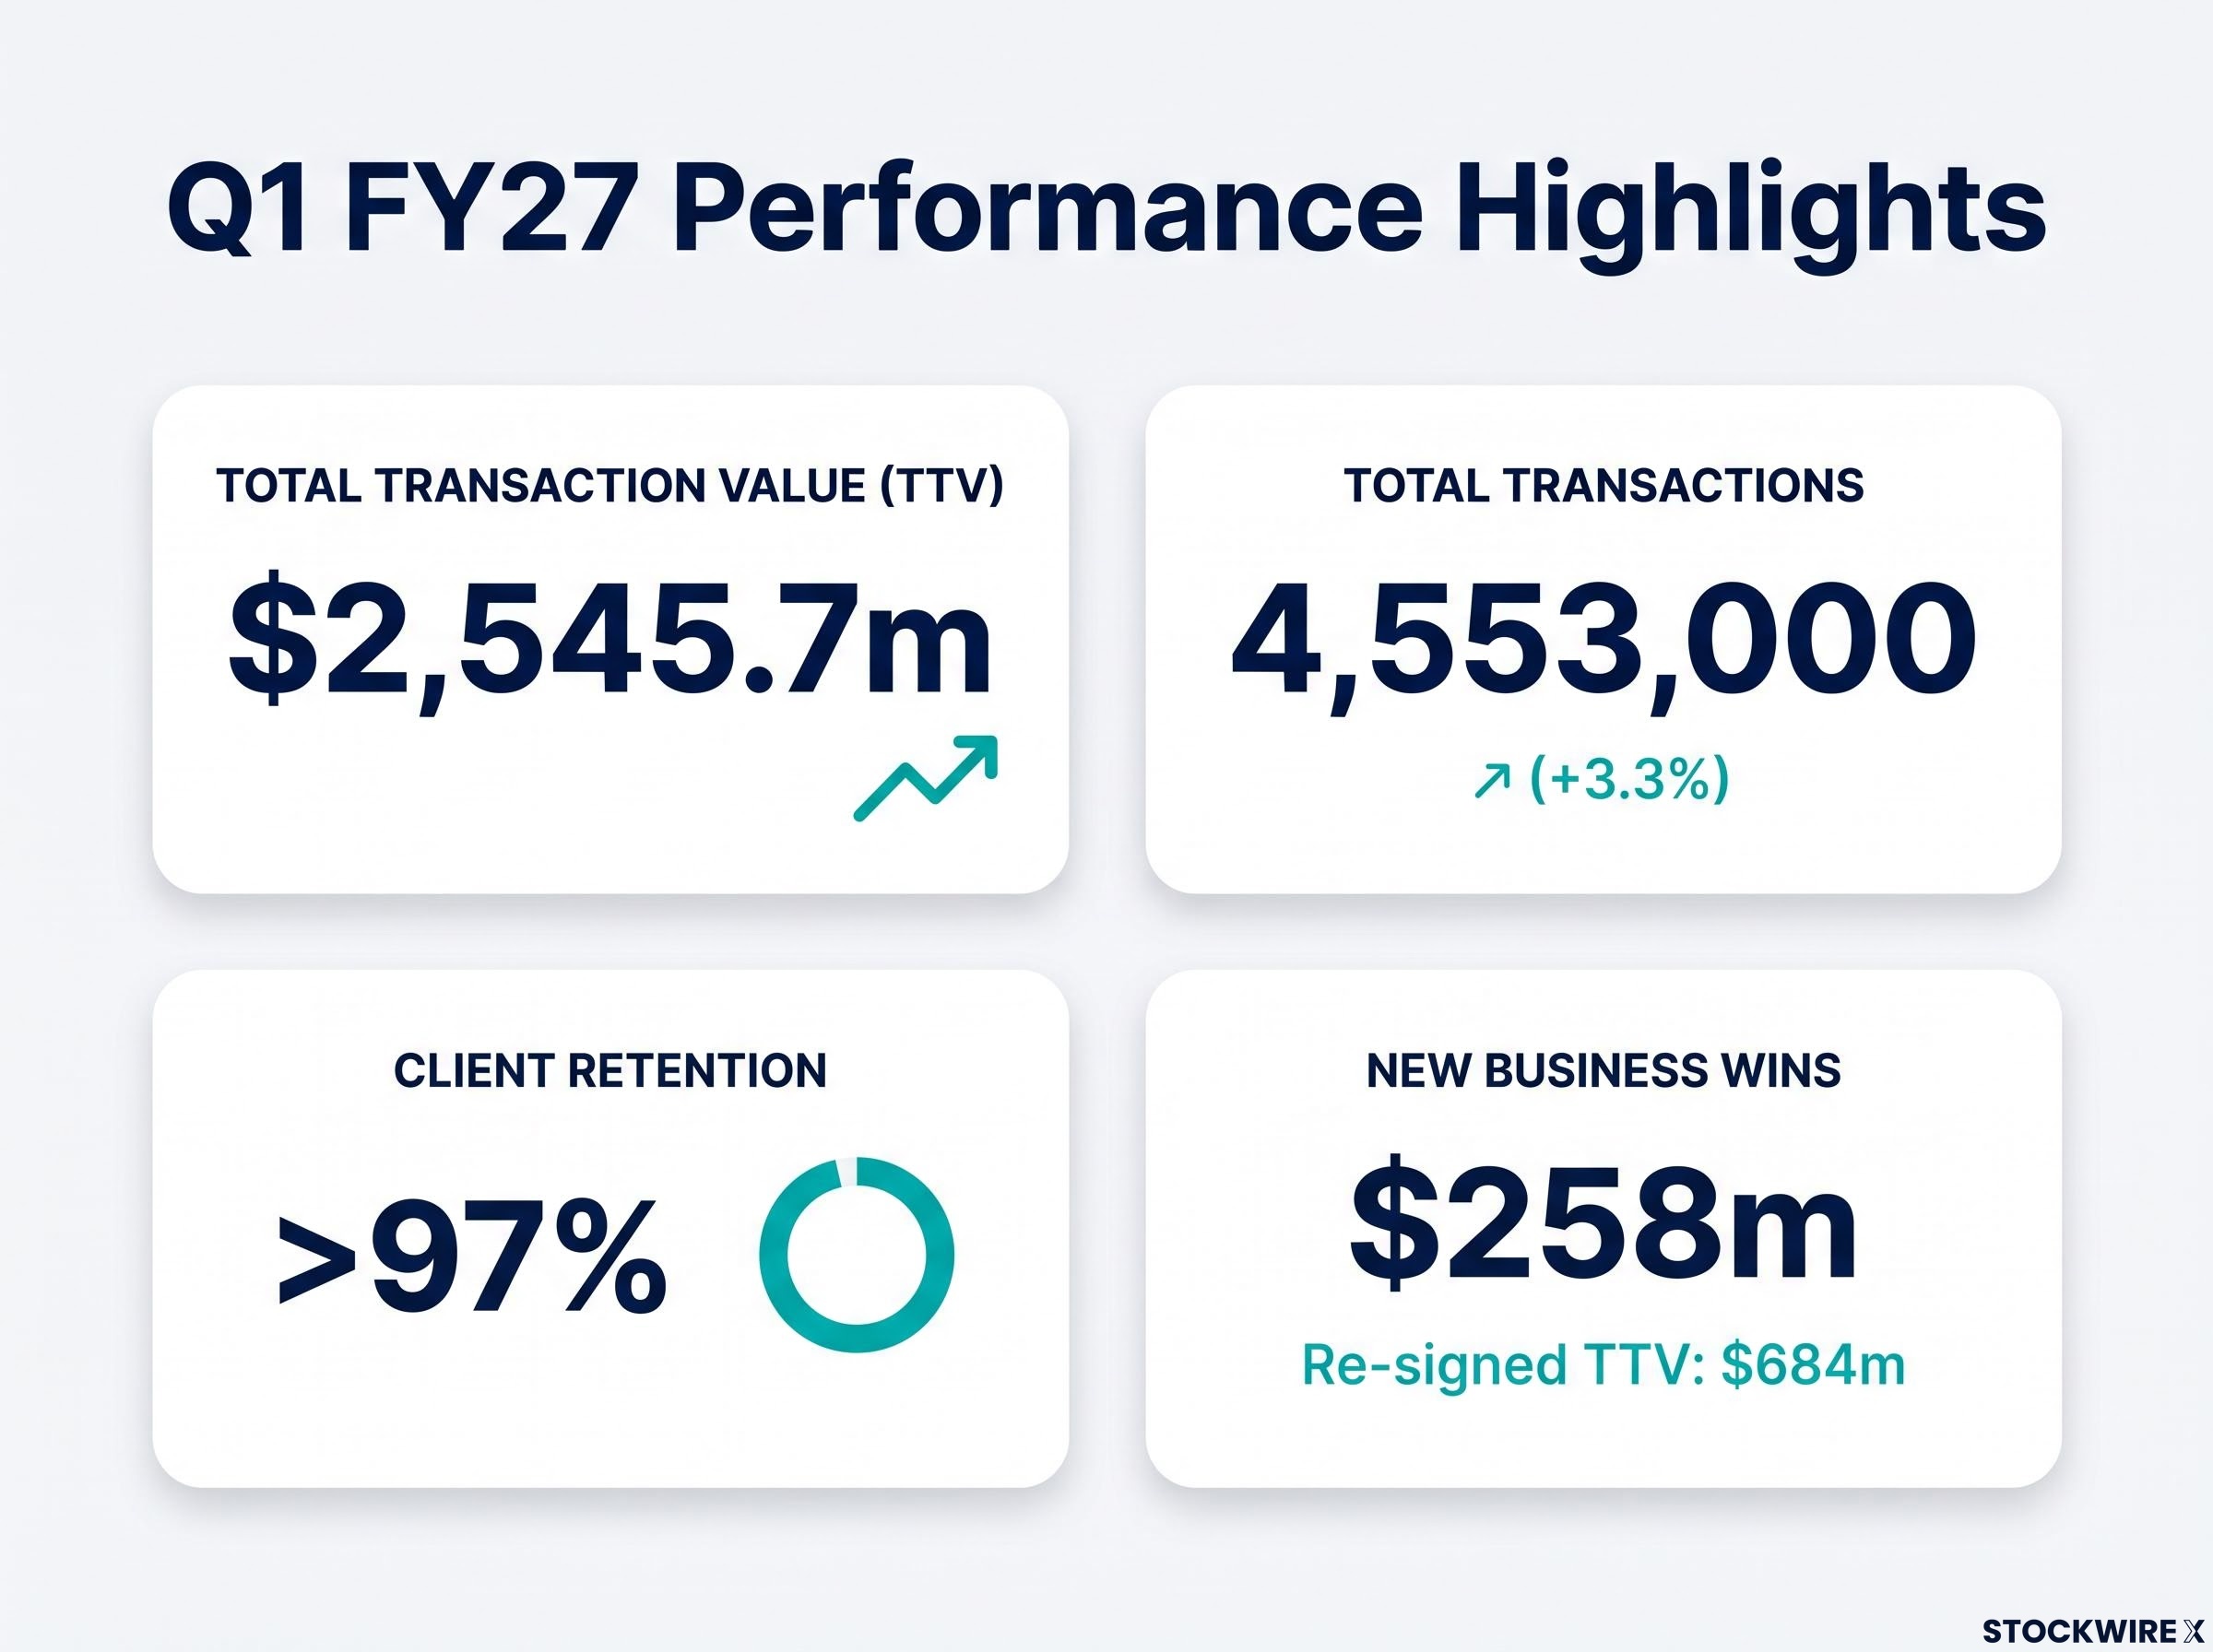
In its Q1 FY27 update on business performance, Corporate Travel Management (CTM) reported total transaction value (TTV) of $2,545.7m for the first quarter ended 30 September 2026. Revenue / TTV margin was 6.2%, and transactions rose 3.3% to 4,553,000.
Year-to-date (YTD) figures cover 1 July 2026 to 6 November 2026. Share trading recommenced on the ASX on 3 September.
Q1 FY27 highlights: $2.5bn TTV and client retention above 97%
The YTD commercial picture centred on customer retention and new business. Management said continued engagement by the sales team, supported by better conversations from September, led to the following results:
- Client retention (TTV) of more than 97%
- New business wins of $258m
- Re-signed TTV of $684m
Managing Director & Group CEO Ana Pedersen pointed to the stability of Group-wide TTV and to the company’s focus on customers.
Ana Pedersen, Managing Director & Group CEO
“Despite global headwinds, Group-wide TTV has remained stable. This provides a strong base for CTM over the next three-to-five years…”
She added that the focus in the First Quarter had been on strengthening customer relationships and positioning CTM for sustainable long-term growth, “rather than maximising short-term earnings at the expense of future performance.”
When big ASX news breaks, our subscribers know first
Financial performance and regional drivers
Q1 FY27 versus Q1 FY26
Revenue and underlying EBITDA declined year on year, even as transactions grew. The table below sets out the unaudited consolidated performance, including the change assuming constant currency.
| Metric | Q1 FY27 | Q1 FY26 | % change | % change in constant currency |
| Transactions (‘000) | 4,553 | 4,409 | +3.3% | n/a |
| TTV (A$m) | 2,545.7 | 2,645.8 | -3.8% | +1.9% |
| Revenue (A$m) | 158.3 | 173.0 | -8.5% | -3.4% |
| Revenue / TTV margin | 6.2% | 6.5% | (30 bps) | (30 bps) |
| Underlying EBITDA (A$m) | 23.5 | 37.6 | -37.5% | -33.6% |
Revenue and underlying EBITDA exclude the GBP15.3m ($28.9m) accounting gain related to customer liability settlement adjustments. That gain will be included in the full year statutory result.
What drove the result
CTM attributed the movement in TTV and revenue to differing conditions across its regions:
- North America: Transaction volumes remained broadly flat while TTV increased, largely reflecting higher airfares. Higher domestic airfares lifted TTV without a proportionate increase in commission and supplier incentive revenue.
- ANZ: Lower transaction volumes reduced TTV and revenue, and underlying revenue / TTV margin declined compared with the prior year.
- UK/EU: Lower hotel accommodation activity associated with UK special projects reduced TTV and revenue. The impact was partially offset by improved margins on individual customer contracts.
Underlying EBITDA fell to $23.5m, which the company said reflected lower revenue, increased regional operating costs (particularly in the UK) and higher Group costs. Adverse exchange rate movements also affected earnings in Australian dollar terms.
CTM said it is focused on addressing these factors, identifying additional revenue opportunities, and driving productivity and cost improvements to support margin growth over time.
Balance sheet, settlements and IATA release
CTM held cash and cash equivalents of $116m at 30 September 2026. Debt of $75m has been drawn under the PEP financing facility as the company continues to progress remediation activities.
The International Air Transport Association (IATA) released its $65m security guarantee in October 2026 and restored CTM’s previous settlement cycles. This is expected to reduce working capital requirements by approximately $30m.
IATA’s decision followed the successful completion of its latest financial assessment of CTM, and the settlement arrangements it replaced had been put in place on a temporary basis while the FY25 financial statements were being finalised.
On customer related liabilities, CTM made payments totalling $66m during the First Quarter, in line with agreed payment schedules under final settlement agreements. That represents 33% of the $198m UK settlement liabilities recognised at 30 June 2026.
Settlement adjustment gains of GBP15.3m have been realised to date through the ongoing settlement processes. CTM said it continues to engage constructively with other affected customers to progress outstanding settlements.
FY27 cost and investment expectations
CTM outlined the following expectations for FY27:
- Corporate costs are expected to be around $39m, with continued investment in the Governance Uplift Program, technology and people.
- Capital expenditure is expected to range between $30m and $35m, supporting technology and platform development. A key initiative is CTM One, the next generation global travel management platform, integrating AI, predictive intelligence and automation.
- Non-recurring costs of around $25m are expected, including costs related to remediation activities, governance uplift, audit completion and certain one-off back-office projects.
- Cash tax payments are expected to be minimal, due to retained tax losses, with an effective tax rate of approximately 20% for the year.
Want Alerts Like This on the Consumer Discretionary Stocks You Follow?
StockWire X Market Intelligence scores every announcement in our coverage for how significant it’s likely to be for investors, and which way it points, then alerts you on the stocks you follow. The first 1,000 founding members lock in 50% off for life: A$247 a year instead of the standard A$495. Join the founding waitlist today.