

Tower lifts FY26 underlying NPAT guidance to $69m–$79m
Tower Limited (NZX/ASX: TWR) has revised its Tower FY26 guidance, now expecting underlying NPAT of between $69m and $79m for the year to 30 September 2026. The announcement is dated 6 October 2026, and the figures are based on preliminary, unaudited results.
The new range compares with previous guidance of $55m to $65m. According to the company, the uplift reflects the large event allowance of $45m not being fully utilised during the year.
Full details are due with the financial results announcement on 26 November. The upgrade stems from lower-than-allowed large event costs, not from a stated change in the underlying business.
| Metric | Previous guidance | Updated guidance | Change |
|---|---|---|---|
| FY26 underlying NPAT range | $55m to $65m | $69m to $79m | $14m uplift at both ends of the range |
| Large event allowance vs. actual | $45m allowance, assumed fully utilised | Large event claim costs of around $25m recorded | Unused allowance of around $20m |
When big ASX news breaks, our subscribers know first
How the large event allowance drove the upgrade
What is a large event allowance?
Insurers typically set aside an allowance to cover claims from major weather or catastrophe events. When actual claims come in below that allowance, the unused amount flows through to profit.
The announcement does not detail how Tower’s large event allowance is calculated.
The numbers behind the uplift
Tower’s earlier guidance assumed the full utilisation of the FY26 large event allowance. The announcement sets out the following figures:
- FY26 large event allowance: $45m.
- Large event claim costs recorded: around $25m.
- Unused allowance: around $20m.
- Underlying NPAT uplift: $14m ($20m less tax).
Because the uplift stems from claim costs running below the allowance, investors may view it as a favourable outcome rather than a permanently higher run-rate. Tower described the expected FY26 result as a return to a more typical earnings profile after the unusually favourable weather conditions and claims experience of FY25, which it called an exceptionally strong year.
Tower’s HY26 earnings results showed underlying NPAT of $36.8m, down 40% on the prior period, with elevated weather claims weighing on the first half before the full-year large event outcome came in lighter than allowed.
Reported profit will continue to be affected by non-underlying costs, including further customer remediation programme costs incurred in the second half. No amounts were disclosed.
Customer growth and pricing support the portfolio
Alongside the guidance revision, Tower reported customer and premium trends for the year:
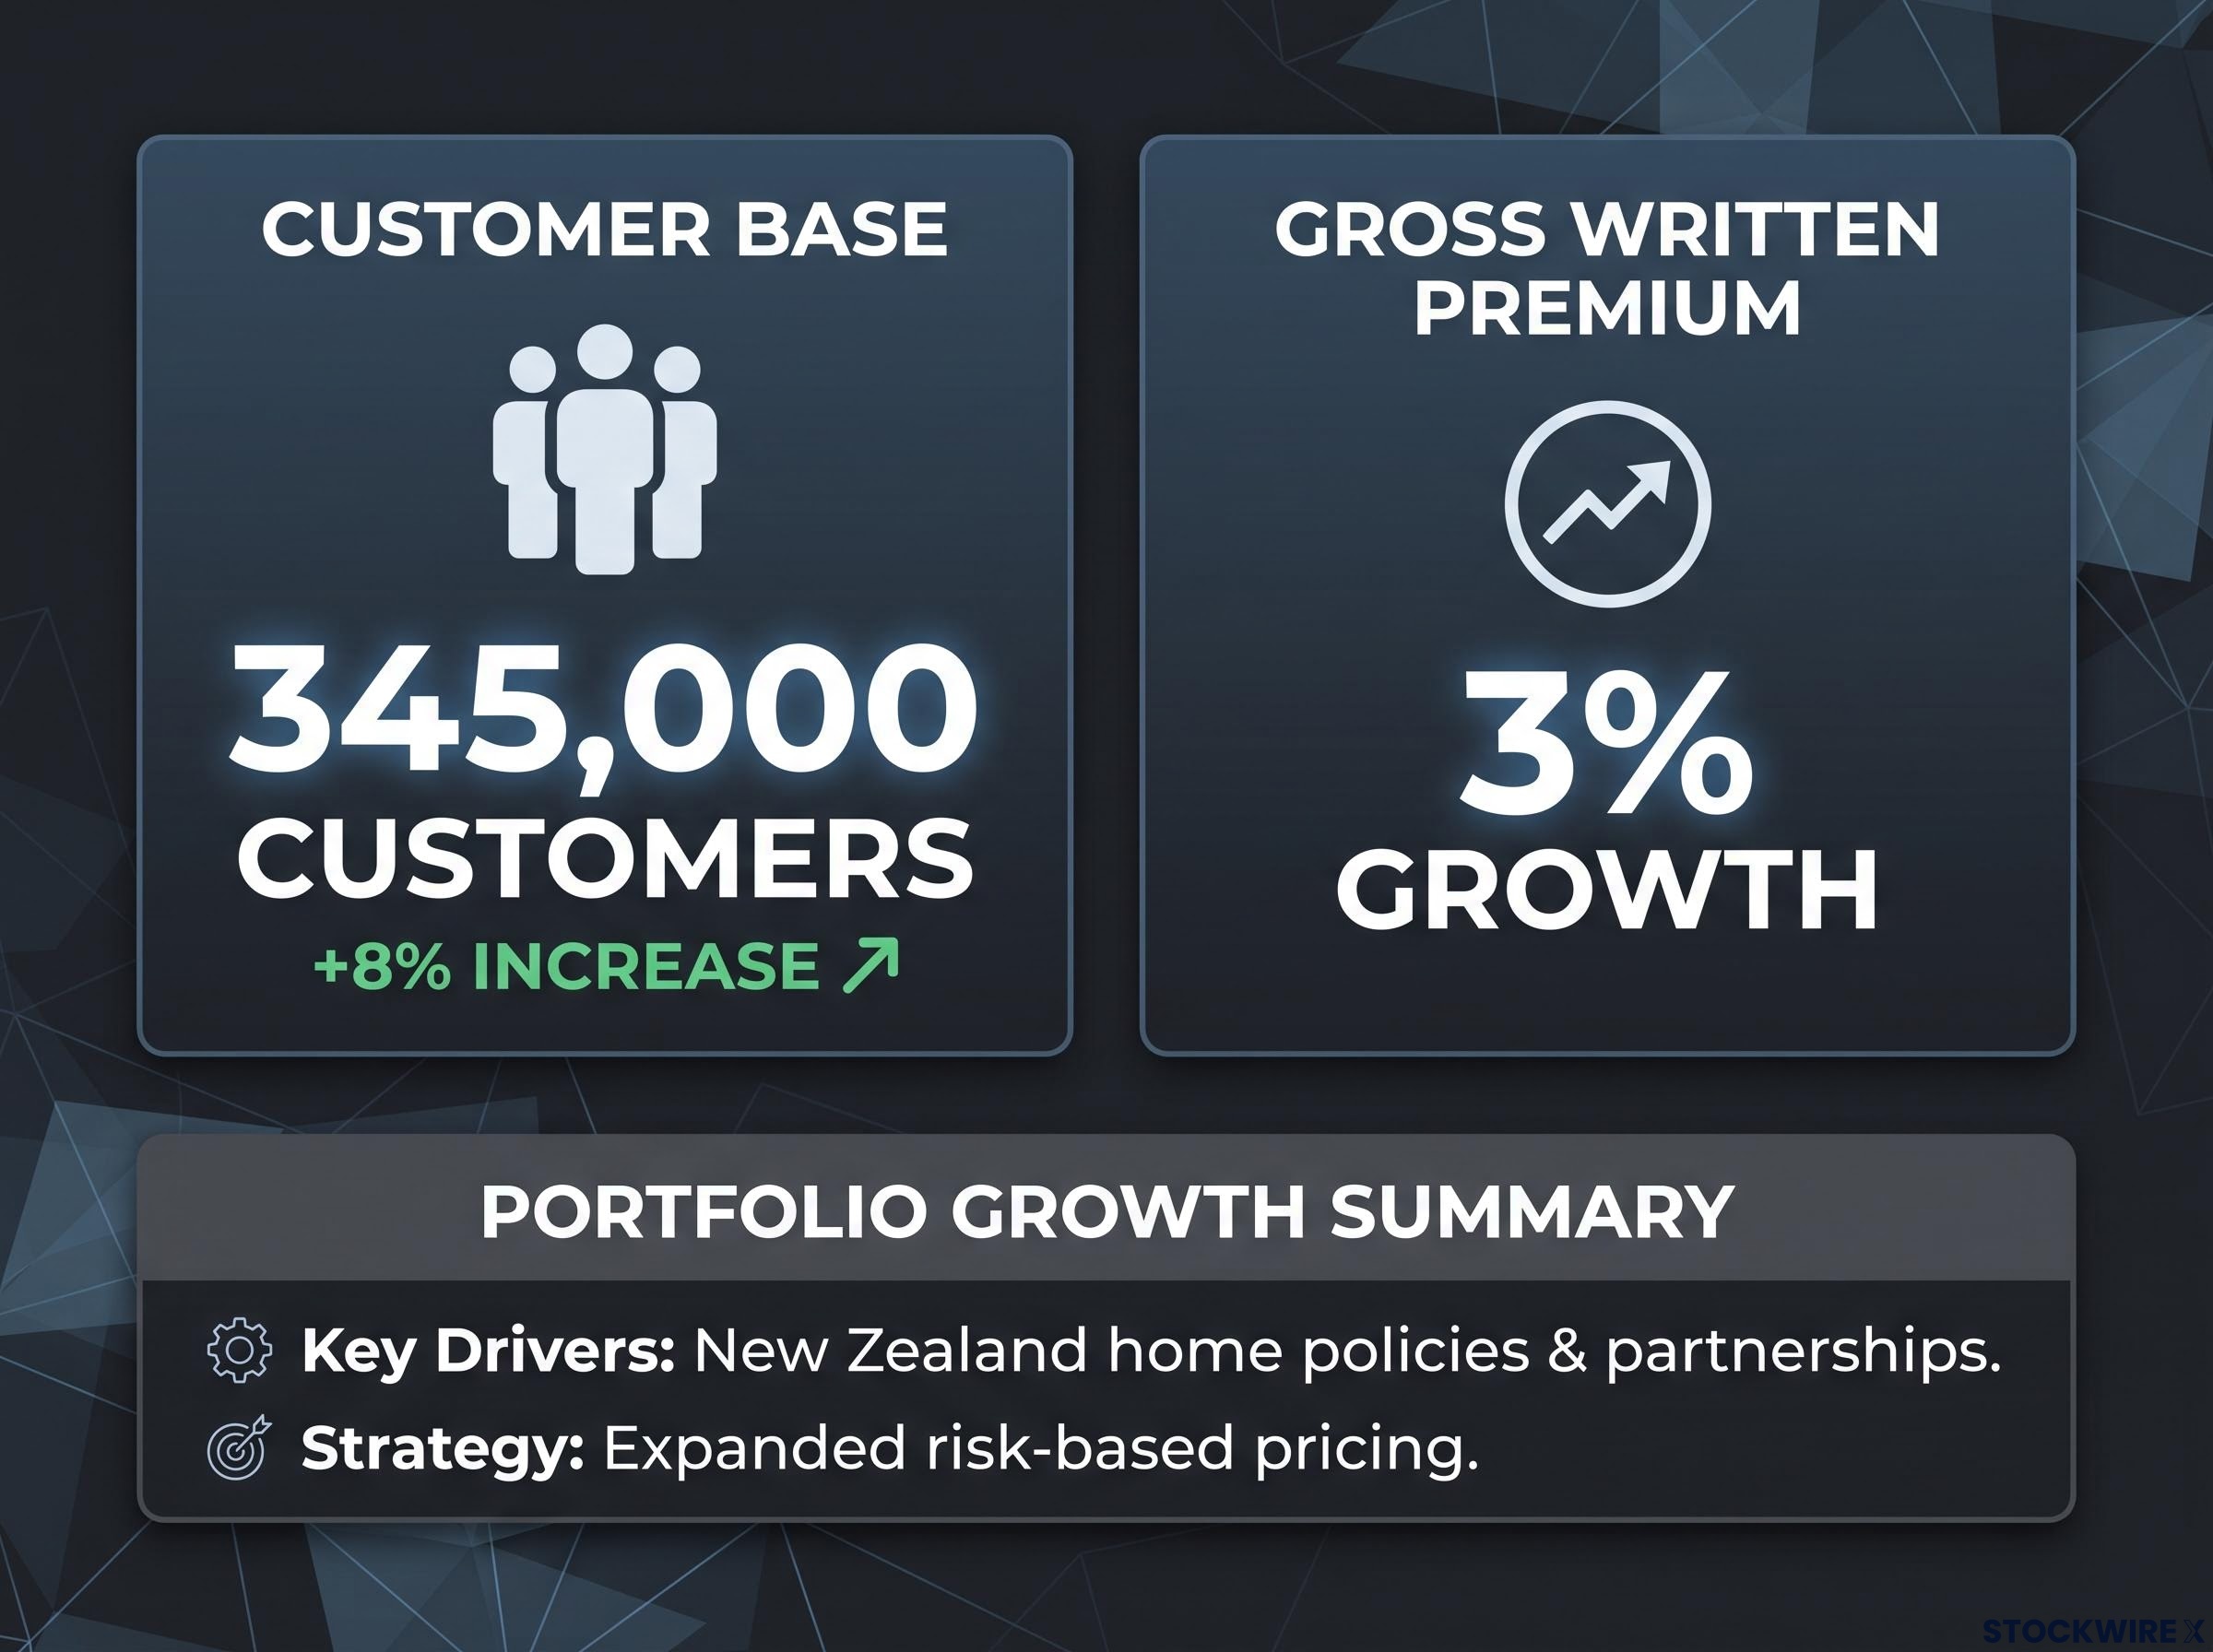
- Customer numbers increased by 8% in the year to 345,000 customers.
- Growth was driven primarily by New Zealand home insurance policies and by new and existing partnerships delivering scale.
- Gross written premium (GWP) growth of 3% was in line with guidance of low single digit growth.
- Competitive pricing is supporting customer affordability and growth, while expanded risk-based pricing is strengthening portfolio quality and reducing exposure to weather-related impacts.
Customer growth paired with GWP growth in line with guidance points to added scale alongside a focus on portfolio quality.
Key takeaway
Tower’s FY26 underlying NPAT guidance has lifted by $14m at both ends of the range, to $69m to $79m, based on preliminary, unaudited results. The announcement was authorised by Paul Johnston, Chief Executive Officer, Tower Limited.
What investors should watch next
Tower will release full details of its FY26 performance with its financial results announcement on 26 November. The announcement does not provide FY27 guidance or dividend commentary.
Points to watch in that release include:
- The audited underlying NPAT result against the new $69m to $79m range.
- The size of the non-underlying costs, including customer remediation programme costs.
- The reported profit outcome.
Get Financials News Before the Market Moves
Join 20,000+ investors receiving FREE breaking ASX alerts within minutes of release, complete with in-depth analysis of the full announcement. Click the “Free Alerts” button at Big News Blast to stay ahead of the next market-moving update in financials, tech, healthcare and beyond.