
September 2026 update: 7.65% distribution rate and 98% of loans performing
The Qualitas Real Estate Income Fund (ASX:QRI) recorded a current month distribution of 7.65% p.a. on NAV ($0.010060/unit) in its September 2026 performance update. The Manager confirmed that 98% of total QRI loans were Performing Loans as at 30 September 2026.
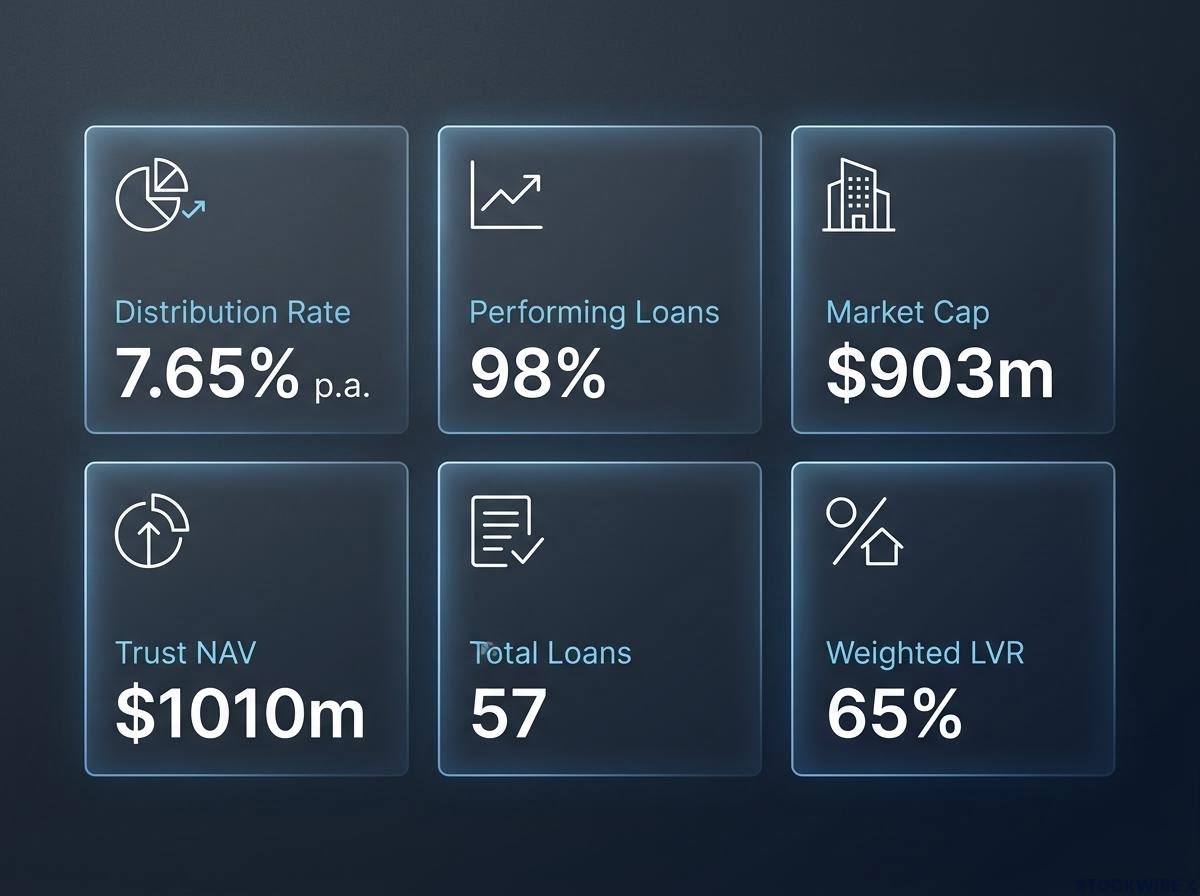
Key figures from the update:
- Market cap: $903m
- Trust NAV: $1010m
- Unit price: $1.430
- Unit NAV: $1.6001
- Total loans: 57
- Weighted loan maturity: 0.94 years
- Fund gearing: 0%
- Weighted LVR: 65%
- Interest exposure: 100% floating
The Manager said distributions for August and September were weighed on by higher cash balances, reflecting timing differences between loan repayments and deployment. It has identified an increasing number of mid-market opportunities offering sound risk-adjusted returns consistent with the Fund’s objectives, as some financiers have imposed redemption restrictions on their funds.
QRI’s available cash is expected to be deployed into these opportunities over the coming months. Distributions are expected to increase as deployment progresses.
Net returns against the RBA cash rate
The Fund’s net return exceeded the RBA cash rate across every period reported. The table below reproduces the source figures.
| Period | Net return (%) | RBA cash rate (%) | Spread to RBA (%) |
|---|---|---|---|
| 1 month | **0.63** | **0.36** | **0.27** |
| 3 months | **1.98** | **1.10** | **0.88** |
| 6 months | **3.94** | **2.16** | **1.80** |
| 1 year | **7.45** | **4.00** | **3.46** |
| 3 years | **7.88** | **4.13** | **3.75** |
| Since inception | **7.22** | **2.32** | **4.87** |
The Fund’s target return is the RBA cash rate plus 5.0% to 6.5% p.a. (net). Past performance is not a reliable indicator of future performance.
When big ASX news breaks, our subscribers know first
Inside the portfolio: how QRI’s loan book is built
QRI is classified under the S&P Global Industry Classification Standard (GICS) as a Mortgage Real Estate Investment Trust. In plain terms, the Fund lends against real estate and aims to pay monthly income from interest on those loans.
Ranking determines who is repaid first. Senior loans are secured by a first ranking mortgage. Senior subordinated loans are subordinated in repayment priority to the senior financier under a common first ranking debt facility but rank ahead of any mezzanine facility. Mezzanine loans are secured by a second ranking mortgage and are subordinated to the senior loan.
By ranking, 95% of the portfolio sits in senior loans, made up of first ranking loans (79%) and senior subordinated loans (16%). Mezzanine loans make up the remaining 5%.
| Loan type | Number of loans | Total loan amount | Weighted avg. gross return | Weighted avg. LVR |
|---|---|---|---|---|
| Senior investment | **32** | **$361m** | **9.6%** | **61%** |
| Senior land | **19** | **$288m** | **10.6%** | **65%** |
| Senior construction | **4** | **$195m** | **10.1%** | **69%** |
| Mezzanine | **2** | **$46m** | **12.2%** | **72%** |
The weighted average gross return includes interest income earned on undrawn cash balances associated with loan commitments. LVR, or loan-to-value ratio, compares the loan amount with the value of the property securing it.
Geography and property sector
By geography, the portfolio is spread as follows:
- NSW: 55%
- QLD: 21%
- VIC: 20%
- SA: 3%
- ACT: 1%
By property sector:
- Residential: 63%
- Commercial: 21% (including 5.6% in hotels and 15.4% in office)
- Industrial: 12%
- Retail: 4%
Sponsor concentration and distribution funding
The top 10 sponsor group exposures are shown on a look-through and committed basis. The largest is $106.6m, or 10.6% of Trust NAV. Exposures 1 and 2 are each made up of 4 separate loan positions with no cross-collateralisation.
Gross income of 9.41% p.a., less management fees (1.54%) and fund costs (0.25%), plus an income reserve (0.03%), equals the 7.65% distribution. Of the distribution, 70% was derived from cash income from investments and 30% from other sources.
The Fund’s March 2026 distribution increase to 7.25% annualised followed the completion of a large repositioning capital loan, showing how individual loan settlements and deployment timing can move the monthly payout in either direction.
Portfolio health: enforcement action on two loans
The portfolio health data shows 98% of loans as Performing Loans, the same share as in August 2026. Two Non-Performing Loans are now subject to Enforcement action, equal to 2% of loans. They are the same two cross-collateralised loans to the same borrower that were flagged as in Payment Default in the previous report.
The Manager had determined not to extend the two loans and had been monitoring the borrower’s progress with a refinancing proposal. It has now demanded full repayment of both loans and appointed a controller over one of the security properties.
The controller has engaged selling agents, and the property is now subject to a formal sales campaign. The Manager considers Enforcement the most appropriate action to protect the Fund’s interest and seek full repayment. It said the action does not in itself indicate further deterioration in the underlying assets or that a credit loss has been incurred.
The Manager said an adequate equity buffer remains between the anticipated selling price range of the property and the loans, based on an independent valuation it holds plus advice from various selling agents.
No impairments were recorded in the 12 months to September 2026. Four loans, including the two under Enforcement, represent less than 3% of total QRI loans and are subject to heightened monitoring under the Fund’s risk management framework.
Interest remained overdue on one of the two loans at the reporting date. Separately, the portfolio has one loan with a $0.2m arrears balance in the 30 to 60 day bracket. The controller has collected property income, which is expected to be applied towards outstanding interest after payment of applicable costs and expenses. Any remaining unpaid interest will continue to accrue.
The performing share of loans moved as follows:
- 100% from October 2025 to June 2026
- 99% in July 2026
- 98% in August and September 2026
What happens next for QRI
Three items are scheduled or expected:
- Enforced loan sales process: The sales process, inclusive of settlement and repayment of both loans, is expected to complete within the next four months, subject to market conditions and settlement timing. The controller manages the campaign.
- Cash deployment: Available cash is expected to be deployed into mid-market opportunities over the coming months, with distributions expected to increase as deployment progresses.
- Investor webinar: Andrew Schwartz, Group Managing Director and Co-Founder, and Mark Power, Head of Income Credit, will host a live update on the Qualitas Real Estate Income Fund (ASX:QRI) on Thursday, 29 October.
Don’t Miss the Next Financials Mover on the ASX
Join 20,000+ investors getting FREE breaking ASX news delivered to their inbox within minutes of release, complete with in-depth analysis. Click the “Free Alerts” button at Big News Blast to receive financials updates the moment market-moving announcements break and stay ahead of the market.