
Q1 FY27 highlights: revenue of A$4.2m in line with normalised pcp, US TTV up 15%
In its Q1 FY27 quarterly business update for the quarter ended 30 September 2026, QuickFee Limited reported revenue of $4.2 million, in line with the normalised previous corresponding period (pcp). The normalised comparison excludes US Pay Now, which was sold effective 9 September 2025.
The FY26 full-year results showed how that sale reshaped the cost base, with operating expenses falling sharply and QuickFee posting its first full-year profit before the divestment gain.
Reported Group revenue was down 29% against the reported pcp of $5.9 million, reflecting the Pay Now disposal. AU Finance revenue rose 6% to $3.2 million, while US Finance revenue fell 10% to US$0.5 million. US Finance total transaction value (TTV) rose 15% to US$5.5 million.
QuickFee also revised its FY27 EBTDA guidance to a range of $4.5 million – $5.0 million. The company cited solid growth potential in the US in H2 FY27, partially offset by softer AU fee funding originations.
Key points from the quarter:
- Quarterly revenue of $4.2 million, in line with normalised pcp
- AU Finance revenue up 6% to $3.2 million
- US Finance TTV up 15% to US$5.5 million, driven by existing customers
- AU TTV down 4% to $15.0 million, with a low lending default rate maintained
- AU disbursement funding TTV expected to remain strong
| Metric | Q1 FY27 | Q1 FY26 | Movement |
|---|---|---|---|
| US Finance revenue | US$0.5M | US$0.6M | -10% |
| AU Finance revenue | $3.2M | $3.0M | +6% |
| Reported Group revenue | $4.2M | $5.9M | -29% |
| US Finance TTV | US$5.5M | US$4.8M | +15% |
| AU Finance TTV | $15.0M | $15.6M | -4% |
Bruce Coombes, Chief Executive Officer
“QuickFee has a differentiated position in the market as a low-risk B2B lender… The disbursement funding business continues to perform well and now accounts for 50% of the Australian loan book.”
When big ASX news breaks, our subscribers know first
Australia: disbursement funding growth offsets softer fee funding
AU TTV declined 4% to $15.0 million (Q1 FY26: $15.6 million), yet AU Finance revenue rose 6%. The lending market softened in Australia due to multiple factors including multiple interest rate rises and federal budget activity.
Fee funding versus disbursement funding
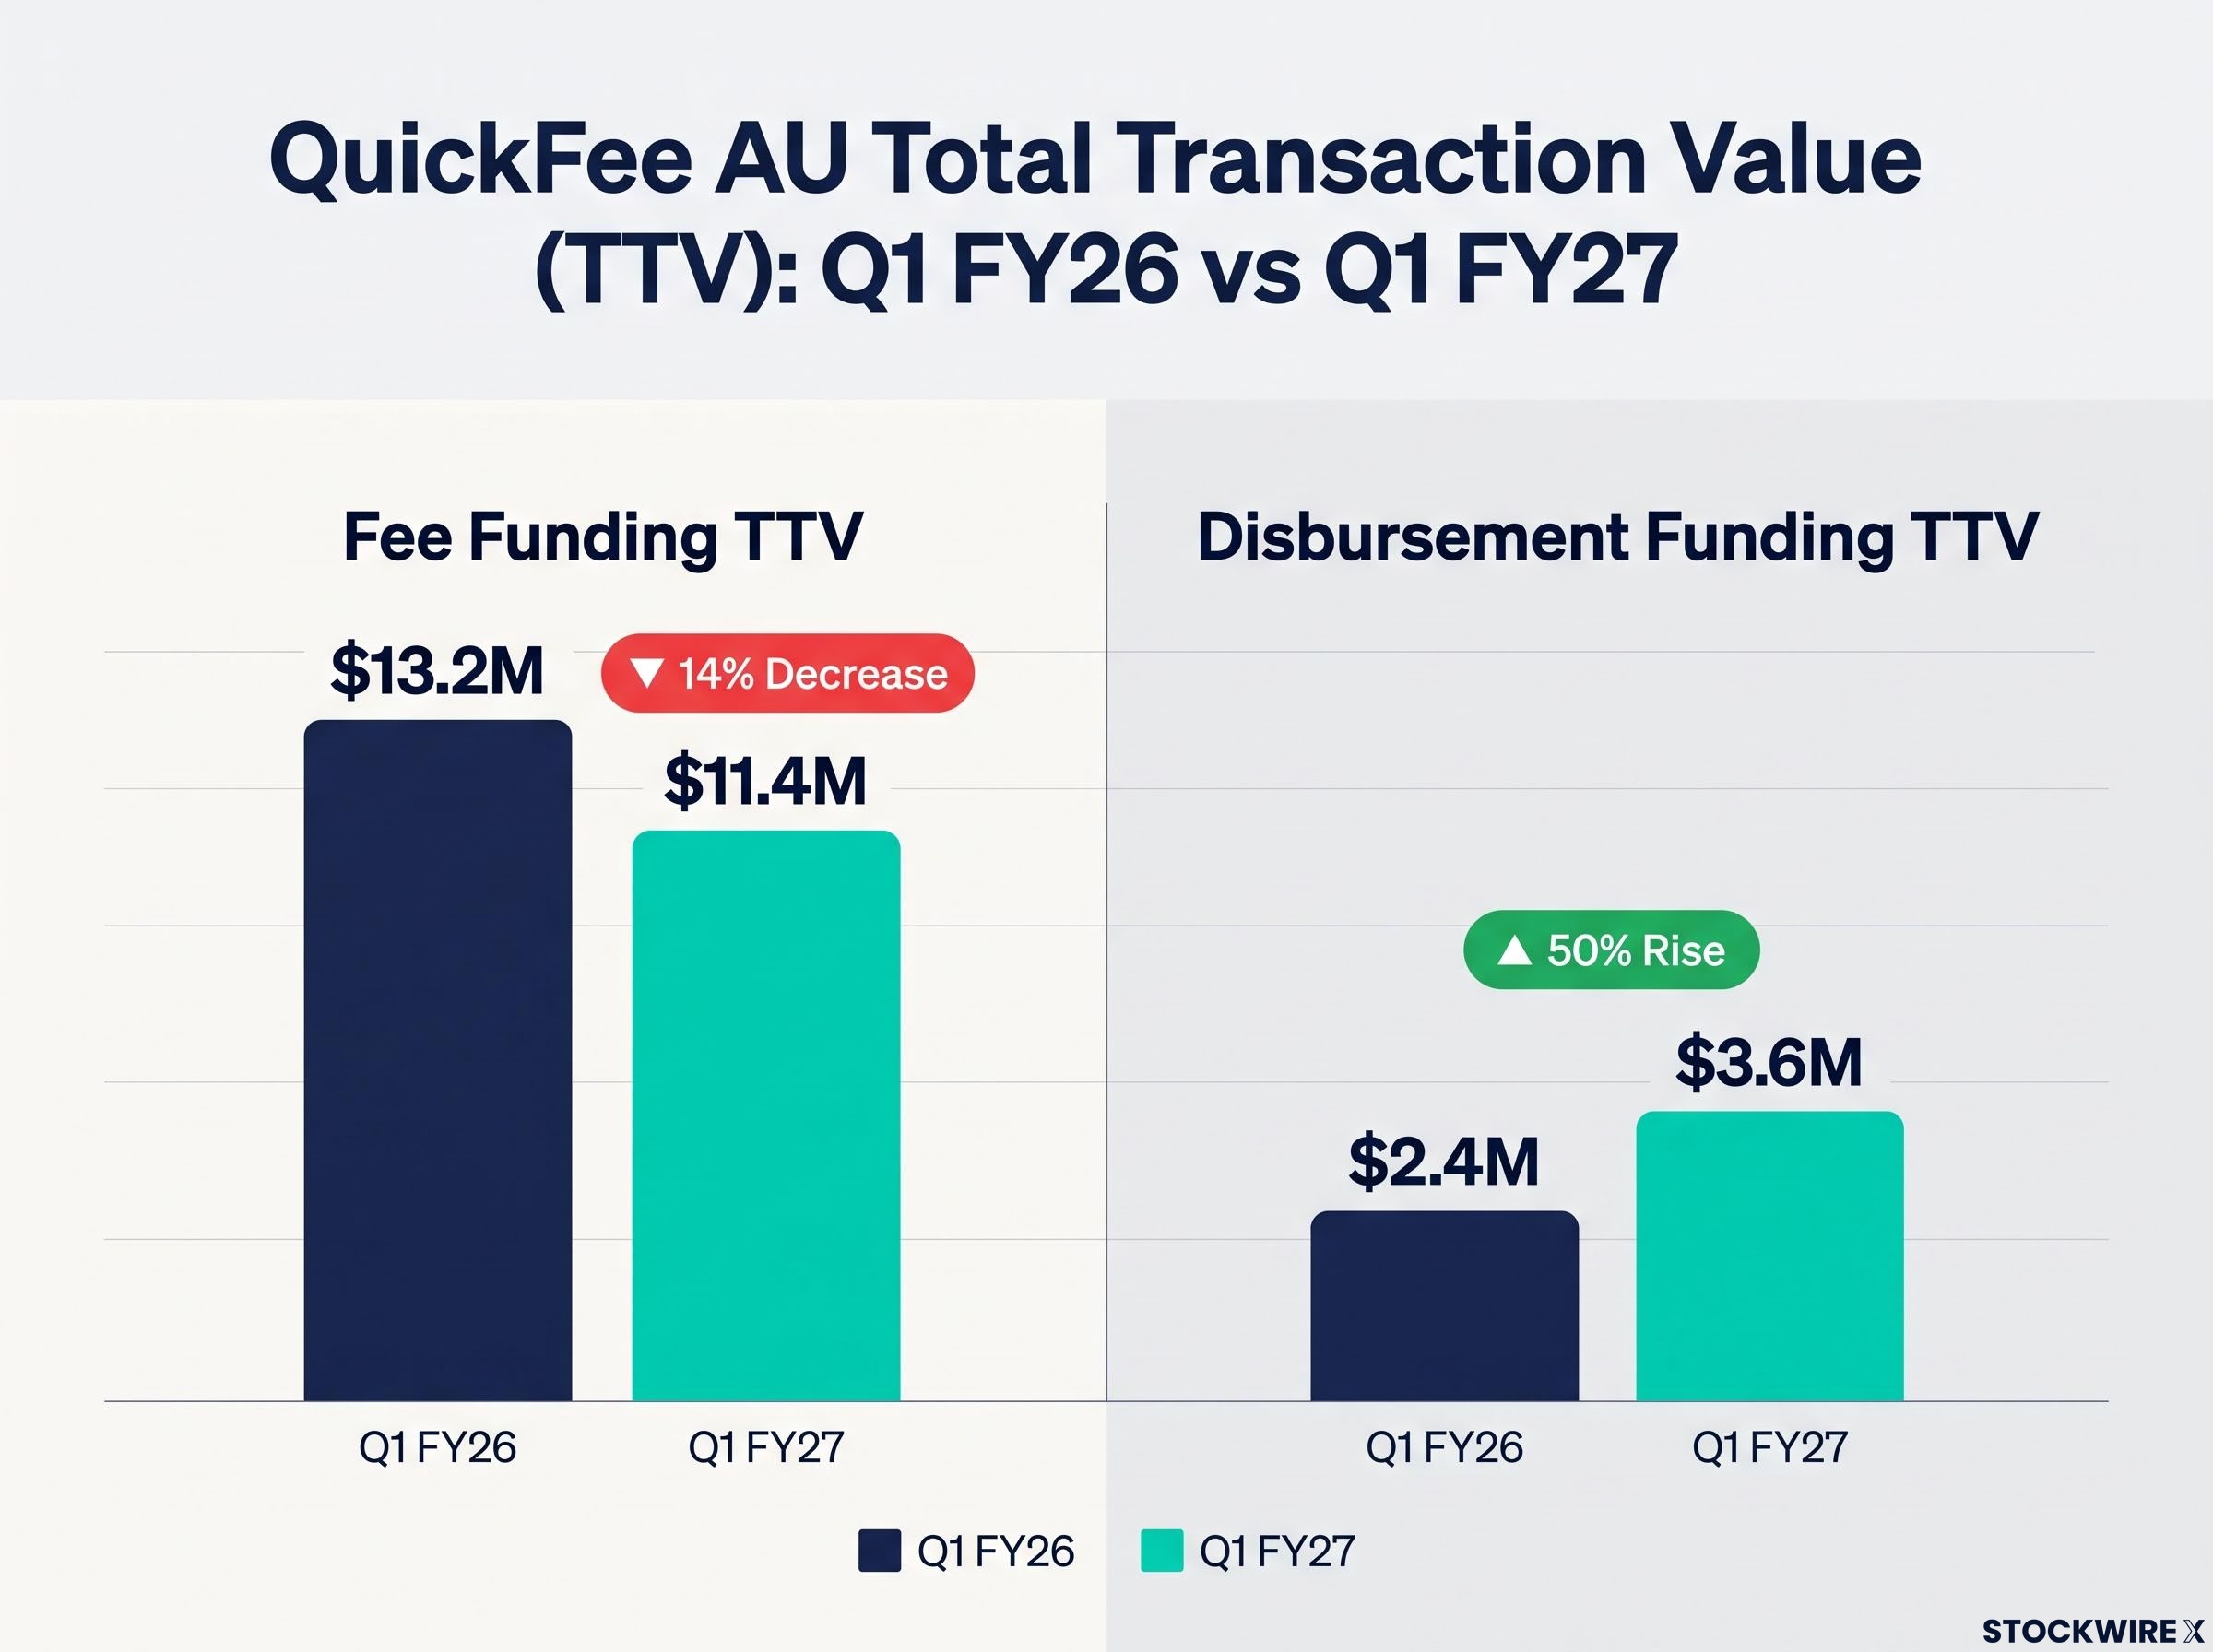
Fee Funding TTV fell 14% to $11.4 million (Q1 FY26: $13.2 million). Disbursement Funding TTV rose 50% to $3.6 million (Q1 FY26: $2.4 million).
AU Finance plans decreased 6% to 1,814, while AU active firms were stable at 437 (Q1 FY26: 440). Total revenue yield was 21.1% versus 19.2%, a rise of 189 bps. Financing revenue was $2,871k and payments and other revenue was $295k.
Low-risk discipline
QuickFee selectively declined higher risk transaction volumes from certain customers, where necessary. Default and arrears rates were stable, although TTV was adversely affected.
New originations of BNPL loans have been discontinued. The existing BNPL loan book is being run off and is expected to be materially cleared by December 2026.
Net interest margin (NIM, rolling last 12 months) declined to 14.4% from 15.3% at FY26, due to multiple interest rate rises in Australia that increased the cost of funds. Pricing will be adjusted and passed onto customers in Q2 FY27.
How fee funding and disbursement funding generate revenue
Fee Funding lets clients pay over 3, 6, 9 or 12 months, while the firm is paid in full within three business days. Revenue is recognised over the life of the loan term, so originations growth in a quarter affects both current and future quarters. Declining originations adversely affect future revenue.
Legal Disbursement Funding (Australia only) provides cashflow for personal injury and estate law firms to pay disbursements on their clients’ matters. The law firm is the borrower, and the loan is repayable on the earlier of when each client matter settles and 36 months.
Revenue on disbursement loans is recognised over the loan term, which results in revenue recognition on existing loans independent of new loan originations. That structure is relevant when fee funding softens, as the growing disbursement funding share sits in a loan book that continues to generate revenue regardless of new originations.
US growth, loan books and liquidity
US Finance TTV rose 15% to US$5.5 million (Q1 FY26: US$4.8 million), primarily driven by new loan originations from existing customers through the direct relationship management team. Plans decreased 7% to 451, and active Finance firms fell 13% to 150. Revenue yield was 9.04% versus 11.5%.
In September 2025, QuickFee established a reseller agreement with Aiwyn, the organisation that purchased its US PayNow business. The exclusive element has ceased due to lower than expected transaction volumes, enabling QuickFee to work with a broader network of resellers.
Loan books at 30 September 2026:
- AU loan book: $55.4 million, with approximately 50% comprising legal disbursement funding loans
- US loan book: US$7.4 million, up 12% in the quarter
Cash on hand and immediately available further funds, based on current loan receivables, totalled $8.3 million. QuickFee also said it remains open to exploring inorganic opportunities should they arise.
What happens next for QuickFee
- AGM: On Tuesday 17 November 2026, QuickFee will provide an update on capital management and a more detailed outlook statement.
- Pricing adjustment: Pricing will be adjusted and passed onto customers in Q2 FY27 to address the higher cost of funds.
- BNPL run-off: The existing BNPL loan book is expected to be materially cleared by December 2026.
- US growth: The company sees solid growth potential in the US in H2 FY27, including integration of its Finance solution into Aiwyn’s payments portal and the addition of new reseller channels.
Don’t Miss the Next Fintech Winner
Join 20,000+ investors getting FREE breaking ASX news delivered to their inbox within minutes of release, complete with in-depth analysis. Click the “Free Alerts” button at Big News Blast to receive fintech and financials alerts the moment market-moving announcements break.