
Q1 FY27 highlights: turnover up 19.1% to $432.3 million
In its Q1 FY27 quarterly results and trading update, betr Entertainment (ASX:BBT) recorded turnover growth of 19.1% to $432.3 million for the three months to 30 September 2026. Net Win rose 14.9% FYTD, and the company reaffirmed its FY27 guidance.
The betr Q1 FY27 result included some customer-friendly results, with margin rebounding in October to date.
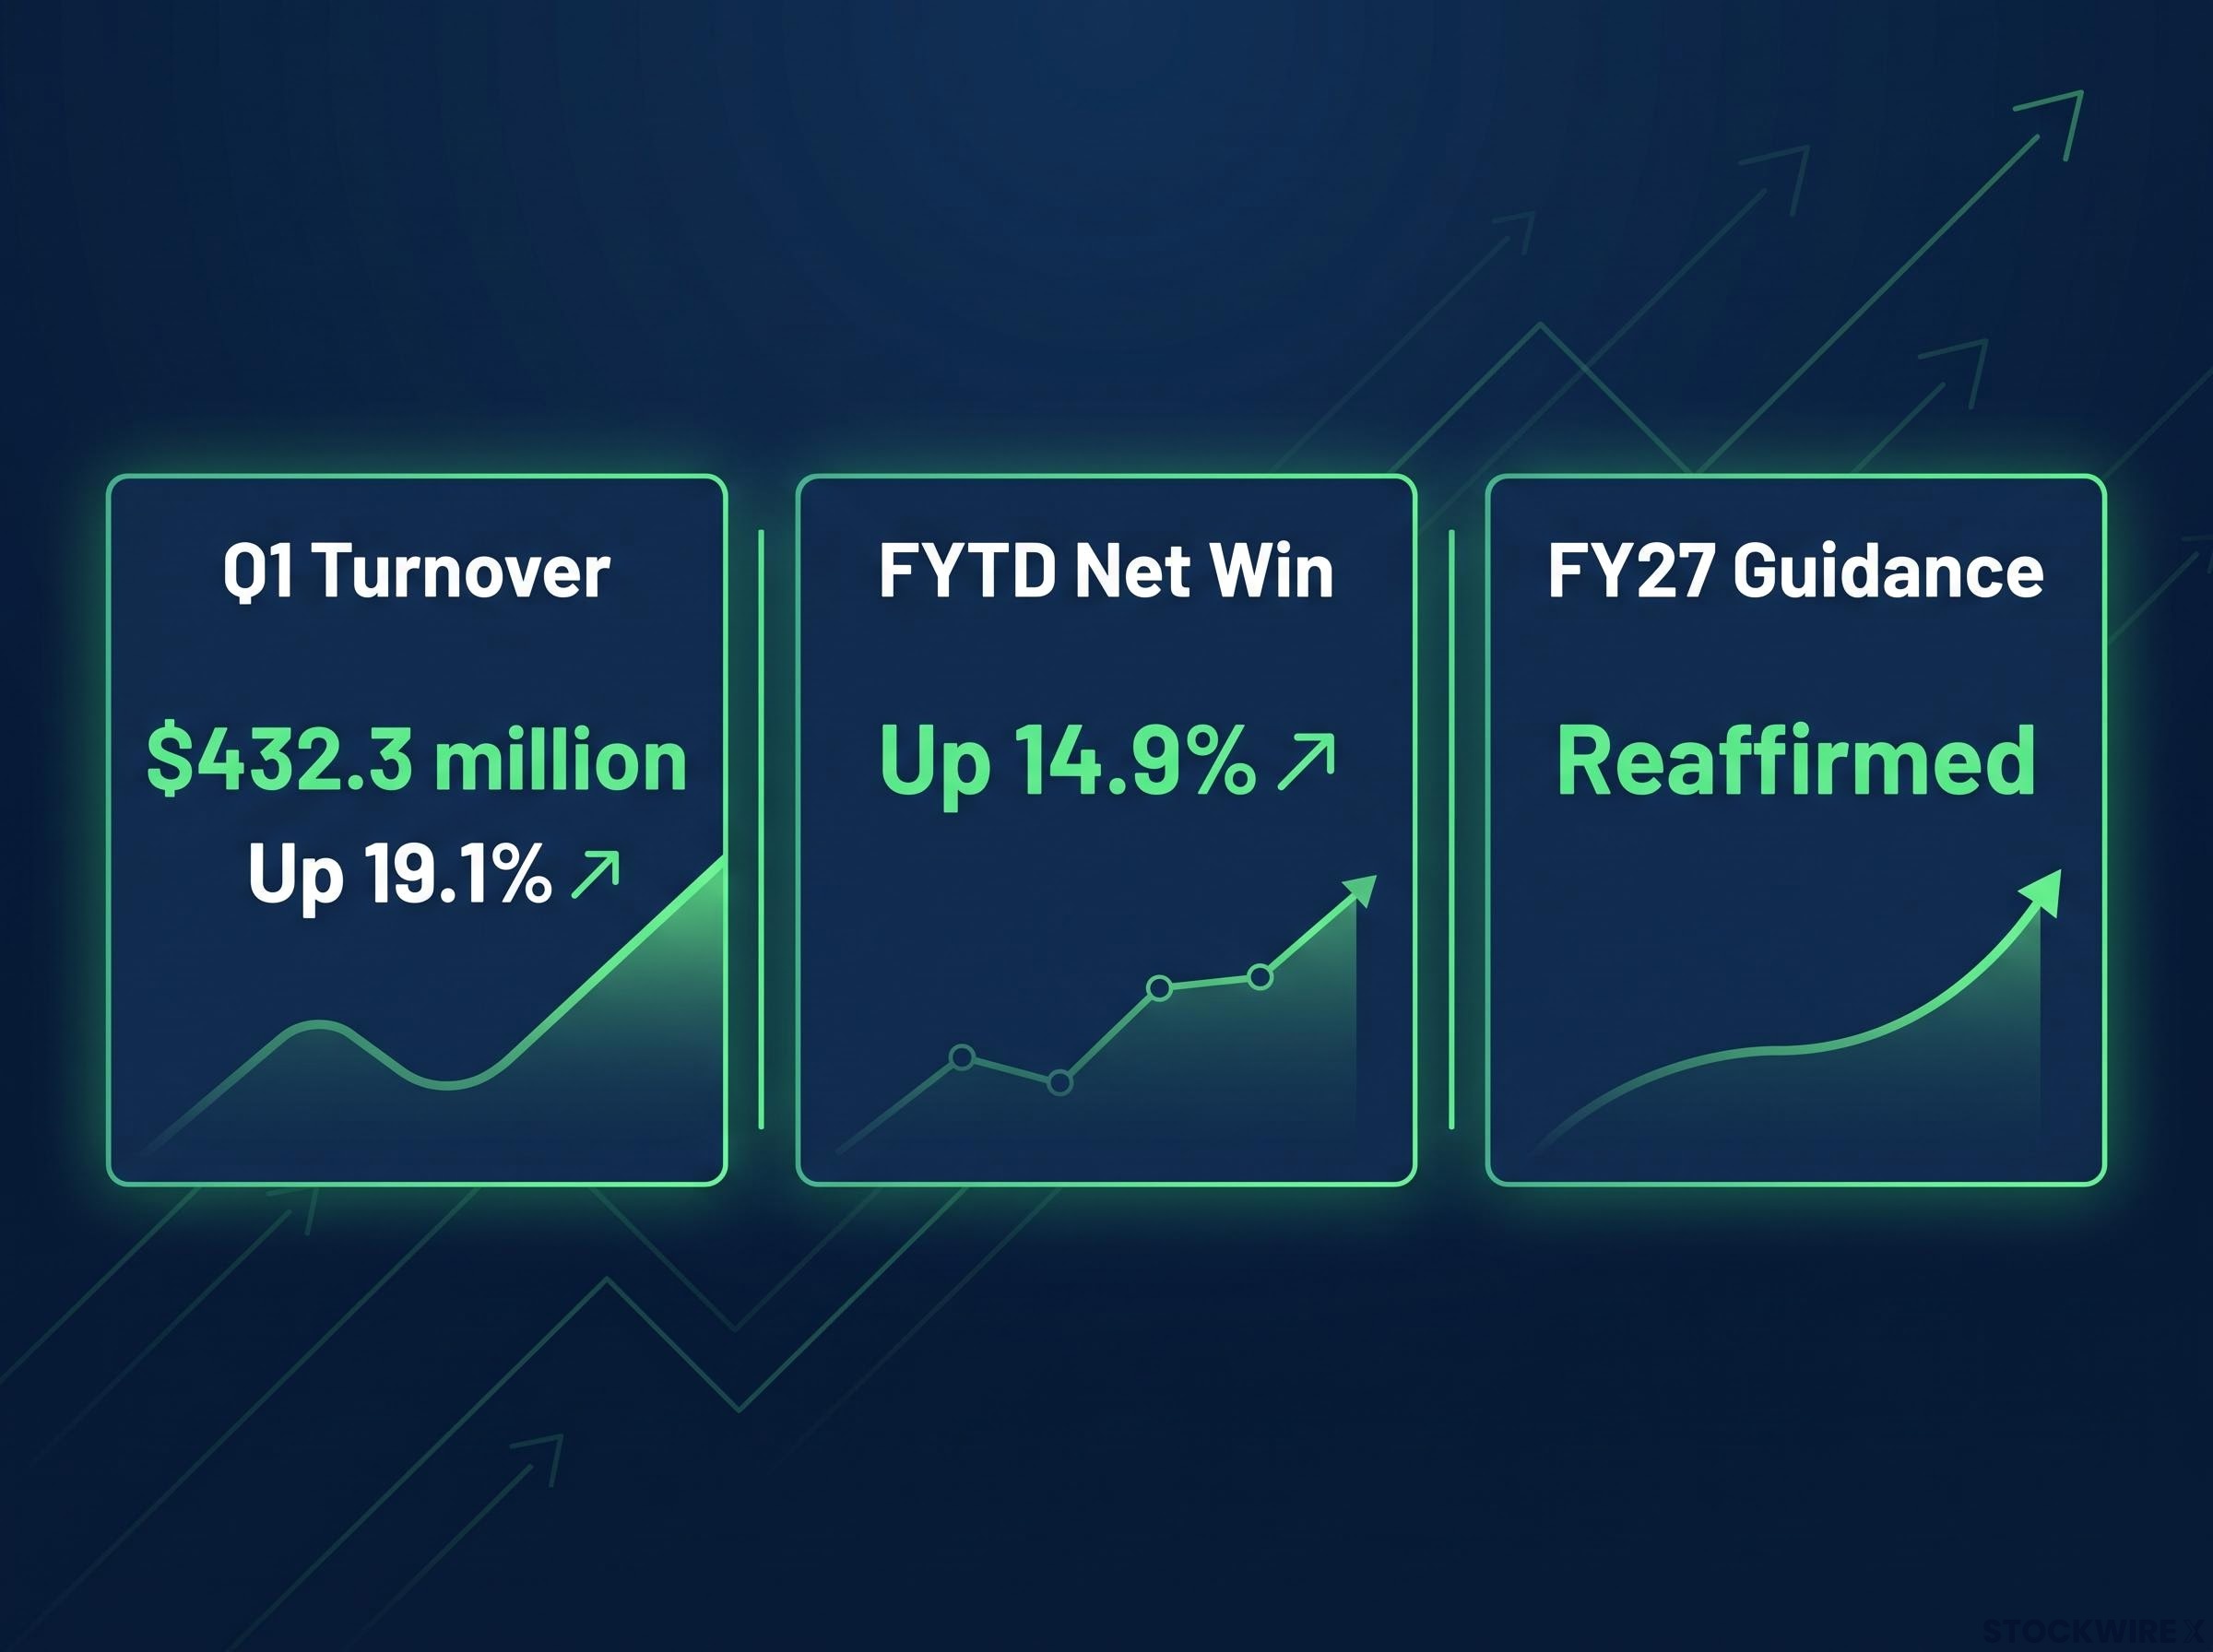
- Turnover: up 19.1% to $432.3 million in Q1
- Net Win: up 14.9% FYTD
- Guidance: FY27 guidance reaffirmed
Andrew Menz, Chief Executive Officer
“We’re very pleased with the growth we experienced in Q1 with our investment in product and brand converting to desirable customer activity heading into spring.”
When big ASX news breaks, our subscribers know first
Product and brand investment drives customer growth
Chief Executive Officer Andrew Menz pointed to investment in product and brand as the driver of customer activity heading into spring. The company’s growth is tied to product and brand levers it controls, rather than results alone.
Menz singled out Wildcards as one of the products bringing in new, high-quality customers. He said it is also winning a larger share of wallet in the company’s most-important season.
What is Net Win margin and why does it matter?
Net Win is the amount a wagering operator keeps after paying out winning bets. Net Win margin is Net Win expressed as a share of turnover.
Margin moves with results. Customer-friendly outcomes lower it, while operator-friendly outcomes lift it. Q1 included customer-friendly results, and margin has rebounded in October to date. The company’s guidance assumes historical Net Win margins (above 10%).
October margin rebound and FY27 guidance reaffirmed
Trading update to 26 October 2026
Management said margin has rebounded strongly in October to date. The trading results are unaudited and cover the period to and including Monday 26 October 2026.
FY27 guidance
betr reaffirmed its FY27 guidance, set out below. Normalised EBITDA excludes one-off costs and share based payments.
| Metric | FY27 guidance | Key assumption |
|---|---|---|
| Normalised EBITDA | $13-19 million | Historical Net Win margins (above 10%) and no material regulatory, taxation or cost of sales changes |
| Operating cash flow | Positive; expected to broadly mirror normalised EBITDA, weighted to H2 | n/a |
Upcoming regulatory reforms are not expected to materially impact betr’s trading. Menz said, “…We are ready for the upcoming regulatory changes and reaffirm our FY27 guidance.”
The move to a Tasmanian Gaming Licence from 7 July 2026, replacing the Northern Territory licence, forms part of the regulatory groundwork behind that readiness.
Reaffirming guidance after a quarter with customer-friendly results points to management confidence in the FY27 outlook.
Company snapshot
betr is a pure-play digital wagering operator listed on the ASX, focusing solely on the Australian wagering market. Its board is led by Matthew Tripp and Michael Sullivan.
For investors, the quarter combined strong turnover growth, an October margin recovery and reaffirmed FY27 guidance.
Get Consumer News Before the Market Moves
Get FREE breaking ASX consumer news delivered to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ investors already ahead of the market. Click the “Free Alerts” button at Big News Blast and see the next big mover the moment news breaks.