

Adrad delivers 10.8% EBITDA lift as data centre and HTS momentum builds in FY26
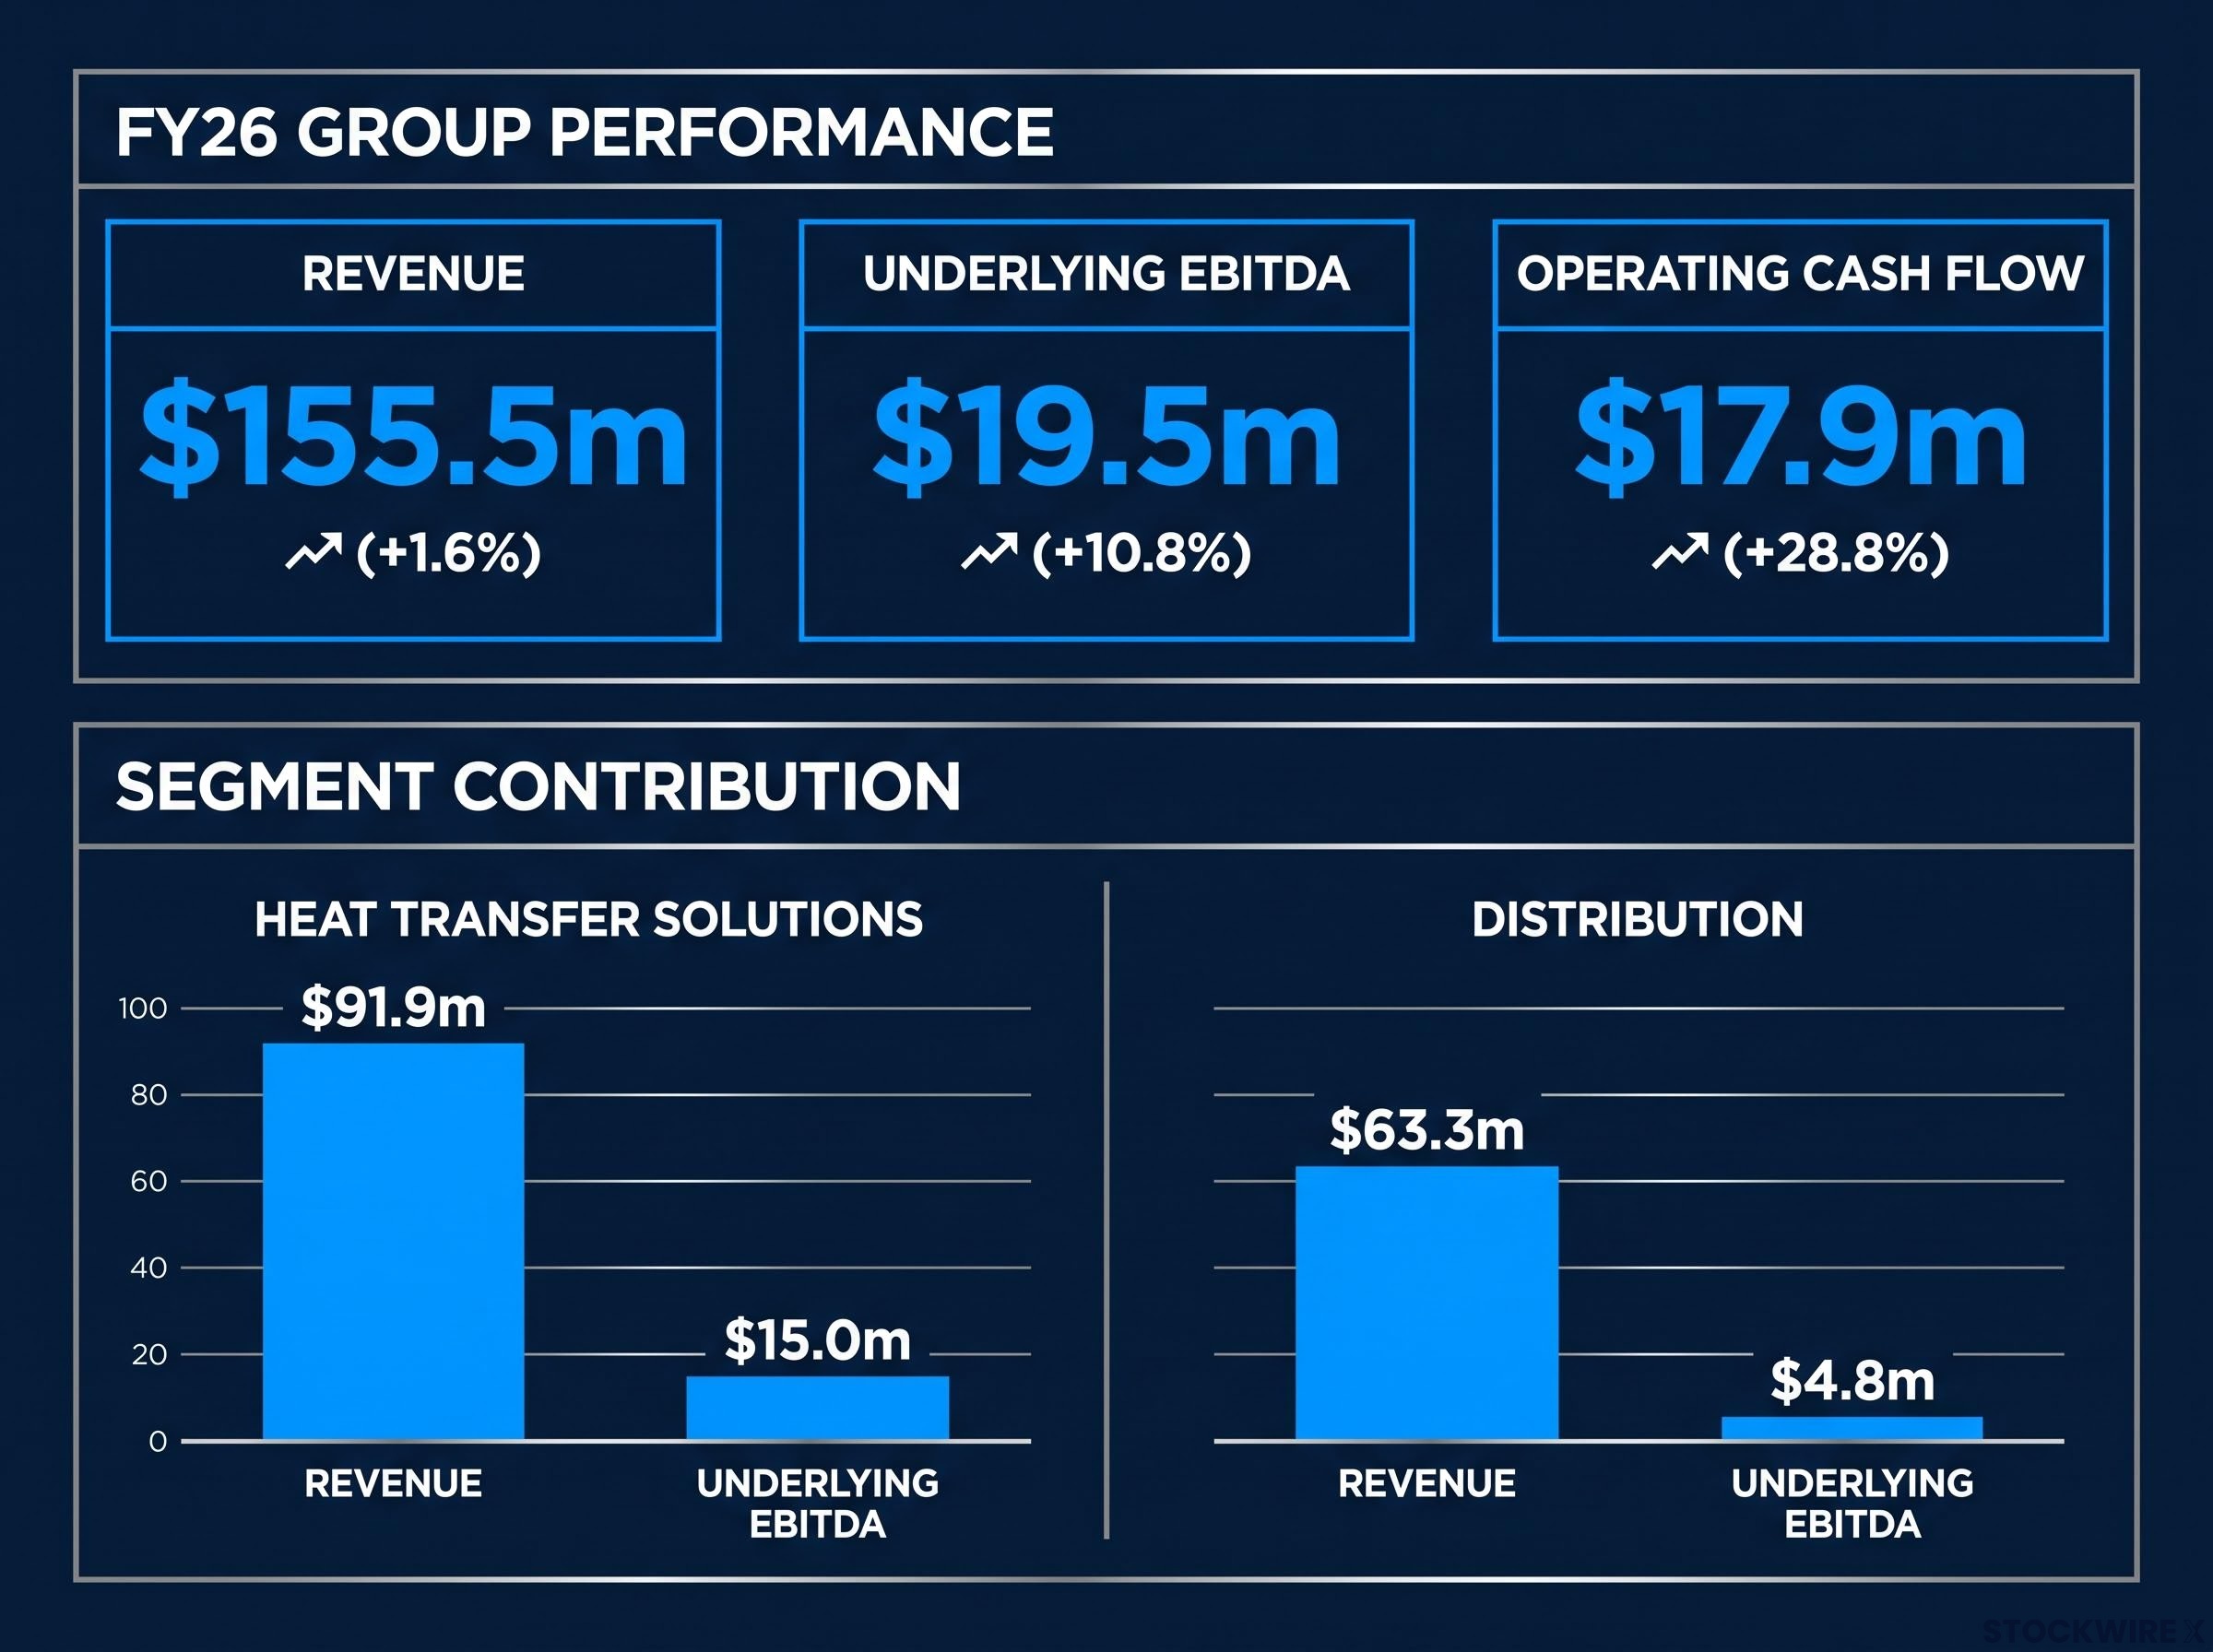
In its FY26 results presentation released August 2026, Adrad Holdings (ASX: AHL) outlined a year of improved earnings quality, with underlying EBITDA up 10.8% to $19.5m on revenue of $155.5m (up 1.6%) for the year ended 30 June 2026.
Operating cash flow rose 28.8% to $17.9m, underscoring stronger earnings conversion. Management highlighted the group’s two-segment structure, with Heat Transfer Solutions (Air Radiators) driving growth and the Distribution (Adrad) business providing resilient cash generation.
The company also lifted FY26 related dividends 15.2% to 4.01 cents per share (cps), fully franked.
When big ASX news breaks, our subscribers know first
FY26 financial results at a glance
The group delivered modest revenue growth alongside a stronger margin and cash conversion profile. Management noted underlying EBITDA margin expanded to 12.5% from 11.4%, reflecting improved operating efficiency and disciplined cost management.
| Metric | FY26 | FY25 | Change |
|---|---|---|---|
| Revenue | $155.5m | $153.1m | +1.6% |
| Underlying EBITDA | $19.5m | $17.6m | +10.8% |
| Underlying NPAT | $7.9m | $7.2m | +9.7% |
| Statutory NPAT | $6.5m | $5.7m | +15.4% |
| Operating cash flow | $17.9m | $13.9m | +28.8% |
| Basic EPS | 8.02cps | — | +15.4% |
Key context management provided included:
-
Revenue increased despite lower volumes from a major OEM customer, supported by growth in data centre activity and new HTS customers.
-
FY26 underlying adjustments of approximately $1.7m relate to non-recurring corporate restructuring costs and the one-off accounting impact associated with the long-term Executive Incentive Arrangement.
-
Underlying figures are non-IFRS financial information and should be considered alongside the statutory results.
Why heat transfer matters: the data centre cooling opportunity
Heat transfer solutions cover the design, manufacture and servicing of radiators and cooling systems that manage the heat generated by industrial equipment. Data centres, which house the servers powering cloud computing and artificial intelligence, require constant, reliable cooling to keep equipment running safely.
Management highlighted several structural drivers behind this demand: the growth of AI and cloud computing, increasing power density, the need for critical cooling infrastructure and rapid global data centre investment. The presentation noted that identified market opportunities continue to expand rapidly at around 100% growth per annum.
Adrad has invested to capture this market. The company reported that Australian data centre capacity was doubled, while data centre orders exceeded 400 units across its Lara (Victoria) and Gillman (South Australia) sites.
These higher-value engineered cooling applications typically carry stronger margins than traditional radiator repair work, which ties directly into the segment margin story below.
HTS drives the result with 40.2% underlying EBITDA growth
Heat Transfer Solutions acted as the growth engine in FY26, delivering a 40.2% increase in underlying EBITDA and expanding its underlying EBITDA margin to 16.3% from 11.9%.
The 40.2% EBITDA lift in HTS builds directly on the trajectory established in the first-half FY26 results, when the segment posted a 36.7% EBITDA gain supported by a $17 million data centre order win that prompted management to accelerate capacity investment.
| Segment | FY26 Revenue | FY26 Underlying EBITDA | Underlying EBITDA Margin |
|---|---|---|---|
| Heat Transfer Solutions | $91.9m | $15.0m | 16.3% |
| Distribution | $63.3m | $4.8m | 7.6% |
Management attributed the margin expansion to organisational restructuring, a higher-value sales mix and improved manufacturing efficiency. FY26 operational highlights included:
-
Doubled Australian data centre capacity, with 400+ units ordered across Lara and Gillman.
-
Manufactured and delivered 20 large radiator systems for an 85MW power station in Western Australia.
-
Secured additional mining and power generation contracts for FY27.
-
Thailand secured three new Japanese heavy industries OEMs for Southeast Asian power generation after exceeding stringent qualification criteria.
-
Launched a new low-cost coil product range in Thailand.
-
Progressed Alu Fin products through customer field trials and OEM approval processes.
Distribution holds firm as channels diversify
The Distribution business remained a resilient, cash-generative platform, though earnings softened. Revenue held broadly flat at $63.3m, while underlying EBITDA eased to $4.8m and the margin declined to 7.6% from 9.5%.
Management noted traditional radiator repair revenue declined around 10% following softer transport and mining activity, with trading conditions weakening in the fourth quarter on higher fuel prices and softer aftermarket demand. Channel diversification partially offset this pressure:
-
Automotive Trade: customer base up 5.4%, revenue up 7.8%.
-
Reseller: customer base up 6.9%, revenue up 21.0%.
-
Natrad Autocare: workshops increased to 25 at 30 June 2026, with program revenue up 16.0%.
Management indicated margins improved towards the end of FY26 following operational initiatives, restructuring and pricing discipline.
A stronger balance sheet funding the growth agenda
The company reported a strengthened balance sheet supporting its expansion strategy, with minimal borrowings of just $0.4m.
-
Cash rose 34.6% to $24.5m.
-
Net assets increased to $128.7m.
-
Franking account balance of $40.3m.
-
Net tangible assets per share of 106.9cps, up 2.1%.
-
Contract assets reduced from $4.7m to $0.7m, aiding cash conversion.
-
Capital investment of $5.2m directed into manufacturing capability.
Management stated the balance sheet supports continued investment in manufacturing capacity, dividends and growth opportunities, with capital allocation focused on operational investment.
Investment thesis and FY27 outlook
Management framed FY26 as another step in the group’s transition towards a higher-quality industrial business, supported by growing exposure to structurally expanding end markets.
Adrad Holdings — FY26 Presentation Conclusion
“FY26 marked another step in Adrad’s transition towards a higher-quality industrial business… while the Distribution business continues to generate resilient cash flow to support ongoing investment in growth.”
On outlook, management noted the business is “positioned to deliver a stronger half year result than the previous corresponding period,” supported by a substantial HTS order book. The company cautioned that the outlook remains subject to customer demand, project timing and broader economic conditions.
The five FY27 priorities management outlined were:
-
Convert customer demand into revenue across data centre, power generation and mining opportunities.
-
Expand manufacturing capacity, including completing the Thailand expansion of over 4,000sqm and lifting utilisation across Lara and Gillman.
The Thailand manufacturing expansion approved in July 2026 adds over 4,000 sqm of owned floor space to be funded entirely from existing cash, consolidating previously rented facilities and targeting data centre coil products, aluminium manufacturing and mining cooling as primary revenue streams for the new capacity.
-
Progress Alu Fin approvals and deepen OEM relationships.
-
Grow Distribution channels and continue the Natrad Autocare rollout.
-
Maintain disciplined capital allocation, including assessing acquisitions that strengthen capability and market position.
The presentation closed on the group’s structural growth positioning across data centres, power generation, mining, defence and its OEM pipeline, supported by a diversified Australian and Thailand manufacturing footprint. A fully franked final dividend of 2.56cps carries a record date of 21 September 2026 and a payment date of 21 October 2026.
Don’t Miss the Next ASX Manufacturing Breakout
Big News Blast delivers FREE breaking ASX news directly to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ investors already staying ahead of the market on manufacturing, industrials and beyond. Click the “Free Alerts” button at Big News Blast to start receiving alerts the moment market-moving news breaks.