

1H FY2026 highlights: FDV’s margin expansion story takes shape
In its 1H FY2026 results presentation, Frontier Digital Ventures (ASX: FDV) outlined a deliberate strategic trade-off: accept lower statutory revenue by exiting non-core, loss-making lines in exchange for meaningfully higher EBITDA margins and free cash flow generation. The period covered January to June 2026, with results presented to the market on 23 September 2026.
FDV’s FY2025 full-year results, released in April 2026, established the baseline for this trajectory: statutory EBITDA of A$5.5 million represented a 205% year-on-year increase, with the EBITDA margin expanding from 3% to 10% as management began exiting non-core revenue lines and reducing operating expenses across LATAM.
The headline metrics from the presentation reflect this quality-over-quantity shift:
- Statutory revenue of US$14.4m, down 27% on the prior corresponding period (pcp) — attributed entirely to the termination of non-core revenue lines, not weakening demand
- Statutory EBITDA of US$2.4m, up 18% on pcp
- EBITDA margin of 17%, expanding from 10% in 1H 2025
- Free cash flow of US$2.3m, with a 98% free cash flow conversion rate
- Cash balance of US$8.1m at 30 June 2026, up 33%
- EBITDA including Associates of US$3.6m, up 13% on pcp
The 98% free cash flow conversion figure stands out as a particularly material improvement, comparing favourably against 28% conversion in 1H 2025.
When big ASX news breaks, our subscribers know first
Understanding FDV’s classifieds model — and why take rate matters
FDV operates online classifieds marketplaces that connect buyers and sellers of high-value consumer goods, principally property and automotive assets. These platforms earn revenue through listing fees, advertising, and transaction facilitation. The core monetisation metric for these businesses is “take rate,” defined as the classifieds platform’s revenue as a percentage of the total commission pool available to sellers, agents, and dealers.
FDV’s current average take rate sits at below 1%. The presentation highlighted where leading global peers currently operate: Baltic Classifieds Group at approximately 6%, Rightmove at approximately 7%, REA Group at approximately 12%, Scout24 at approximately 9%, Autotrader at approximately 6%, and Car Group at approximately 7%.
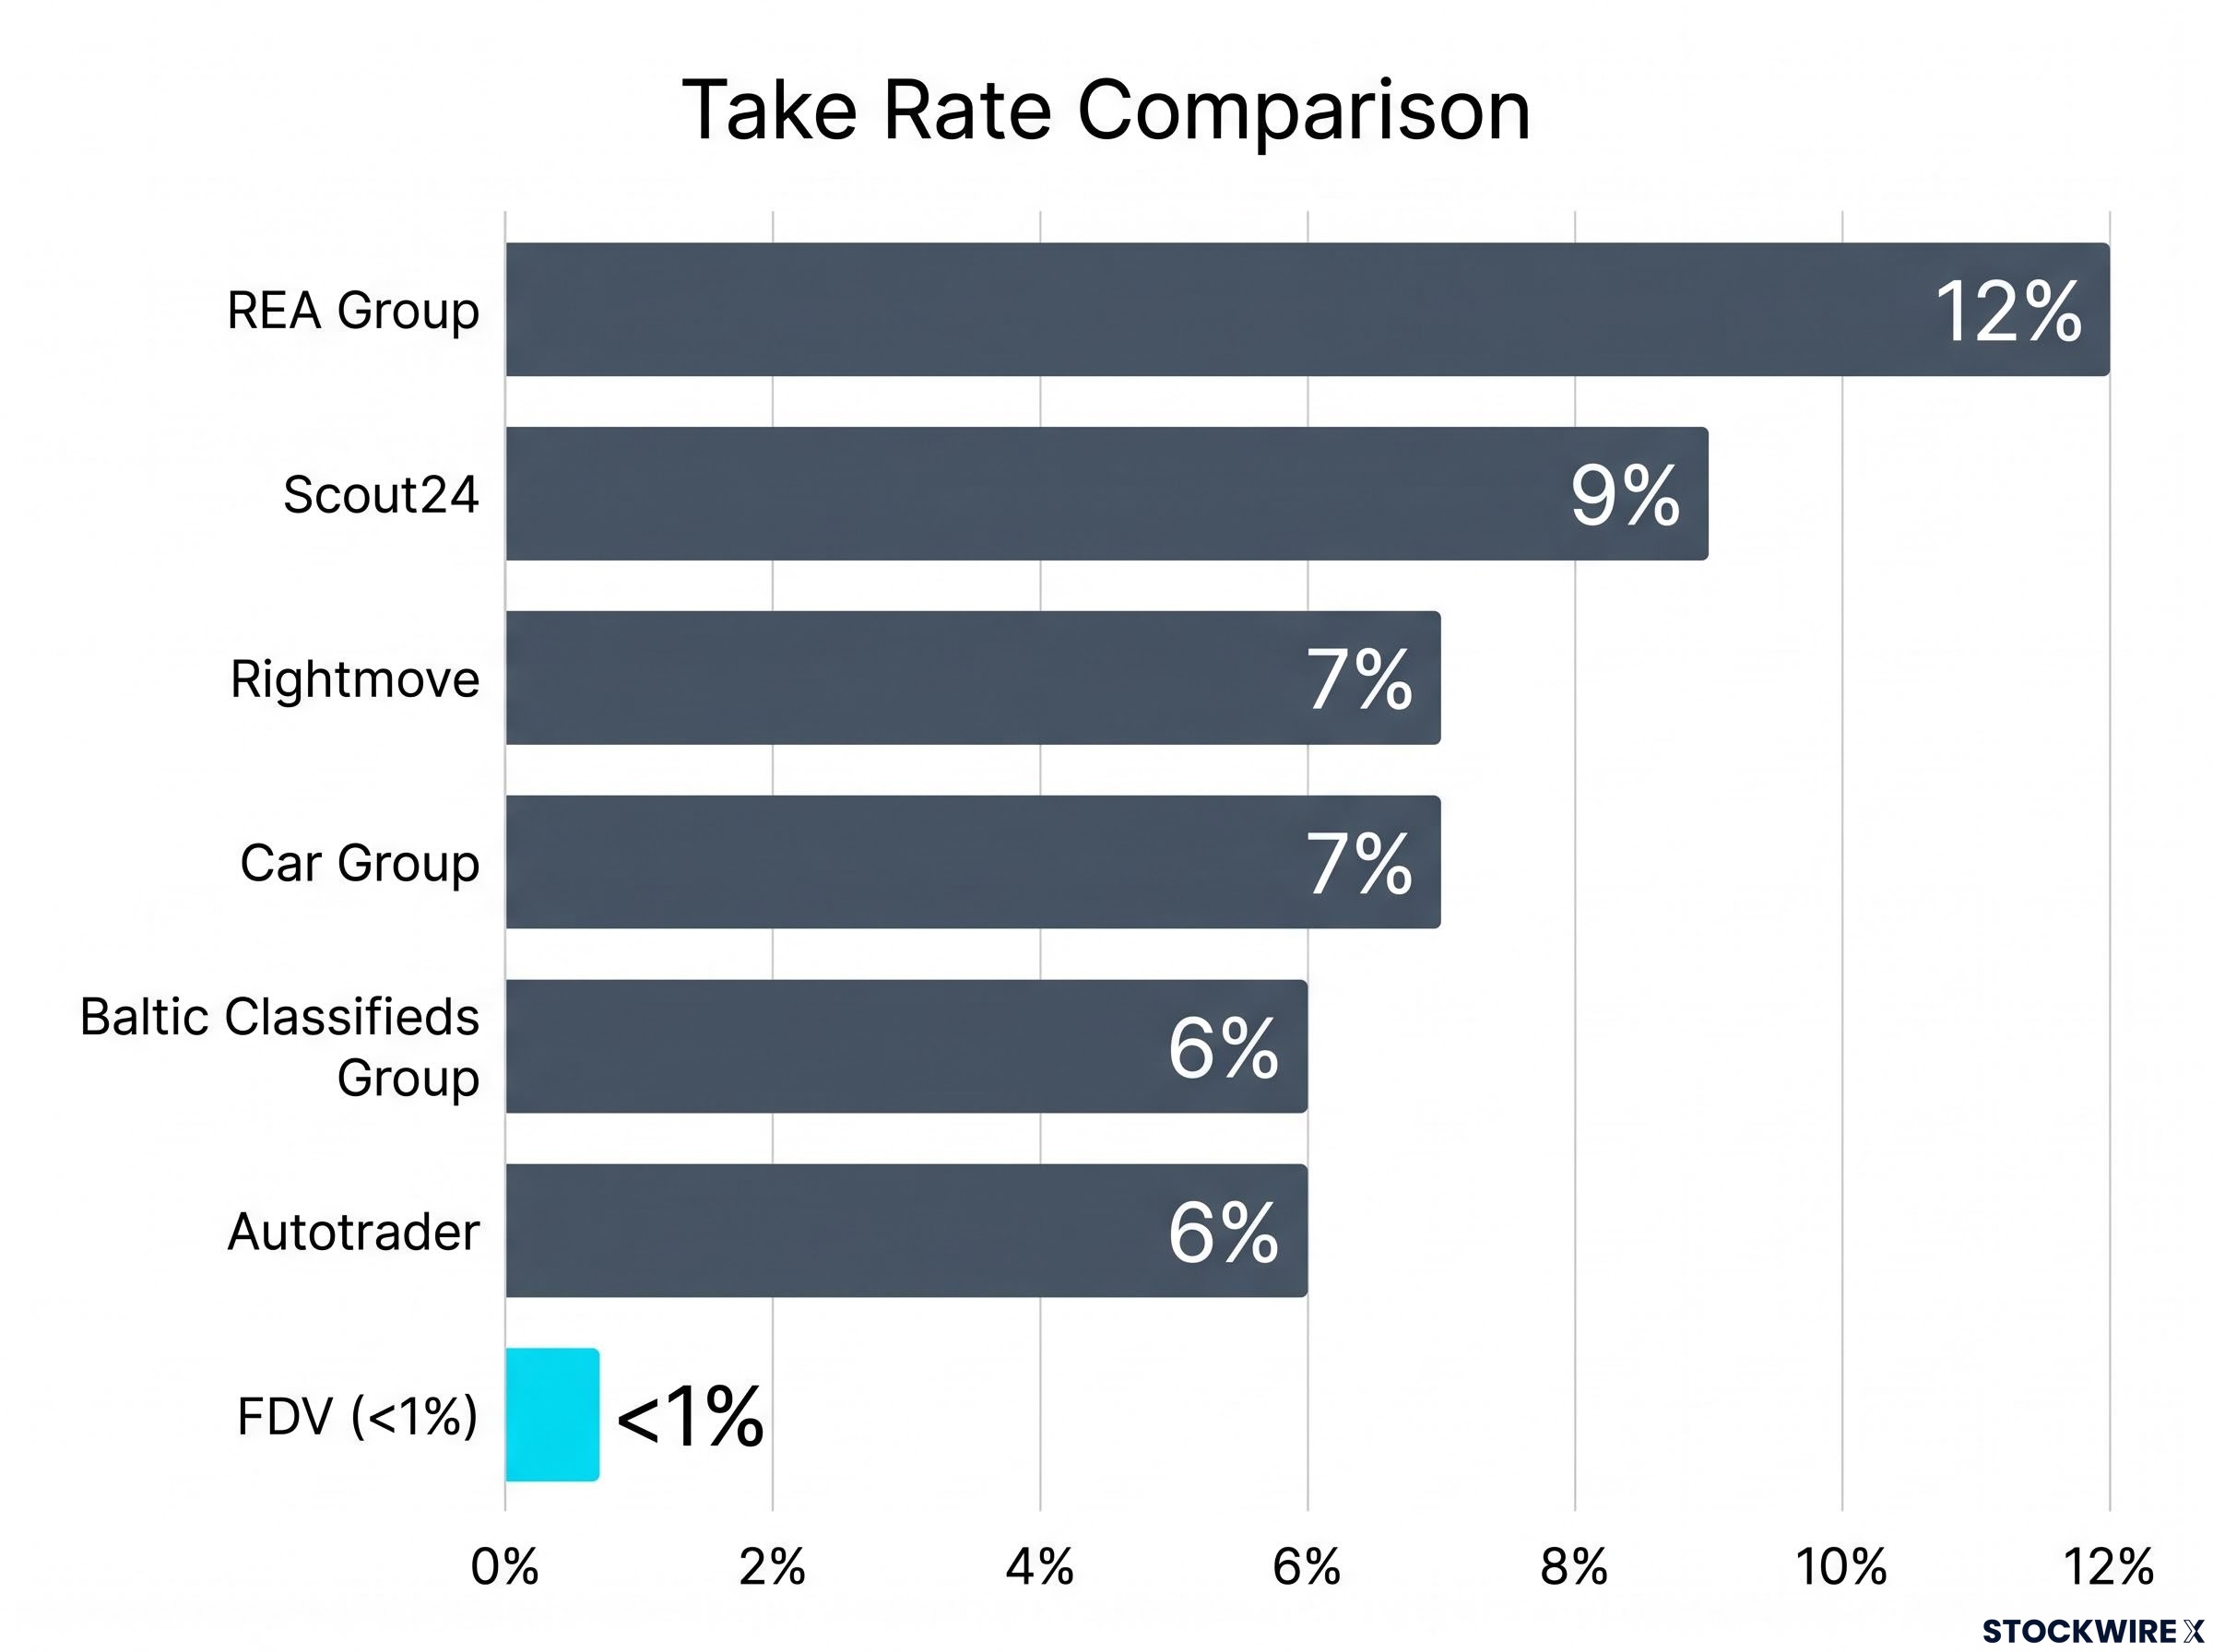
That gap represents the central investment thesis management presented. FDV’s platforms hold market-leading positions in their respective regions, yet monetisation remains at an early stage. ARPU (average revenue per user) growth already being achieved across LATAM and Morocco offers early evidence that pricing optimisation is beginning to work.
The operating leverage in classifieds businesses is a structural feature of the model: once fixed platform and technology costs are covered, incremental revenue from ARPU growth or take rate expansion flows through to earnings at high incremental margins, which is precisely the dynamic FDV’s North Star targets are designed to capture.
Regional performance — where the gains are coming from
LATAM — EBITDA up 37% as classifieds mix improves
LATAM delivered revenue of US$9.6m, down 35% on pcp, consistent with the group-level explanation: the result reflects the proactive termination of non-core, low-margin revenue lines rather than underlying demand deterioration. EBITDA, however, rose 37% on pcp to US$3.1m, with the EBITDA margin expanding from 15% to 32%. Classifieds revenue now represents 91% of total LATAM revenue, up from 63% in 1H 2025.
At the brand level, Fincaraiz was the standout performer. EBITDA margin expanded from 16% to 37%, free cash flow grew 678% to US$1.1m, and ARPU increased across all customer segments — agents up 10%, developers up 17%, and private sellers up 40%. InfoCasas also delivered a significant turnaround, with its EBITDA margin expanding from 4% to 32% and free cash flow turning positive from -US$0.6m to +US$0.4m.
For Encuentra24, the presentation clarified that the headline -30% revenue decline requires context. Approximately 20% of that decline is attributable to the absence of event-bundled revenue that benefited the prior period. When adjusted for this, the true decline in ongoing classifieds revenue is approximated at 7% on pcp. Management flagged a freemium pricing review for private sellers in 2H 2026.
Morocco — flat revenue, EBITDA up 63%
Morocco recorded revenue of US$3.2m, flat on pcp. Within that, Avito (Morocco) grew 2% while Tayara (Tunisia) declined 46%, the latter offsetting the former at the segment level. Morocco EBITDA rose 63% on pcp to US$0.6m. Avito’s own EBITDA margin expanded from 7% to 15% (reported at the Avito Group level as 11% to 22%). Classifieds revenue increased 7% on pcp, driven by growth in new development projects and higher ARPU through higher-tier package adoption in auto.
Tayara remained loss-making, recording EBITDA of -US$73.9k. Management acknowledged this and stated that cost restructuring is planned in 2H 2026 to bring the business unit to EBITDA breakeven.
Pakistan Associates — growing quietly
Zameen and PakWheels are equity-accounted associates and therefore excluded from FDV’s statutory revenue. Combined, their revenue grew 8% to US$5.1m in 1H 2026. PakWheels was the standout, with revenue up 36% to US$1.3m and EBITDA up 26%. Together, the two associates contributed US$1.2m to FDV’s EBITDA including Associates figure.
Asia (consolidated entities) recorded revenue of US$1.6m, down 5% on pcp, with currency headwinds in the Philippines and Sri Lanka cited as a contributing factor. Asia EBITDA came in at US$96k.
| Region | 1H 2025 Revenue (US$m) | 1H 2026 Revenue (US$m) | 1H 2026 EBITDA (US$m) | EBITDA Margin |
|---|---|---|---|---|
| LATAM | $14.8m | $9.6m | $3.1m | 32% |
| Morocco | $3.2m | $3.2m | $0.6m | 18% |
| Asia | $1.7m | $1.6m | $0.1m | 6% |
| Associates (Pakistan) | $4.7m | $5.1m | $1.2m | 25% |
| Statutory Total | $19.8m | $14.4m | $2.4m | 17% |
Note: Associates (Pakistan) figures reflect FDV’s proportionate equity-accounted share and are excluded from the statutory totals. LATAM 1H 2025 revenue and EBITDA margin sourced from the Statutory Revenue and EBITDA by Brand tables.
Strategic priorities and what the second half holds
Management outlined three strategic pillars in the presentation: maintaining focus on the core, high-margin classifieds business; expanding margins through ARPU growth and take rate optimisation; and pursuing accretive M&A in existing markets where clear synergy and return thresholds can be met.
These pillars connect directly to what the presentation described as FDV’s “North Star” targets: expanding EBITDA margin to above 40%, increasing take rate toward peer levels, and achieving 75% free cash flow conversion. The 1H FY2026 results showed progress against two of these three targets, with the EBITDA margin reaching 17% and free cash flow conversion at 98%. Take rate remained below 1% with little change from year-end 2025, indicating that the most material monetisation lever is still largely untapped.
One area requiring transparency is the rise in group corporate costs. These increased 88% to US$1.4m in 1H 2026. The presentation attributed this to three factors: AUD strengthening 24% and MYR strengthening 10% against the USD on average during the period, with the proportion of AUD-settled expenses rising to 76% from 61% in the prior period; a pro-rata accrual of US$0.2m for Executive Directors’ year-end 2026 short-term incentive cash award; and share-based payment expense of US$0.3m for performance rights granted to Executive Directors.
For 2H 2026, management identified two specific operational actions: cost restructuring at Tayara to reach EBITDA breakeven, and a review of freemium pricing for private seller listings at Encuentra24.
Don’t Miss the Next Tech and Media Breakout on ASX
Big News Blast delivers FREE breaking ASX news straight to your inbox within minutes of release, complete with in-depth analysis already done for you. Over 20,000 active subscribers rely on it to stay ahead of the market. Click the “Free Alerts” button at Big News Blast to make sure the next major announcement lands in your inbox before the market moves.