

ASIC registers Ramsay Santé Demerger Booklet ahead of 24 November vote
The Australian Securities and Investments Commission has registered the Demerger Booklet for the proposed distribution by Ramsay Group of its 52.79% shareholding in Ramsay Générale de Santé SA to shareholders of Ramsay Health Care (ASX: RHC). The announcement is dated 19 October 2026, and the booklet is dated 16 October 2026.
The Ramsay Santé demerger now moves into its formal decision window. Shareholder meetings will be held consecutively on 24 November 2026, immediately after the 10.00am Annual General Meeting, at The Fullerton Hotel Grand Ballroom, Sydney, with a live webcast available.
Each Ramsay Director recommends that shareholders vote in favour of the resolutions. Deloitte Corporate Finance Pty Limited, the Independent Expert, concluded that the Demerger is in the best interests of shareholders “in the absence of a superior proposal”.
The booklet adds a caveat to the unanimous recommendation. Shareholders should have regard to the interests of Group CEO & Managing Director Natalie Davis, who holds 131,547 unvested performance rights and would be entitled to certain Supplementary Awards, subject to the Scheme becoming effective and shareholders approving the Supplementary Award Resolution.
The vote is not a done deal. Shareholder approval, Court approval and ASX quotation are all still required.
When big ASX news breaks, our subscribers know first
What Ramsay shareholders receive
Eligible shareholders would receive 0.25 of a Ramsay Santé Security for every Ramsay Share held at the Record Date, rounded down to the nearest whole security. Existing Ramsay Shares are unaffected. The booklet states that it is not possible to predict the market value of Ramsay Santé Securities after the Demerger.
The securities are anticipated to be Ramsay Santé CDIs, tradeable on the ASX in AUD. This assumes Ramsay Santé obtains its Foreign Exempt Listing, for which it has received in-principle approval from ASX. Otherwise, Ramsay Santé Shares would trade on Euronext Paris in EUR.
Small Shareholders, who hold 500 Ramsay Shares or less at the Record Date, receive cash by default. They must submit an Opt-Out Form by 5.00pm on 30 November 2026 to receive Ramsay Santé Securities instead. Ineligible Overseas Shareholders also receive sale proceeds rather than securities.
David Thodey, Chair
“Your Board unanimously recommends that you vote in favour of the demerger, which is intended to provide the best opportunity to maximise value for Ramsay shareholders over time.”
Two companies, two profiles
After the Demerger, Ramsay would be Australia’s largest private hospital operator, with 71 hospitals, alongside Ramsay UK and Elysium Healthcare. Ramsay Santé operates 491 healthcare facilities across five countries: France, Sweden, Norway, Denmark and Italy.
| Metric | Ramsay (post Demerger) pro forma | Ramsay Santé historical |
|---|---|---|
| FY2026 revenue | A$9,414.8m | A$9,275.5m |
| FY2026 EBIT | A$806.8m | A$298.6m |
| FY2026 NPAT | A$386.6m | Net loss of A$65.2m |
These are the booklet’s pro forma and historical figures, not forecasts. The Demerger would deconsolidate Ramsay Santé, which reported lower EBIT and a net loss against the pro forma Ramsay result, and the booklet states it is intended to sharpen management focus on the Australian and UK businesses.
Demerger explained for investors
A demerger separates one business from a listed parent and distributes it to shareholders. Here, shareholders keep their Ramsay Shares and gain a separate holding in Ramsay Santé.
The original in-specie distribution proposal, first outlined in February 2026, framed the structure as a way for shareholders to receive Ramsay Santé exposure in proportion to their holdings without needing a cash sale.
A CDI (CHESS Depositary Interest) gives an indirect, beneficial interest in an underlying Ramsay Santé Share. It allows trading on the ASX in AUD, but CDI holders cannot vote directly at Ramsay Santé meetings and remain exposed to AUD/EUR currency movements.
The in-specie distribution (a distribution of assets rather than cash) would work through a scheme of arrangement:
- Shareholders vote on the Capital Reduction Resolution and the Scheme Resolution.
- The Court is asked to approve the Scheme.
- The Scheme becomes effective once the Court order is lodged with ASIC.
- Ramsay Santé Securities are transferred or issued on the Implementation Date.
For investors, the booklet points to choice over exposure to each business. It also notes that Ramsay’s holding is excluded from the Ramsay Santé free float, which is currently about 7.39%, and that distribution may increase free float and liquidity. Ramsay’s reported financial profile would also be simplified.
Advantages and risks the booklet outlines
The advantages set out in the booklet include:
- Greater flexibility and liquidity to choose investment levels in each company.
- A simplified Ramsay financial profile through full deconsolidation of Ramsay Santé.
- An improved ability for each company to pursue independent growth strategies.
- Enhanced management focus on Ramsay’s Australian and UK operations.
- The greatest certainty of execution within the considered timeline compared with alternatives.
The disadvantages and risks include:
- About $59m in pre-tax transaction costs, of which about $27m will be incurred whether or not the Demerger proceeds.
- A smaller and less diversified Ramsay.
- A move from an indirect controlling interest to a direct non-controlling minority interest.
- CDI currency risk and no assurance of an active, liquid ASX market.
- Uncertainty about the combined market value of Ramsay Shares and Ramsay Santé Securities.
- Direct exposure to the French regulatory regime for those receiving Ramsay Santé Securities.
The Ramsay Santé refinancing completed in July 2026 extended debt maturities to 2033 and included a change of control provision built to accommodate the in-specie distribution, which removed a key financing hurdle ahead of the vote.
The booklet states it is likely that Ramsay will remain in the S&P/ASX 100, but no assurances can be made.
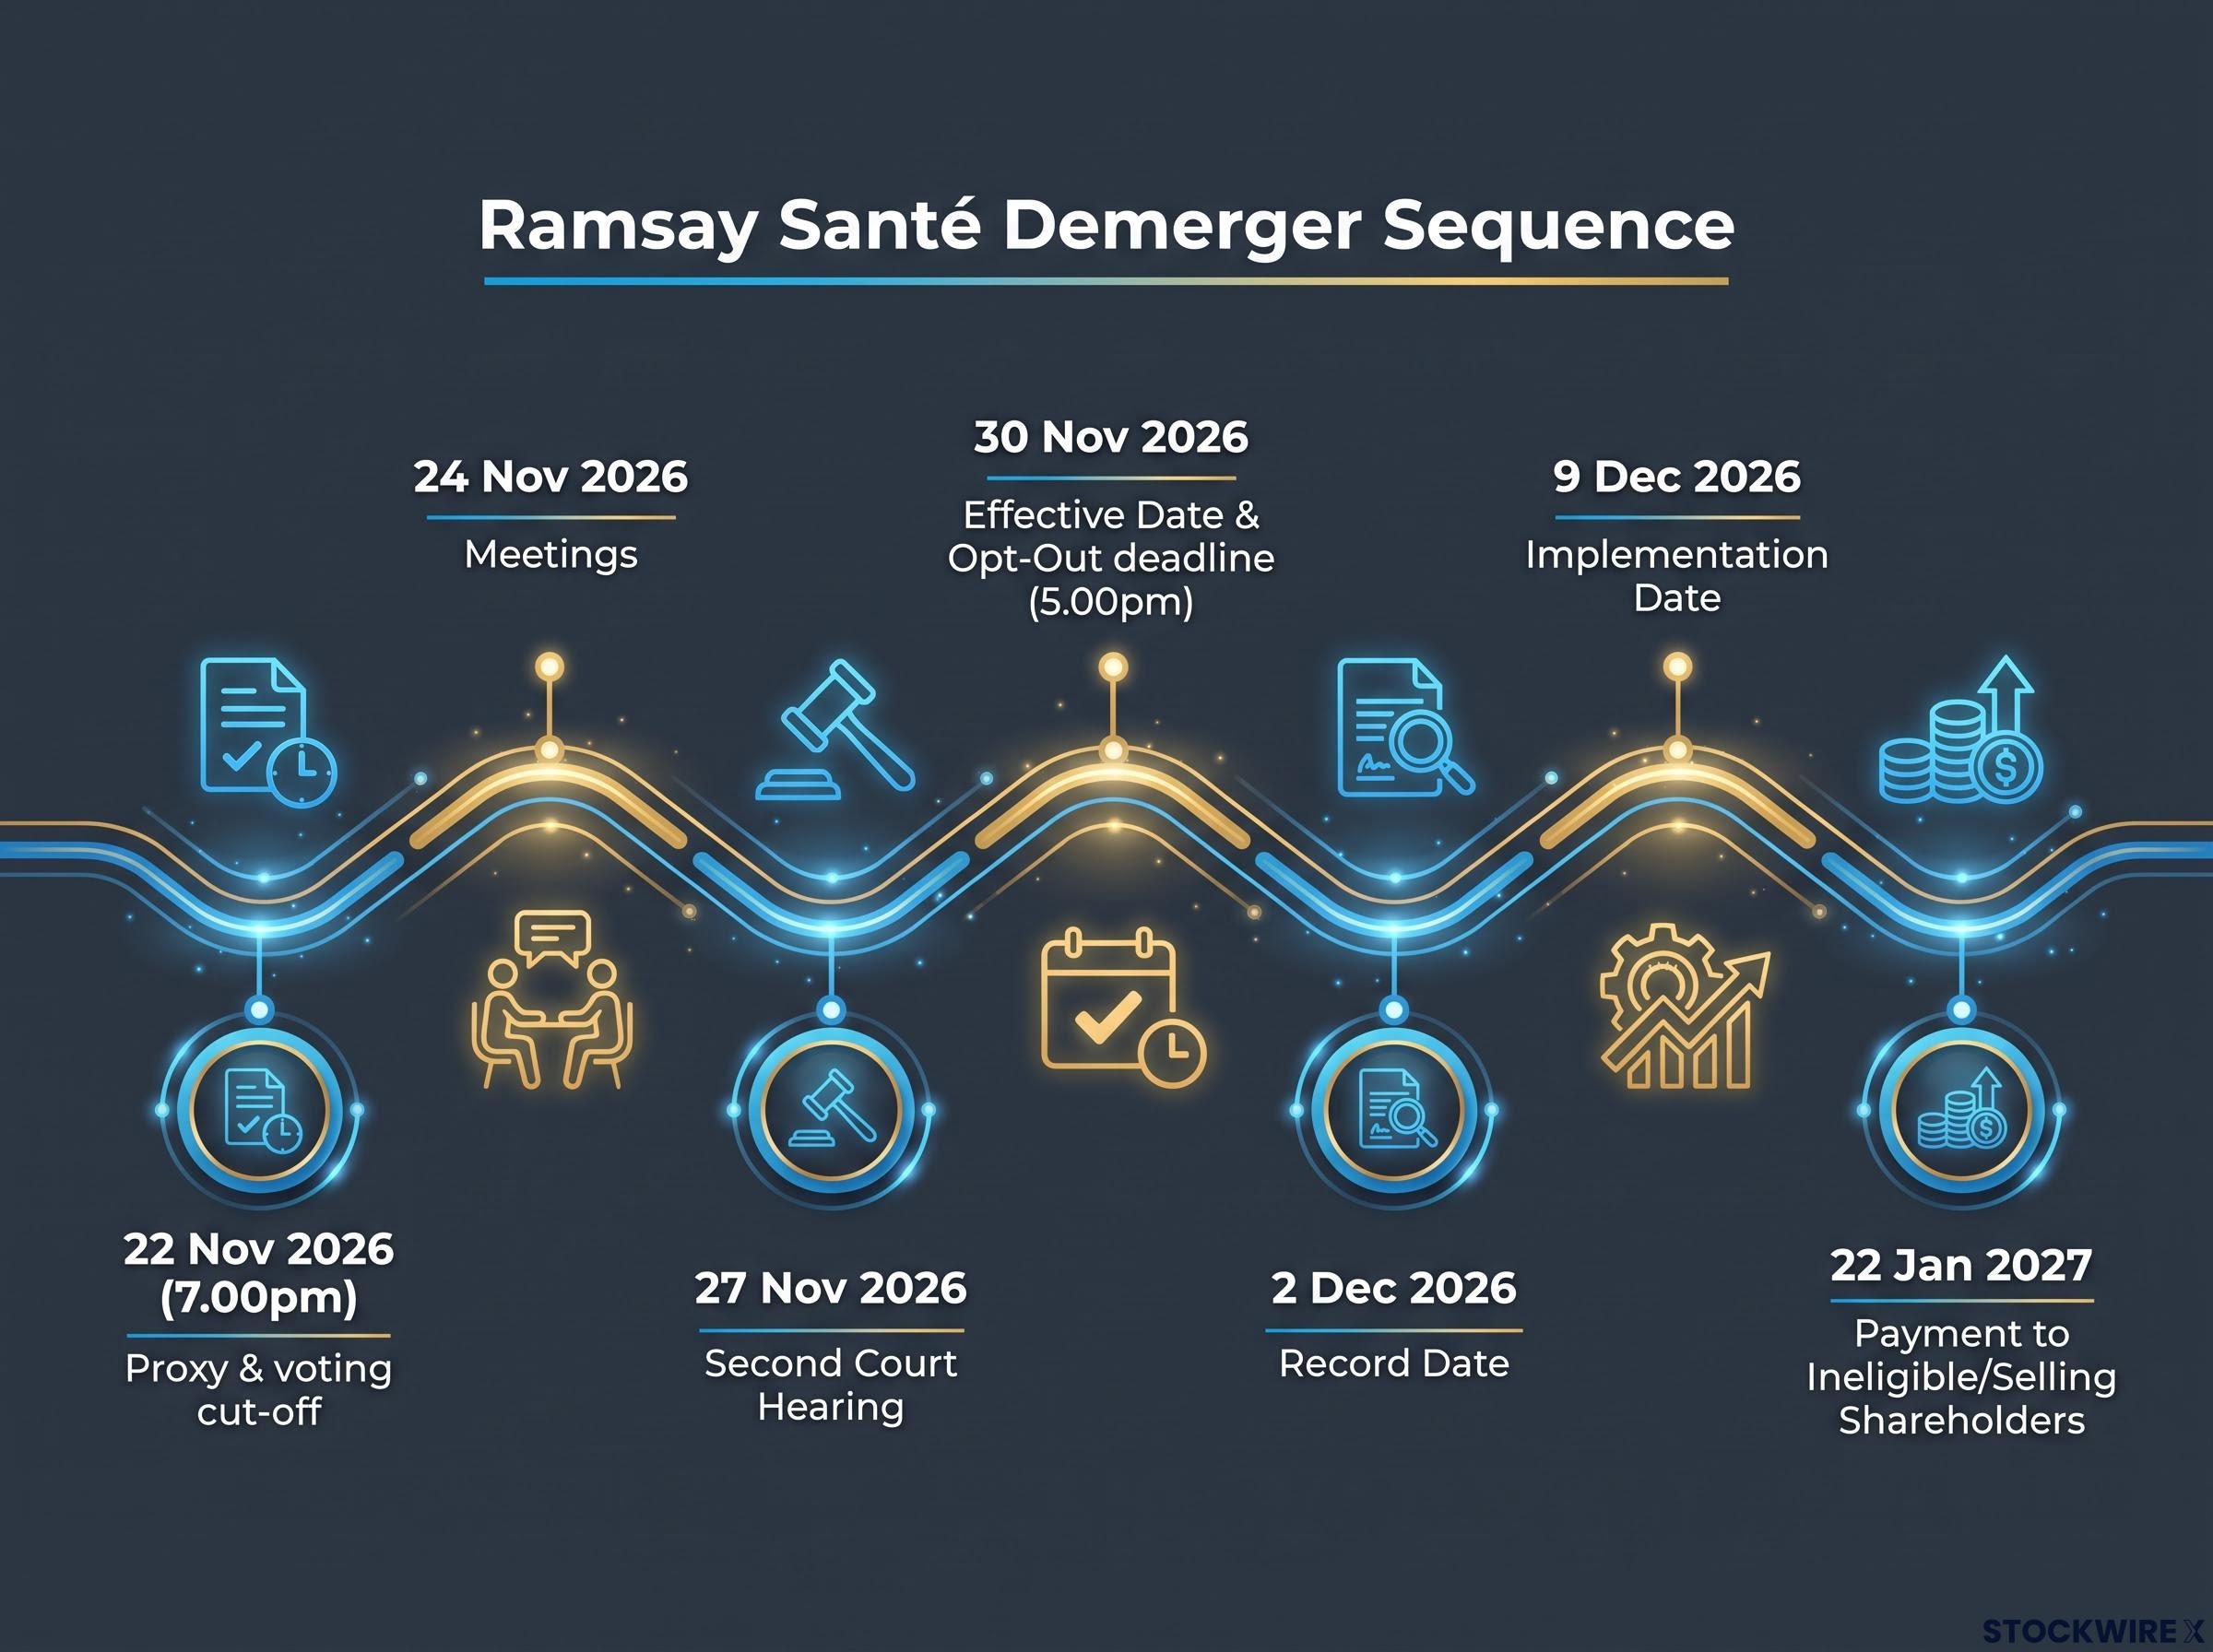
Key dates and next steps
| Event | Date |
|---|---|
| Proxy and voting eligibility cut-off | 7.00pm, 22 November 2026 |
| Meetings | 24 November 2026 |
| Second Court Hearing | 27 November 2026 |
| Opt-Out deadline (Small Shareholders) | 5.00pm, 30 November 2026 |
| Effective Date | 30 November 2026 |
| Record Date | 2 December 2026 |
| Implementation Date | 9 December 2026 |
| Payment to Ineligible Overseas Shareholders and Selling Shareholders | 22 January 2027 |
All dates after the meetings are indicative and subject to Court and regulatory approvals. The Capital Reduction Resolution requires more than 50% of votes cast. The Scheme Resolution needs a majority in number of shareholders voting plus at least 75% of votes cast.
Shareholders can watch the webcast, appoint a proxy by 7.00pm on 22 November 2026, or submit questions in advance by 5.00pm on 6 November 2026. The Shareholder Information Line is 1300 118 931 within Australia, or (+61) 2 9290 9697 internationally.
Get Healthcare News Before the Market Moves
Join 20,000+ investors receiving FREE breaking ASX healthcare news within minutes of release, complete with in-depth analysis and the full announcement. Click the “Free Alerts” button at Big News Blast to get market-moving updates in your inbox the moment news breaks.