
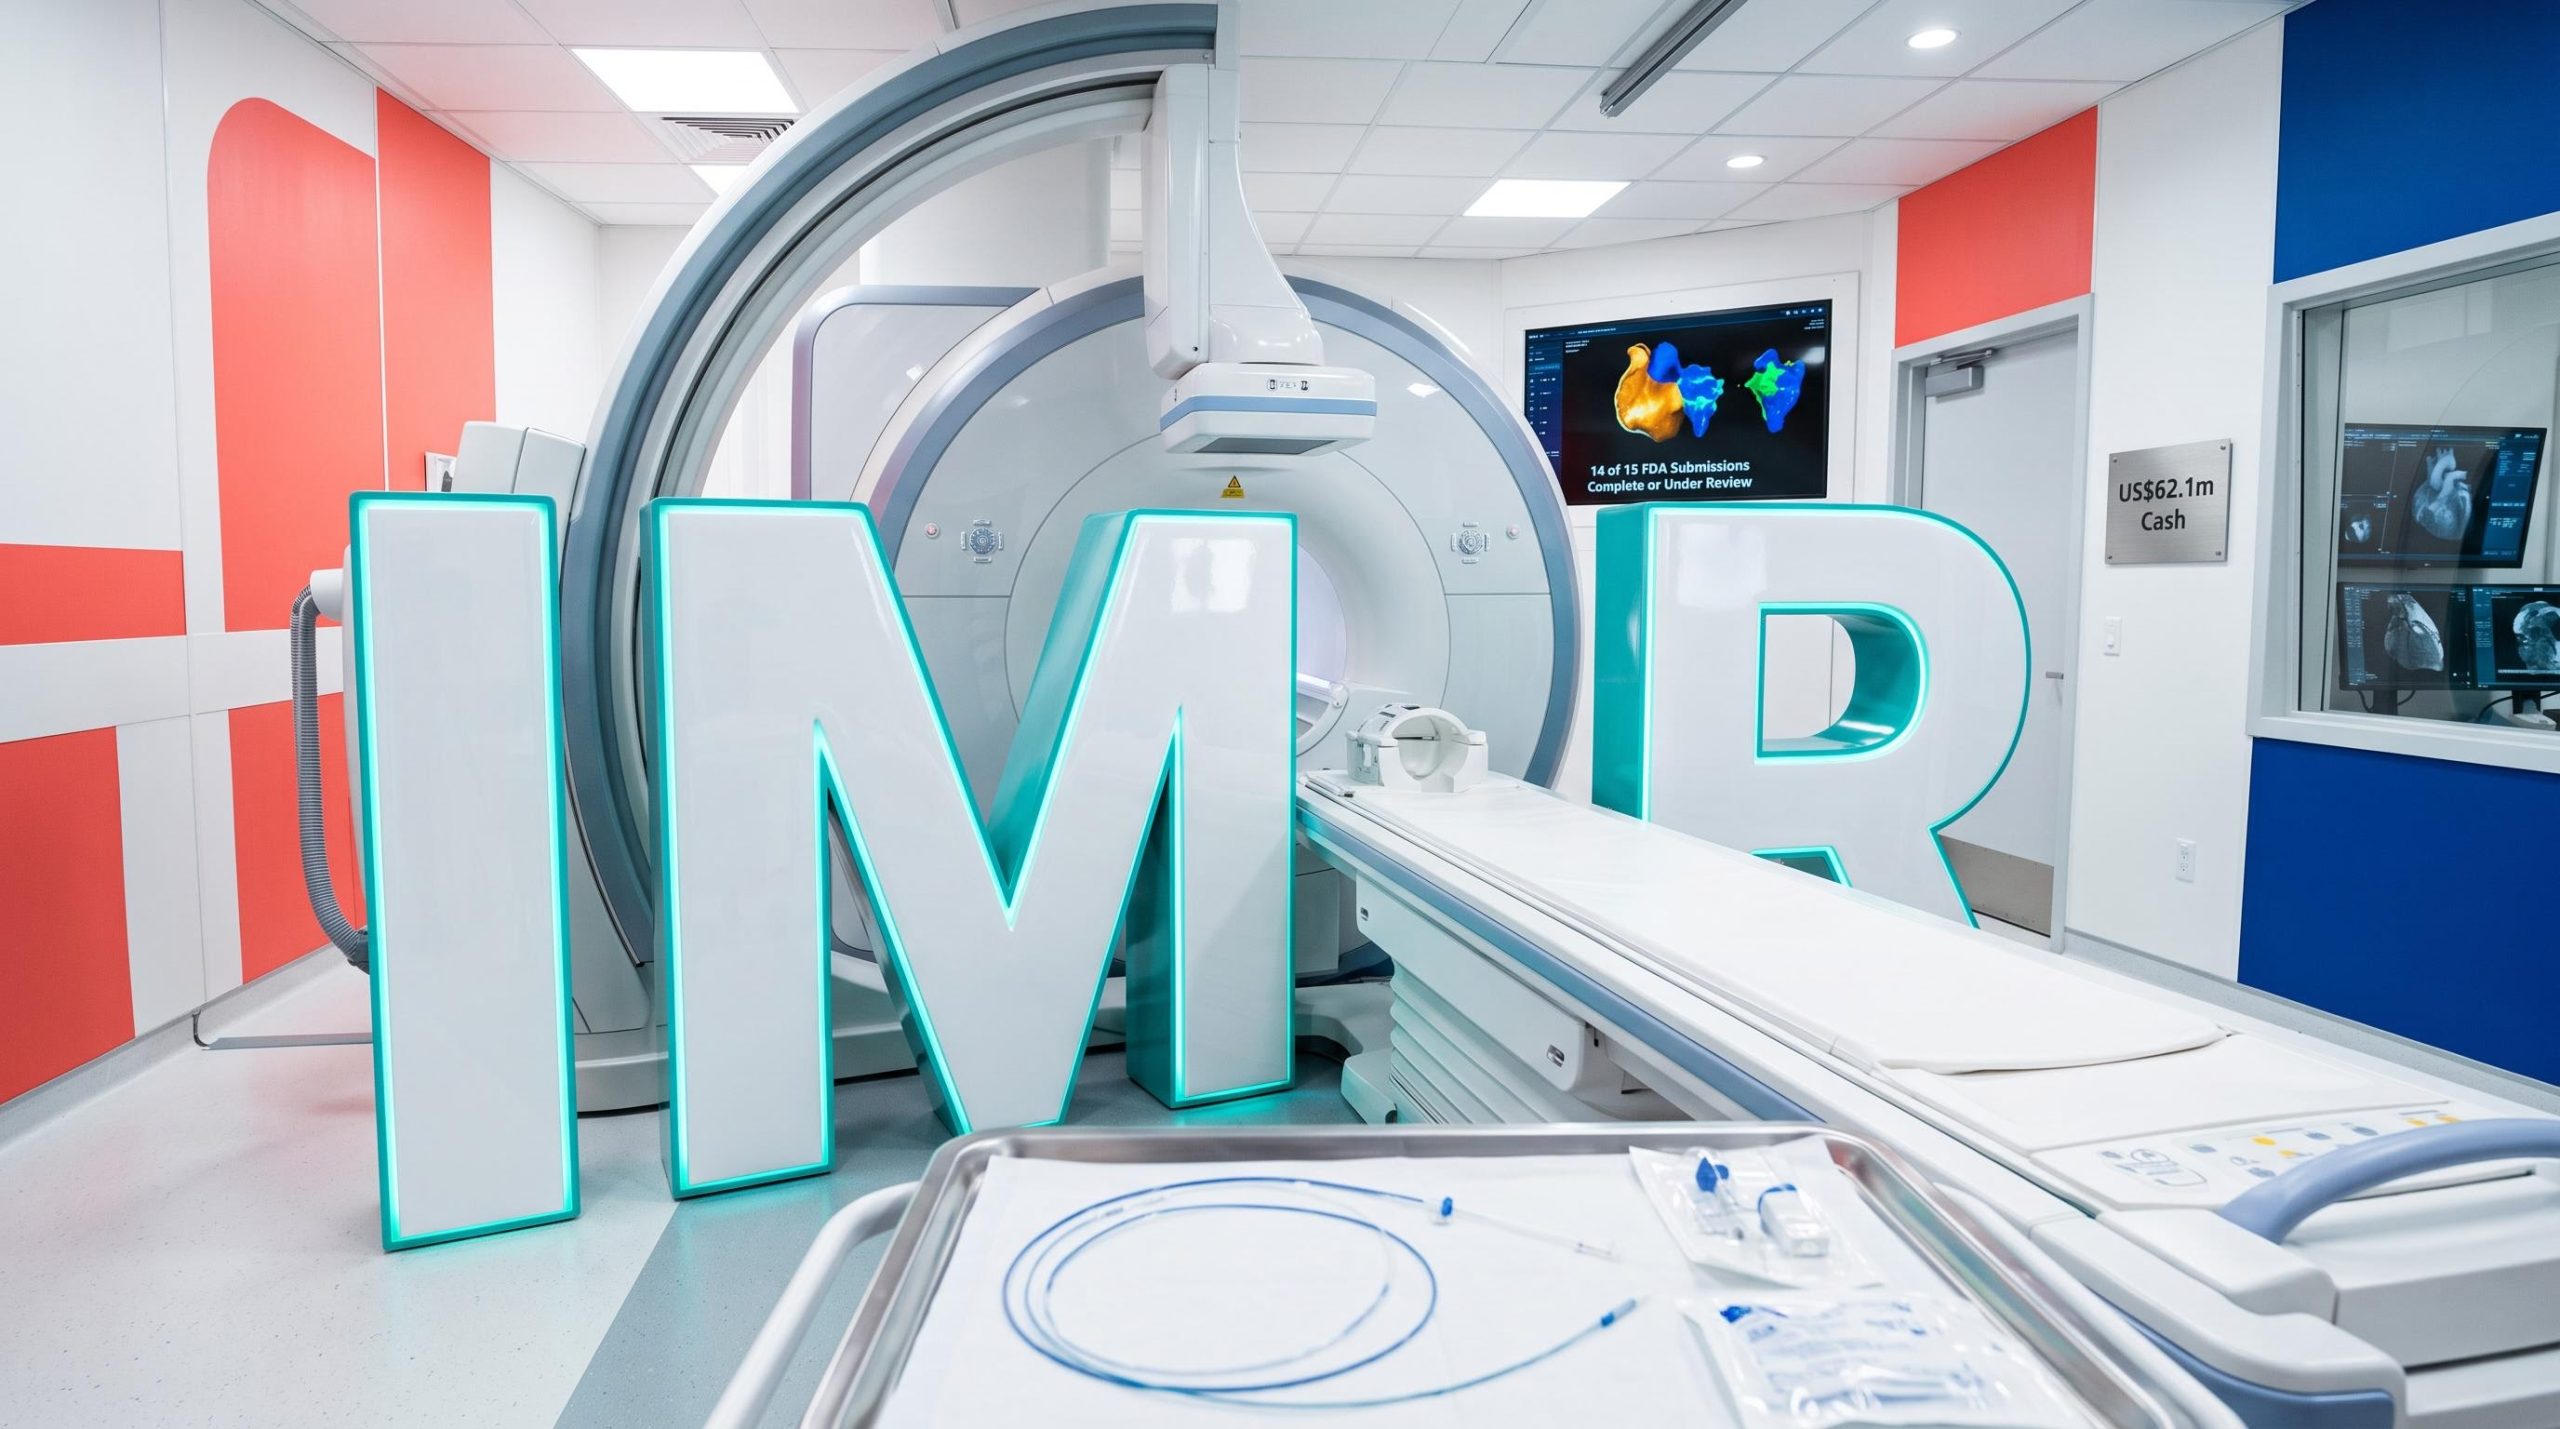
In its Q3 result webinar presentation, Imricor outlines U.S. launch progress and US$62.1m cash position in Q3 CY2026 update
In its Q3 result webinar presentation on 13 November 2026, Imricor Medical Systems (ASX:IMR) outlined an underway U.S. commercial launch of its interventional MR (iMR) platform, with 2 U.S. hospital customers, both leading children’s hospitals. Management pointed to Q3 CY2026 revenue of US$188k, up 437% on the prior comparative period (pcp), and cash of US$62.1m / A$90m at 30 September 2026 (FX AUD/USD 0.69).
The company highlighted four headline figures from the quarter:
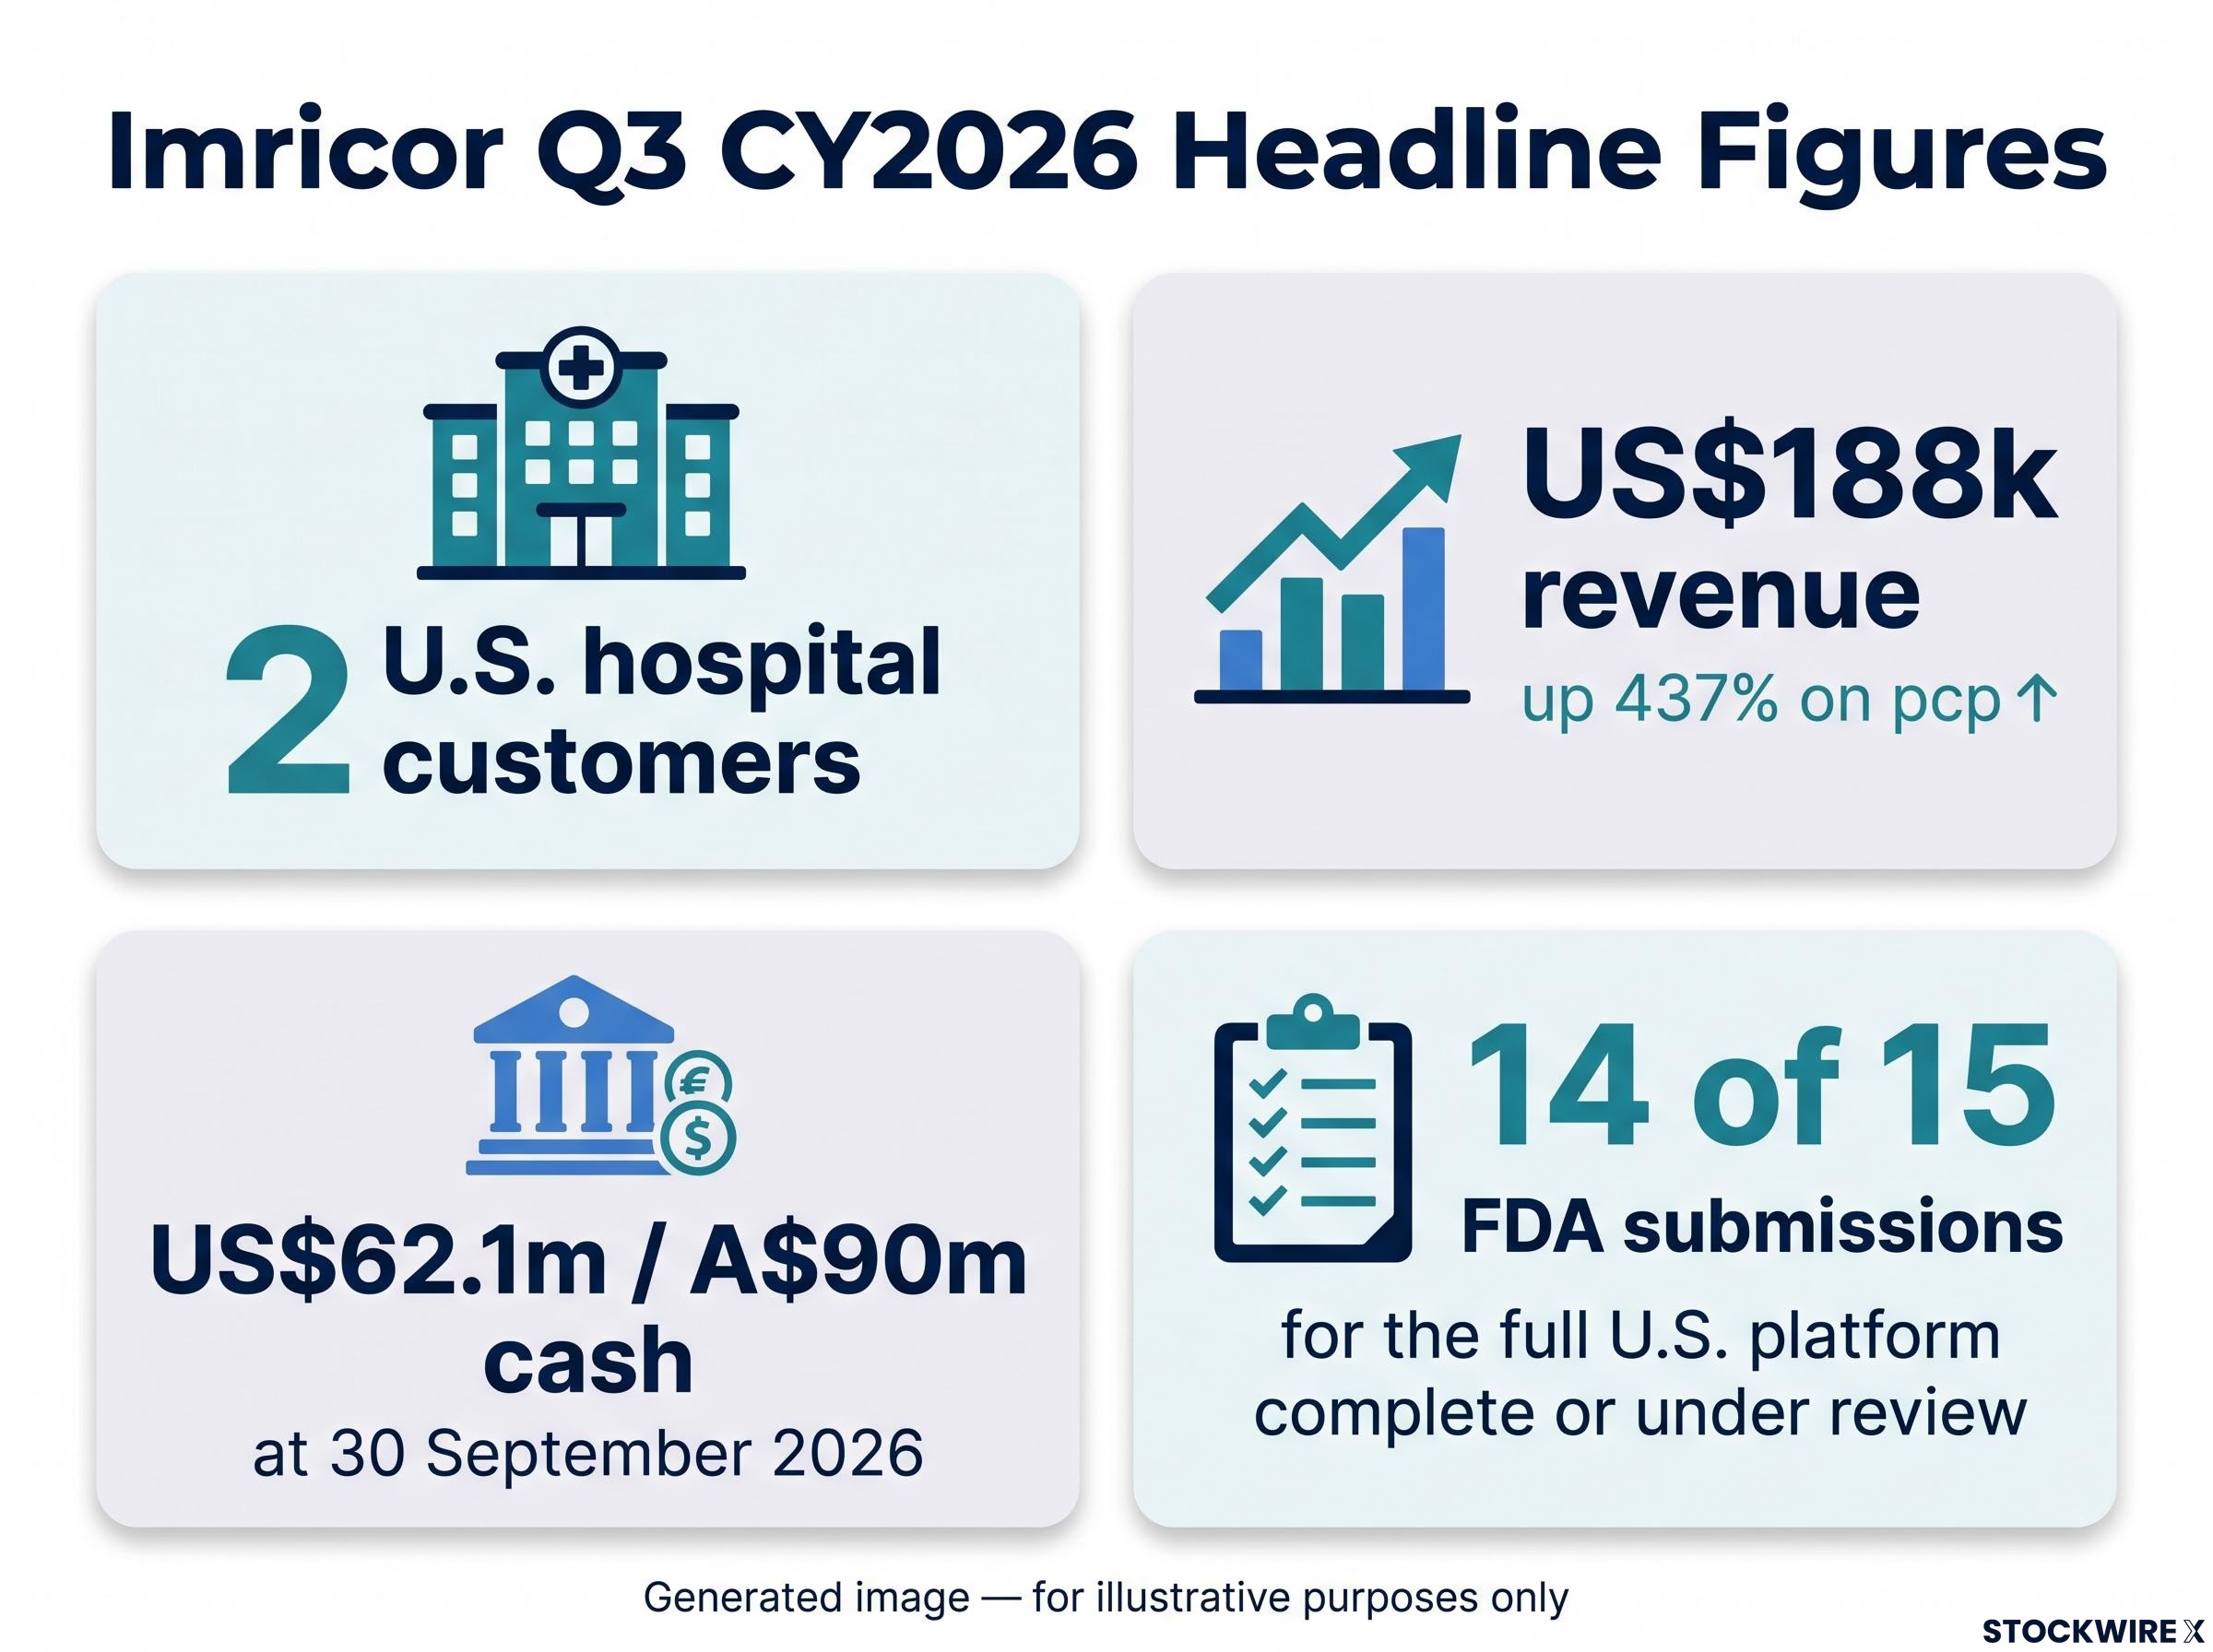
- 2 U.S. hospital customers
- US$188k revenue, up 437% on pcp
- US$62.1m / A$90m cash at 30 September 2026
- 14 of 15 FDA submissions for the full U.S. platform complete or under review
Rady Children’s Hospital-San Diego is the first U.S. customer, establishing the first U.S. commercial iMR cardiac catheterisation program. Children’s Medical Center Dallas followed two weeks after launch, which management described as the first commercial outcome of Philips compatibility.
The Dallas installation occurred after quarter end, and its revenue will be recognised in Q4.
Management also said Imricor Cardiovascular has launched, opening a U.S. market of 250+ children’s and 2,000+ adult hospitals. Under Imricor Finance with DLL, hospitals can finance over 1-7 years, with Imricor paid in full upfront.
When big ASX news breaks, our subscribers know first
Regulatory progress: 14 of 15 FDA submissions complete or under review
Management framed the regulatory position as 20 years of work nearing completion, with 14 of 15 submissions for the full U.S. platform now complete or under review. Pediatric label expansions under the 510(k) pathway mean NorthStar and the Vision-MR Diagnostic Catheter are now cleared for patients of all ages.
The submission of NavTrac and NavTrac-MR completes all 510(k) submissions. Separately, the PMA manufacturing module for the Vision-MR Ablation Catheter was accepted and closed by the FDA, covering 7 products.
The FDA’s Module 3 review, covering the largest piece of the PMA, flagged a single software deficiency tied to the RF-5000 System’s third-party operating system and none for the ablation catheter itself.
The table compares status at the FY25 result (February 2026) with November 2026.
| Device / submission | Pathway | Status at FY25 result (Feb 2026) | Status Nov 2026 |
|---|---|---|---|
| Pediatric label expansions (NorthStar, Vision-MR Diagnostic Catheter, Vision-MR Diagnostic Cable) | 510(k) | Pending | CLEARED |
| NavTrac-MR items (Steerable Introducer and Dilator, Cable, Steerable Introducer and Dilator for x-ray use) | 510(k) | Pending | Submitted |
| Vision-MR Ablation Catheter 2.0 / Cable Set 2.0 / RF5000, PMA Modules 1 and 2 | PMA | Submitted | CLOSED successfully |
| Vision-MR Ablation Catheter 2.0 / Cable Set 2.0 / RF5000, PMA Module 3 | PMA | Pending | Submitted |
| Vision-MR Ablation Catheter 2.0 / Cable Set 2.0 / RF5000, PMA Module 4 | PMA | Pending | Pending |
Q3 CY2026 financial performance and balance sheet
Loss narrows on fair value movement
Revenue of US$188k (pcp US$35k) came from the first U.S. NorthStar sale. Net loss after tax was US$2.9m, down 17% on pcp, which management attributed to the fair value movement of the convertible note, which does not have a direct impact on future cashflow.
Underlying net loss after tax was US$7.65m (pcp US$5.39m), and EBITDA was (US$8.04m) against (US$5.60m). Two cost lines drove the higher expenses:
- Costs and non-R&D expenses rose to US$4.0m, primarily due to higher staffing costs.
- R&D expenses rose to US$4.22m, due to higher staffing and professional services costs.
Cash and balance sheet
Cash and cash equivalents stood at US$62.1m, compared with US$19.5m at 31 December 2025. Total cash and marketable securities increased 36% versus pcp.
Operating cash outflow was US$7.33m, while a financing inflow of US$2.17m reflected proceeds from CDI options exercised in July. The convertible note, held at fair value under US GAAP, had outstanding principal and interest of US$7.1m at 30 September, and total equity was US$33.8m.
| US$’000 | Q3 2026 | Q3 2025 |
|---|---|---|
| Revenue | 188 | 35 |
| EBITDA | (8,039) | (5,595) |
| Net loss after tax | (2,910) | (3,494) |
| Operating cash flows | (7,333) | (4,820) |
| Total cash and marketable securities | 62,100 | 45,745 |
Philips partnership and what iMR means for the platform
The Philips Compatibility Declaration opens the Philips MR installed base to NorthStar for the first time, in the U.S. and Europe. The presentation also detailed a joint turnkey cardiac iMR lab on the Philips 1.5T BlueSeal platform, showcased at ESC Congress 2026, following fourteen years of joint development.
Philips has extensive sales channels in Europe and the U.S. to scale the rollout of iMR labs. Features of the lab highlighted by management include:
The turnkey cardiac iMR lab pairs Philips’ helium-free scanner with Imricor’s capital systems and single-use catheters in one purpose-built environment, and it was launched as a commercial offering in CE-marked markets.
- 7 liters of sealed helium, versus about 1,500 liters in a conventional scanner
- No quench pipe, so no external wall is needed
- Wide bore at 1.5T, giving patient access without losing image quality
- NorthStar controls the MR scanner and tracks Imricor’s active catheters
Management also pointed to AIM-iMR 2026 in Amsterdam, the first international meeting devoted entirely to interventional MR. It was organised by the medical community, with Imricor and Philips as co-sponsors.
What is interventional MR (iMR)?
Interventional MR is a new medical field in which doctors use magnetic resonance (MR) imaging to guide procedures inside the body. Imricor’s platform has three parts: MR-safe equipment (the Advantage-MR EP Recorder/Stimulator), software (the NorthStar Mapping System) and single-use consumables (the Vision-MR ablation and diagnostic catheters).
It spans electrophysiology, which covers atrial flutter, AFib and VT ablation, and cardiac catheterisation, launched in 2026. Single-use consumables are used once per procedure, so each procedure performed creates a need for new catheters. That repeatable model is relevant to the commercial launch because installed systems can be paired with ongoing consumable sales.
Investment highlights management outlined
Management closed the presentation with seven investment highlights:
- Global leader in MR conditional systems and devices
- US$15bn market growing at 15%
- No competition
- Safety tailwinds with rising concerns about radiation exposure
- Close partnerships with MR manufacturers
- Strong balance sheet: US$62m / A$90m at 30 September
- Commercialising now in the US
Want Alerts Like This on the Healthcare Stocks You Follow?
StockWire X Market Intelligence scores every announcement in our coverage for how significant it’s likely to be for investors, and which way it points, then alerts you on the stocks you follow. The first 1,000 founding members lock in 50% off for life: A$247 a year instead of the standard A$495. Join the founding waitlist today.