
Finbar AGM 2026: all six resolutions carried as management outlines record pre-sales
In its 2026 AGM presentation on 11 November 2026 at Garden Towers, East Perth, Finbar Group outlined FY26 pre-sales of $567.2M and sales of $528.8M, up 124% on FY25’s $236M.
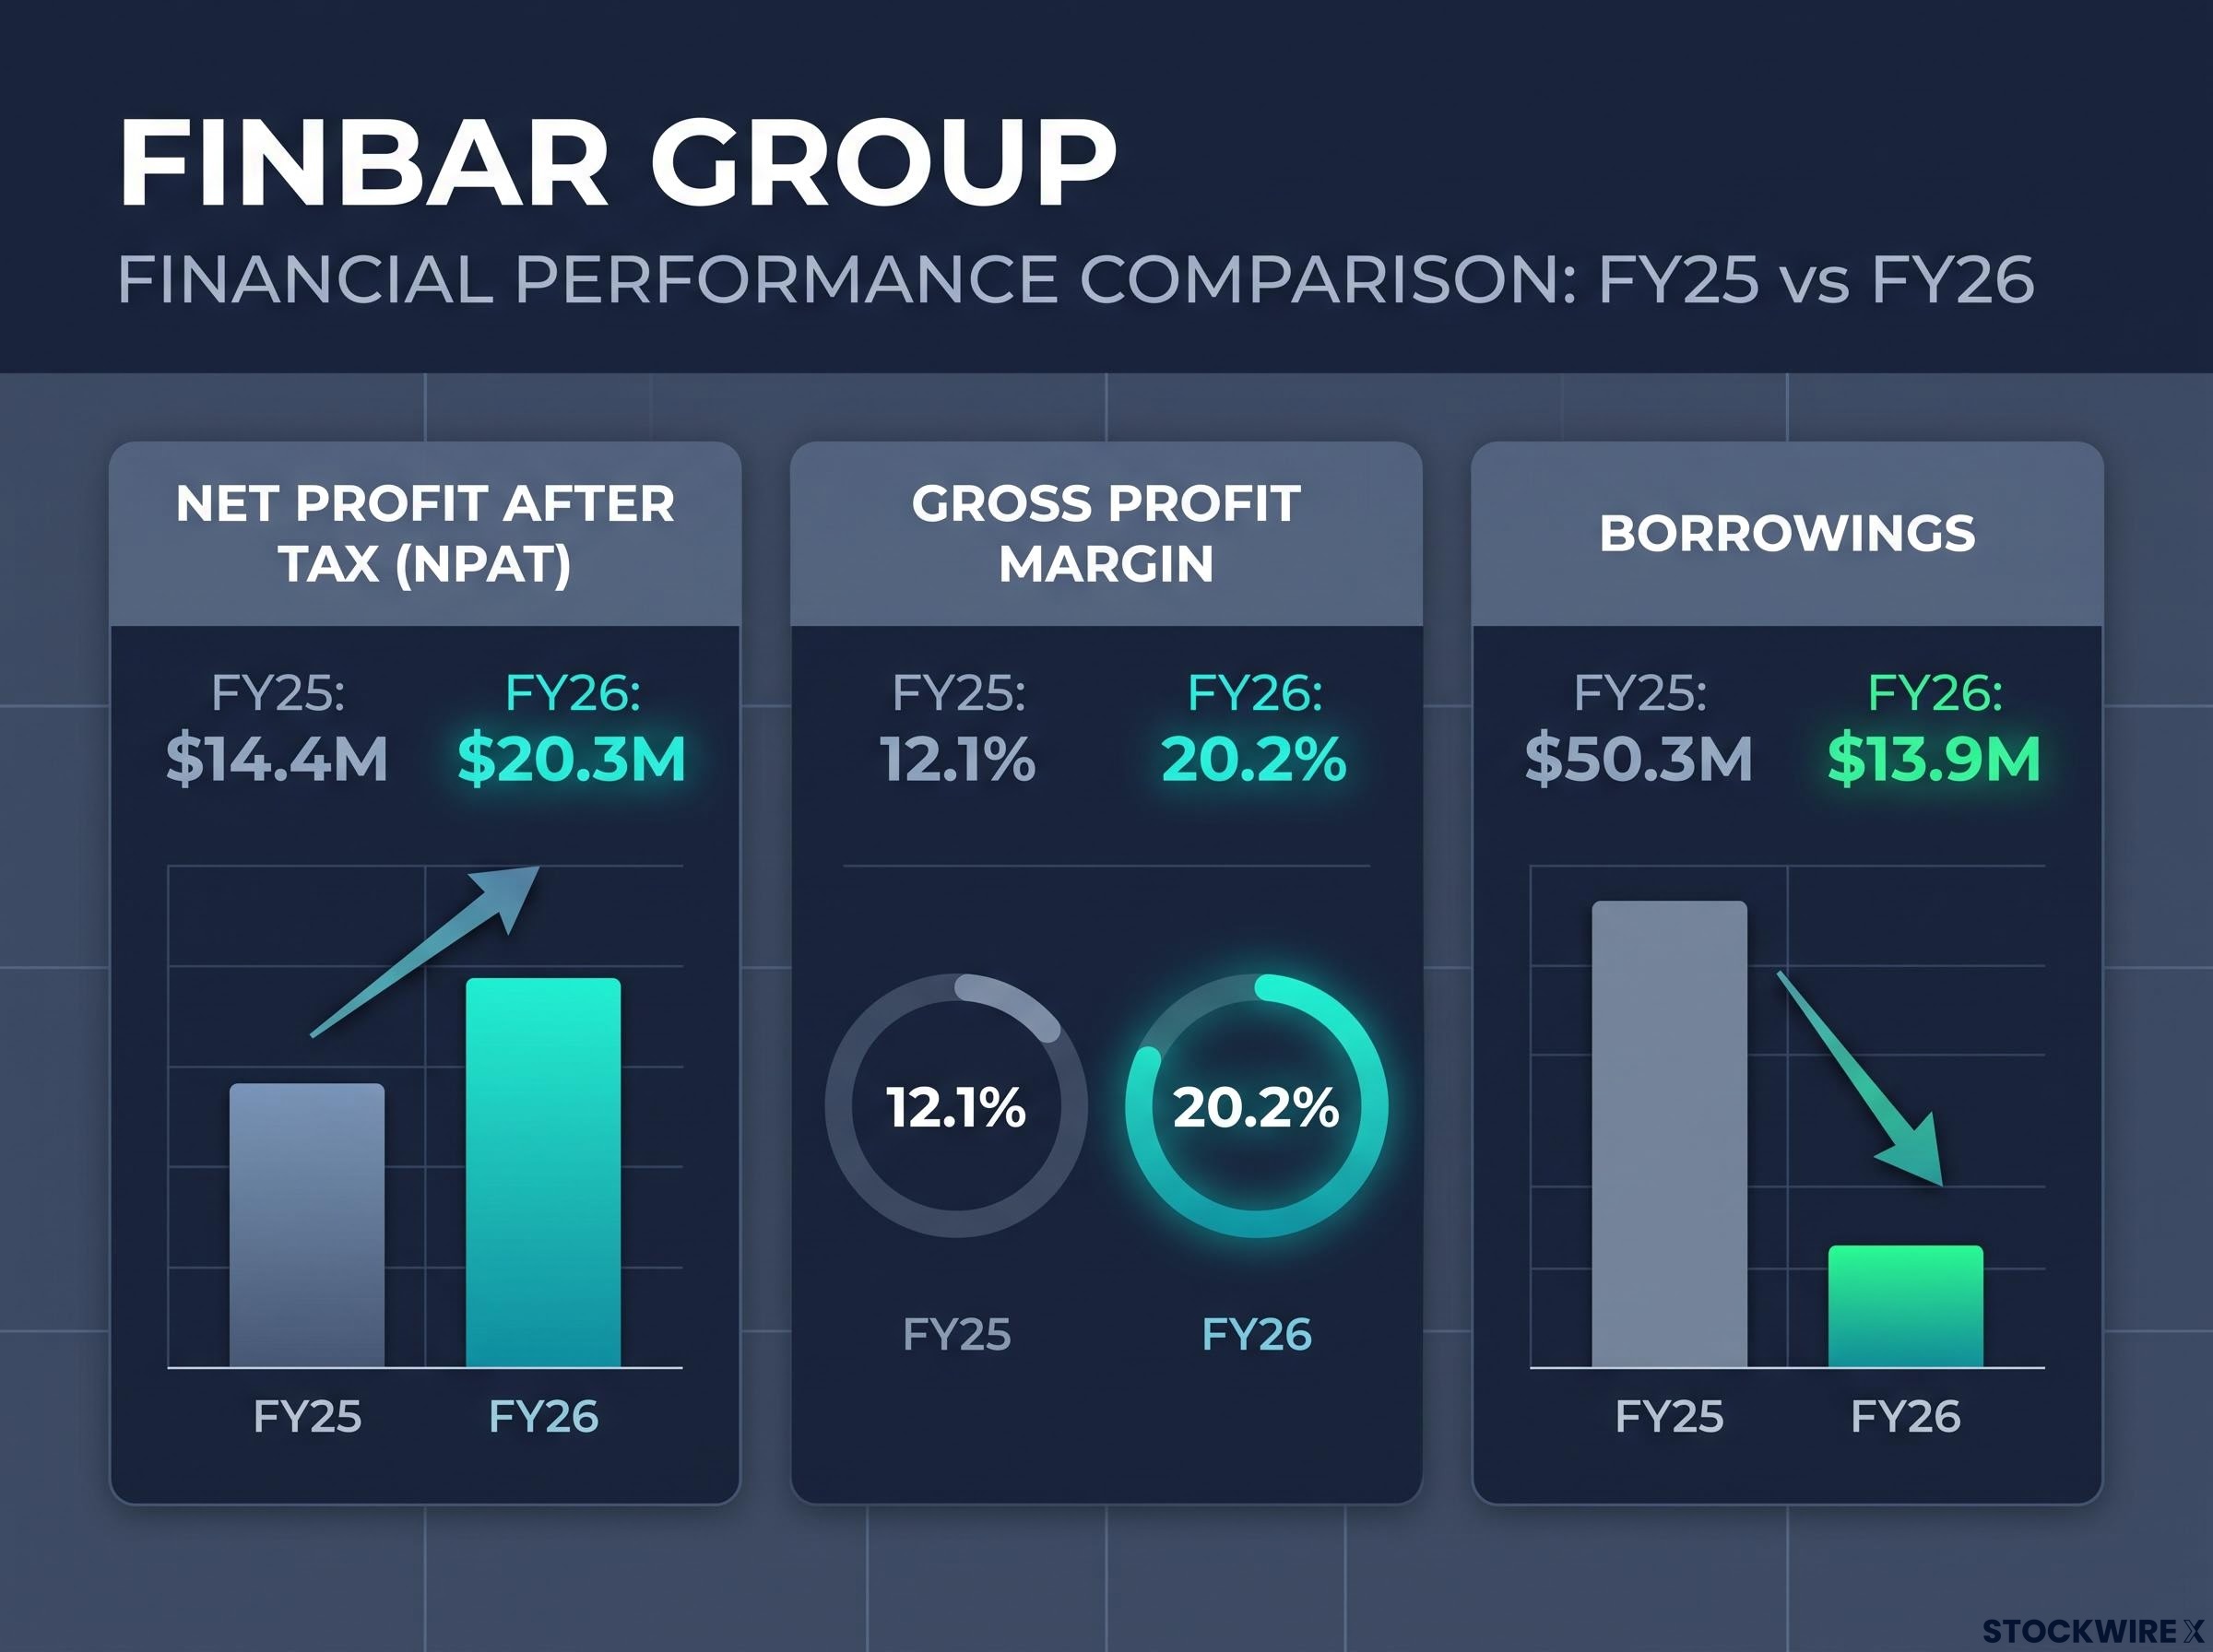
Management also recapped an FY26 NPAT of $20.3M (FY25 $14.4M) and borrowings down to $13.9M.
Valid proxy forms were received from 99 shareholders representing 161,436,998 shares, or 59.3% of total issued shares. Each resolution below is described by the proportion of proxy votes received in favour.
Proxy votes at a glance
| Resolution | For | Against | Open-Usable | Abstain |
|---|---|---|---|---|
| 1. Remuneration Report (non-binding) | 98.87% | 0.27% | 0.86% | 4,694,441 |
| 2. Appointment of Deloitte Touche Tohmatsu as auditor, with effect from the resignation of KPMG | 99.73% | 0.00% | 0.27% | 15,053 |
| 3. Re-election of Mr John Chan | 98.22% | 1.51% | 0.27% | 20,089 |
| 4. Re-election of Mr Ronald Kean Yew Chan | 98.14% | 1.57% | 0.29% | 20,089 |
| 5. Re-election of Ms Melissa Siew Ching Chan (appointed by the Board as an additional Director with effect from 2 March 2026) | 98.07% | 1.66% | 0.27% | 20,089 |
| 6. Increase to Non-executive Director fee pool by $240,000 to $600,000 per annum (inclusive of superannuation contributions), effective from the financial year commenced 1 July 2026 | 98.27% | 0.78% | 0.95% | 113,810,591 |
When big ASX news breaks, our subscribers know first
FY26 results and operational highlights presented
Management pointed to a profit and balance sheet turnaround, with NPAT rising while borrowings fell sharply. Key FY26 figures, with FY25 comparisons in brackets:
- Total revenue of $204.3M ($284.5M, down 28.2%)
- NPAT of $20.3M ($14.4M) and Underlying NPAT of $22.1M ($16.2M)
- Earnings per share of 7.4 cents (5.3 cents) and NTA per share of 94 cents (92 cents)
- Gross profit margin of 20.2% (12.1%)
- Cash and term deposits of $50.7M ($36.4M) and borrowings of $13.9M ($50.3M)
- Final dividend of 3c fully franked
Underlying NPAT removes the impact of yearly variation in the valuation of the property portfolio.
| Metric | FY26 | FY25 |
|---|---|---|
| Settlements | 287 lots, valued at $263.7M | 351 lots at $352M |
| Sales | 566 lots, $528.8M | $236M |
| Pre-sales | $567.2M | $294.1M |
| Under construction (end value) | 615 lots, $515.1M | $391M |
For FY27 to 31 October 2026, the presentation showed pre-sales of $395M, sales of $74.4M and settlements of $231.7M, including projects such as Bel-Air and Garden Towers.
Investors exploring the earnings detail behind the margin expansion can read our detailed coverage of Finbar’s FY26 full-year results, which breaks down the debt reduction, the Bel-Air loan repayment and the settlement outlook for Garden Towers.
Customer mix shows investor demand and loyalty
For CY2026 to 31 October, investors versus owner occupiers averaged 53:47. Investor shares were higher for the launches of Romeo Applecross (65%), Palmyra West (45%) and Parkside (72%).
Key buyer metrics for the period:
- First home buyers represented 18% of sales, up from 9% in 2023
- Repeat buyers accounted for 27% of sales
- Referred buyers accounted for 21% of sales
The presentation attributed the strong repeat buyer profile to effective leveraging of Finbar Loyalty Club membership and brand capital.
Development pipeline and market positioning
A $1.7B+ five-year pipeline
The presentation described a $1.7B+ five-year development pipeline. Current and recent projects were shown as follows.
| Project | Location | Value | Units | Sales status |
|---|---|---|---|---|
| Garden Towers (completed October 2026) | East Perth | $298m | 342 units | 81% sold |
| Riverbank | Rivervale | $119m | 143 units | 97% sold |
| Palmyra West | Palmyra | $100m | 130 units | 85% sold |
| Romeo | Applecross | $192m | 155 units | 67% sold |
| Parkside | Rivervale | $73m | 108 units | 28% sold |
Next pipeline projects, with launch timing:
- Leeder (West Leederville, $266m): launch to market H1 FY27
- Ascot ($166m): launch to market H2 FY27
- Lyall Street (South Perth, $245m): launch to market H2 FY27
- Bowman Street (South Perth, $402m): launch to market H1 FY29
- ABC Heritage (East Perth, $142m): launch to market H2 FY30
Perth market backdrop
The presentation cited WA population growth of 2.1% a year, compared with 1.4% nationally. Perth unit values rose 3.9% over the twelve months to October 2026, while dwelling values fell 5.7% over the three months to October, moderating 8.9% below the April 2026 peak.
Median unit value was approximately $692,000, against $982,000 for houses, and unit rents increased 6.9% over the year to October. Higher interest rates were described as tempering near-term demand.
On track record, Finbar has completed 81 projects comprising 7,945 units, with 31 consecutive years of profit and a 100% completion success rate.
What happens next for Finbar
The presentation set out the following indicative timelines, which are subject to change:
- Romeo Applecross: anticipated completion 1H FY29.
- Palmyra West: anticipated completion 2H FY27.
- Riverbank: anticipated completion 1H FY28.
- Parkside: anticipated completion 2H FY28.
- Leeder Residences: commencement of presales projected in Q2 FY27, with launch to market in H1 FY27.
- Ascot and Lyall Street: launch to market H2 FY27.
- Bowman Street: launch to market H1 FY29.
- ABC Heritage: launch to market H2 FY30.
The Leeder Residences approval covers a 244-apartment twin-tower scheme opposite West Leederville train station, with construction completion targeted for 2H CY2029.
Ready To Explore Finbar’s $1.7B+ Development Pipeline?
Finbar has reported record FY26 pre-sales of $567.2M, a 124% lift in sales and borrowings cut to $13.9M. Projects such as Garden Towers, Romeo Applecross and Leeder Residences are shaping its next phase of growth.
Investors can explore Finbar Group’s company profile and latest updates to see how the pipeline and settlement outlook may support future earnings.