
Count Group to acquire majority interest in Skybridge and raise $25.0 million
Count Group (ASX:CUP) has entered into a binding agreement for the acquisition of a majority interest in Skybridge Financial, alongside a fully underwritten institutional placement to raise approximately $25.0 million.
The company describes the deal as its “most significant equity partnership investment to date”. It accelerates the strategy to build Australia’s leading integrated wealth and accounting platform.
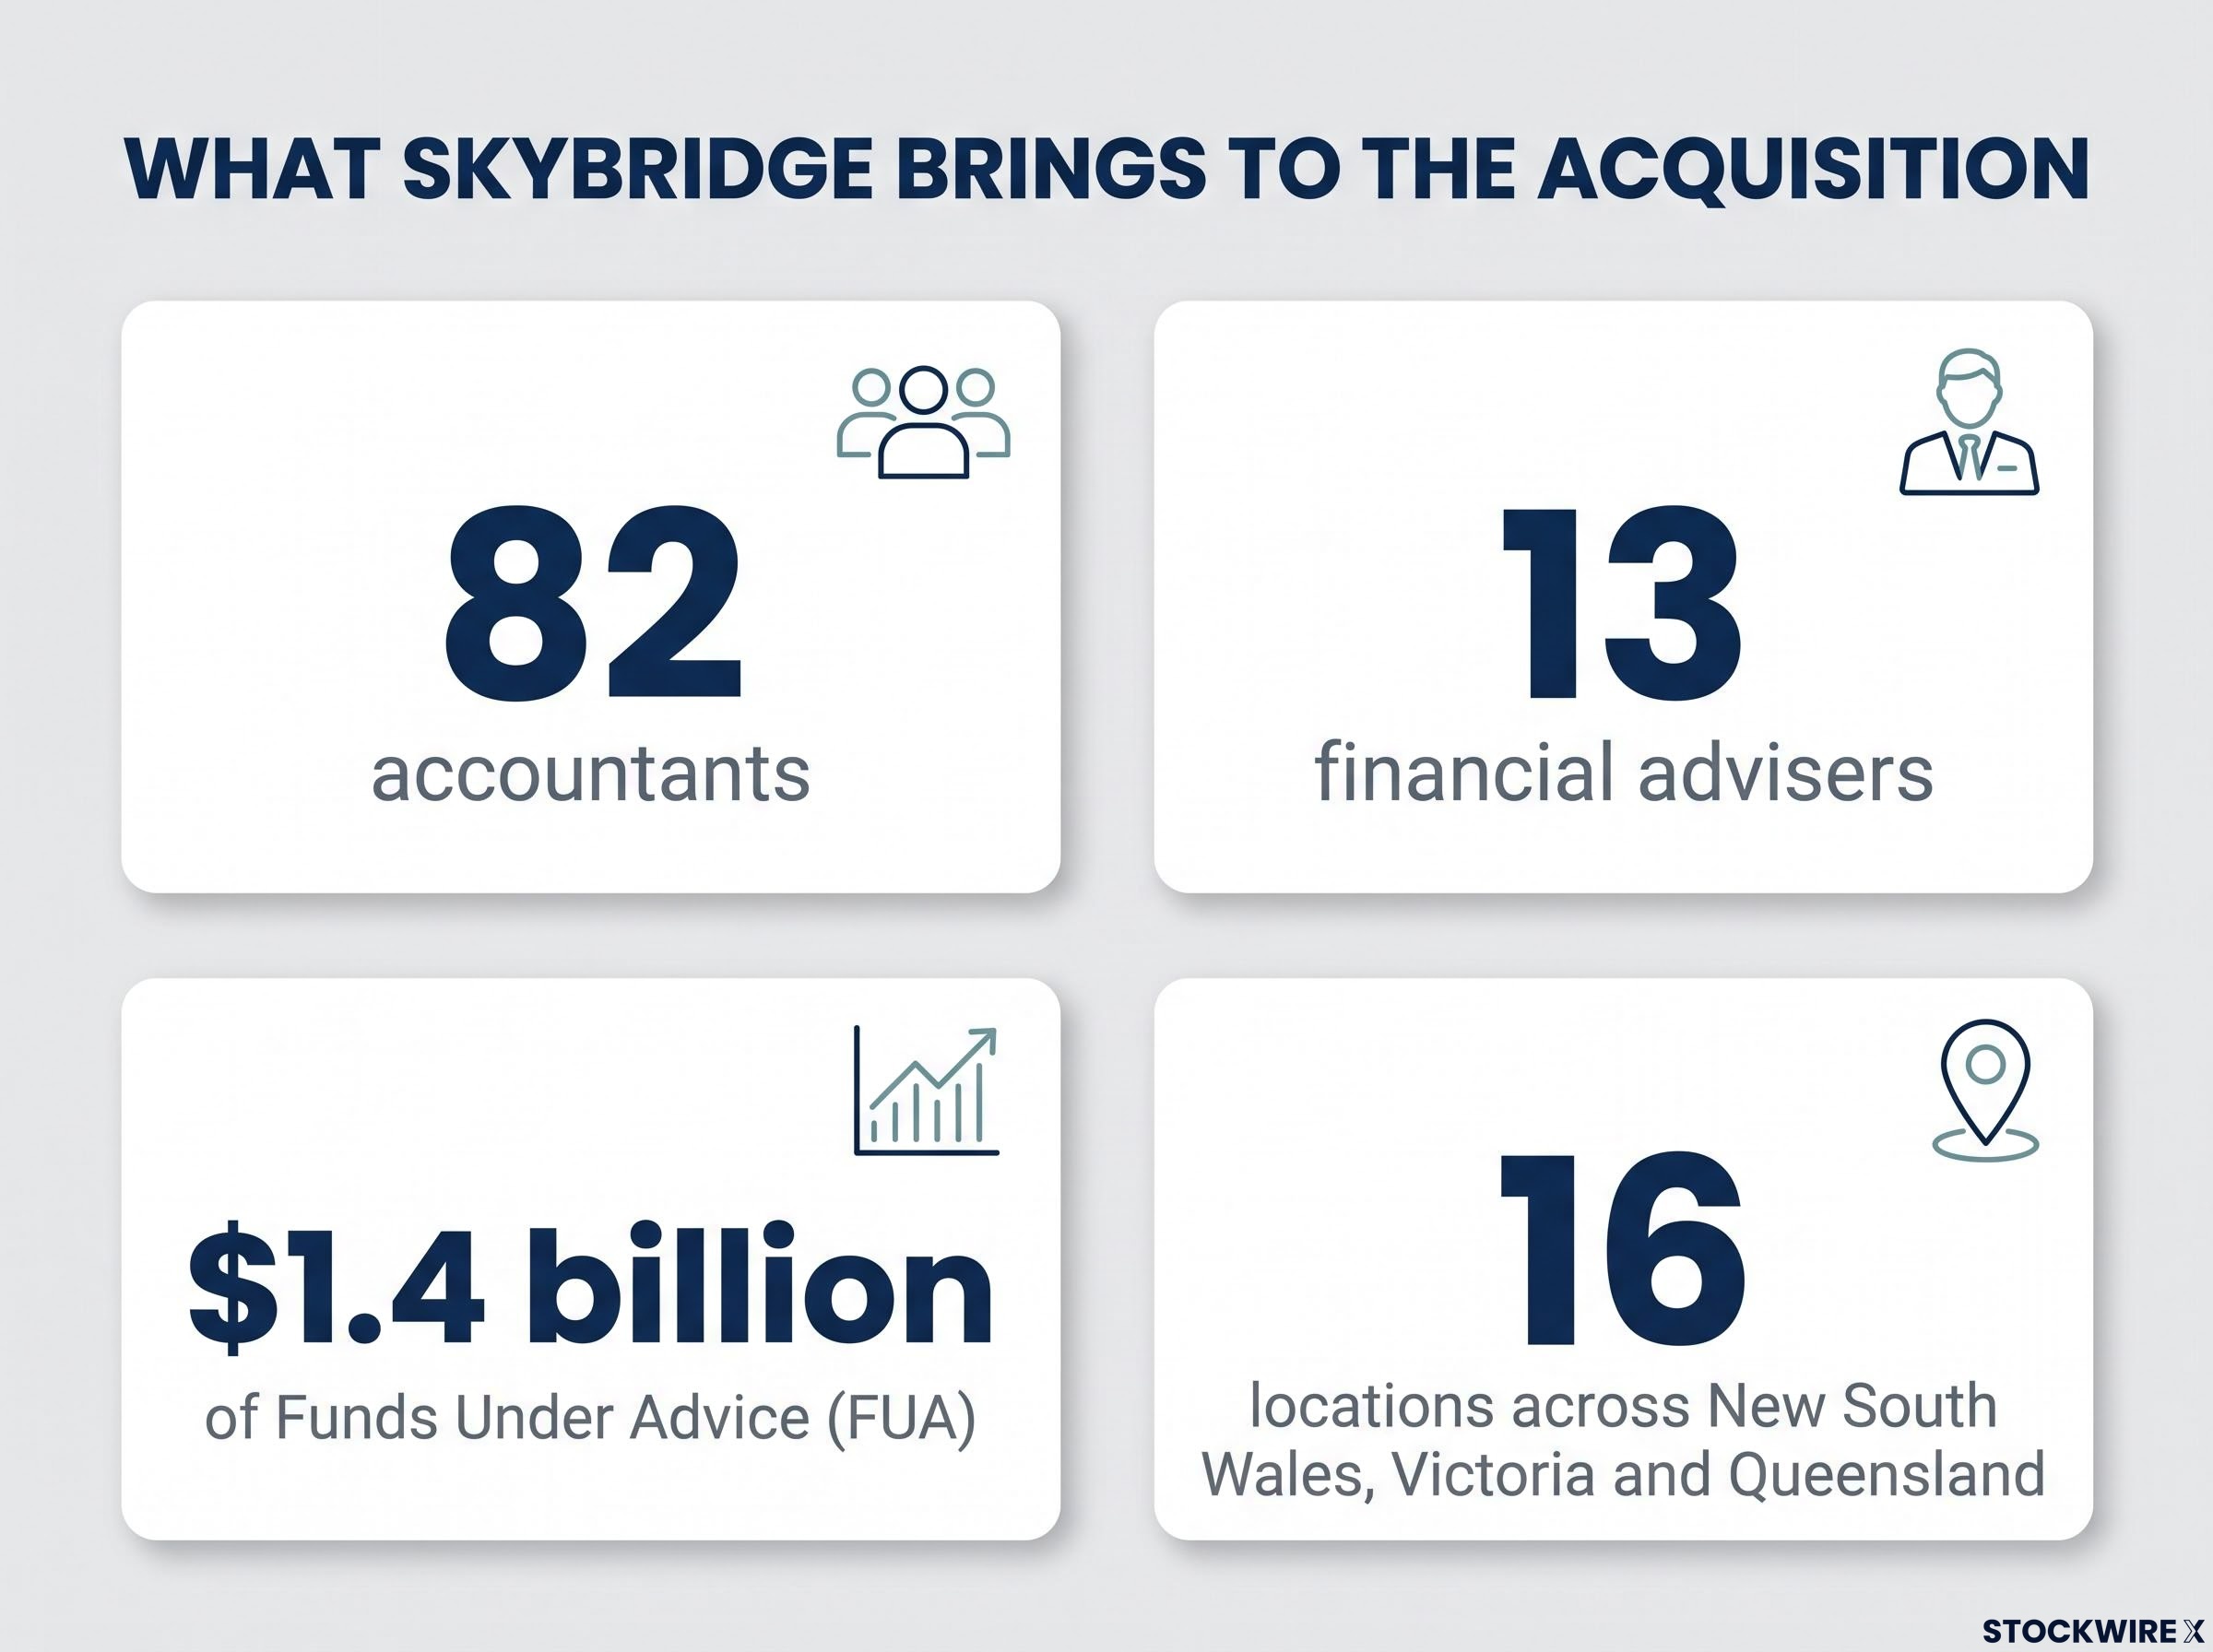
Skybridge brings:
- 82 accountants
- 13 financial advisers
- $1.4 billion of Funds Under Advice (FUA)
- 16 locations across New South Wales, Victoria and Queensland
For investors, the acquisition adds scale in both accounting and financial planning.
Hugh Humphrey, Chief Executive Officer
“…It delivers another step-change for Count Group’s scale in accounting and financial planning.”
When big ASX news breaks, our subscribers know first
Skybridge financials and deal terms
A high-margin earnings base
Skybridge delivered approximately $29.0 million of revenue and $8.8 million of Normalised EBITA in FY2026, a Normalised EBITA margin of approximately 30.3%. That compares with Count Group’s FY2026 pro forma underlying EBITA margin of 22.2% (including Oracle).
The FY2026 figures are pro forma, taking into account the full-year contribution of accounting acquisitions completed by Skybridge during FY2026.
The acquisition is expected to be mid to high single-digit EPS accretive pre-synergies on a FY2027F pro forma basis.
How the price is structured
Count Group will initially acquire a 75% interest, with a target of c.70% ownership through a sell-down to existing and new employee shareholders in time. Jason Birch will continue as Founder and Executive Director, and Grant Duddle will be appointed Managing Principal. Jason, Grant and employee shareholders will retain a 25% interest post-completion.
The deal implies an enterprise value for 100% of Skybridge of $66.0 million, or 7.5x the agreed deferred payment EBITA target of $8.8 million. Implied equity value for 100% of Skybridge is $43.9 million, subject to customary net debt and net working capital completion adjustments.
| Component | Amount | Timing / condition |
|---|---|---|
| Upfront cash | $25.6M | Upfront, subject to customary completion adjustments |
| Upfront scrip | $4.0M | Count shares issued at the Placement offer price, subject to 12-month escrow |
| Conditional Deferred Consideration | Up to $3.3M | Payable after the first 12-month period post-completion, subject to Normalised EBITA of $8.8M; any shortfall reduces the payment at 7.5x, floored at nil |
| First earn-out | Up to $2.8M | First 12-month period, Normalised EBITA between $8.8M and $9.3M |
| Second earn-out | Up to $3.0M | Second 12-month period, Normalised EBITA between $10.0M and $11.0M |
Skybridge’s budgeted EBITA is c.$9.8 million for FY2027B. At that level, the implied enterprise value for 100% of Skybridge would be approximately $69.8 million (inclusive of the first earn-out), an effective multiple of c.7.1x.
Why Skybridge fits Count Group’s strategy
The company outlined the following strategic benefits:
- Scaled equity partnership: Count Group’s largest equity partnership investment to date.
- Regional scale: a large, predominantly regional footprint that complements the existing network and provides capacity for incremental growth without impacting existing equity partnerships.
- AFSL: 13 employed advisers will join the Count Financial Australian financial services licence, allowing more time on clients and growth rather than licensee obligations.
- FUA synergies: approximately $1.4 billion in FUA, with Skybridge clients offered the opportunity to benefit from Count Group’s Investment Solutions.
- Flywheel: multiple pathways for organic growth through cross-referrals, adviser recruitment and Count services.
- Operating autonomy: Skybridge will continue to operate with a high degree of autonomy following completion.
- Platform for tuck-ins: Skybridge has completed more than 35 acquisitions since 2001 and operates a dedicated in-house integration team.
There is also potential synergy and earnings upside from services including technical helpdesk, actuarial certificates, tax training and outsourcing across Skybridge’s network.
Following the acquisition, Count Group will have 115 employed financial planners, 490 accountants and c.$44.4 billion in FUA.
The two groups share a history. Skybridge partnered with Count Financial for licensee services from c.1995 to 2008.
What is an equity partnership model?
An equity partnership model means Count Group takes an ownership stake in an accounting or financial advice firm rather than absorbing it outright. The firm continues to run its own business day to day.
At a much smaller scale, Count’s c.20% investment in Tailored Lifetime Solutions followed the same ownership logic, with the option to lift its shareholding over time.
For Skybridge, the company says alignment will come through governance arrangements, joint strategic initiatives and access to Count Group’s platform capabilities.
Skybridge is a converged firm, meaning it offers financial planning, accounting, taxation, SMSF administration and bookkeeping under one roof. Count Group identifies cross-referrals between these services as a pathway for organic growth.
Placement details and funding
The Placement involves approximately 15.9 million new fully paid ordinary shares at $1.57 per share. That is a 5.4% discount to the last closing price of $1.66 on 4 November 2026, and a 4.9% discount to the 5-day volume-weighted average price of $1.65.
The Placement is fully underwritten. The new shares will rank equally with existing Count shares. The issue is within the company’s existing placement capacity under ASX Listing Rule 7.1, so shareholder approval is not required.
The balance of the consideration will be funded from existing cash reserves, incremental debt capacity under existing facilities and the issuance of Count scrip. As at FY2027F year-end, pro forma net debt / underlying EBITA is expected to remain within Count Group’s acceptable debt metric range.
The Oracle Group acquisition earlier in 2026 was funded in a similar way, pairing an underwritten institutional placement with debt capacity and added 22 advisers to the employed network.
E&P Capital Pty Ltd is financial adviser, and E&P and Canaccord Genuity (Australia) Limited are joint lead managers and underwriters. Baker McKenzie is legal adviser.
Key dates for Count Group shareholders
The Placement bookbuild opened and closed on 5 November 2026. The remaining dates are:
- Thursday, 5 November 2026, 11am AEDT: investor and analyst briefing.
- Friday, 6 November 2026: Placement results announced, trading halt lifted and trading resumes.
- Wednesday, 11 November 2026: settlement of New Shares.
- Thursday, 12 November 2026: issue and commencement of trading of New Shares, and despatch of holding statements (indicative, subject to ASX confirmation).
- Q3 FY2027: completion of the acquisition expected, subject to conditions precedent including ACCC approval (or notification waiver).
- FY2028: Conditional Deferred Consideration and first earn-out payable, assuming completion occurs during FY2027.
- FY2029: second earn-out payable, on the same assumption.
Want the Next Financial Services Breakout in Your Inbox?
Join 20,000+ investors getting FREE breaking ASX news within minutes of release, complete with in-depth analysis and the full announcement. Click the “Free Alerts” button at Big News Blast to receive finance and wealth sector alerts the moment market-moving news breaks, ahead of the crowd.