
McPherson’s flags 11% first quarter sales decline and CEO exit at 2026 AGM
McPherson’s Limited (ASX: MCP) told shareholders at its 2026 AGM that first quarter FY27 sales were approximately 11% below the prior corresponding period, while confirming that Brett Charlton will step down as Chief Executive Officer and Managing Director. Charlton remains in the role, and this is his final AGM.
Management also retained its view that underlying EBITDA growth in FY27 “remains achievable”, with the full year result expected to be weighted to 2H27. The addresses were delivered by Chairman Ari Mervis and Charlton at the 11.00am (AEDT) meeting on 30 October 2026 at Level 8, 383 Kent Street, Sydney.
When big ASX news breaks, our subscribers know first
FY27 trading update: why the first quarter fell short
The prior corresponding period included increased stock orders by various wholesalers throughout the first quarter of 2026 in connection with the route-to-market transition. These increased stock orders repeated in December 2025, so they will be reflected in the comparison period for the first half 2027 result. That is relevant context for investors reading the 1H27 result.
The FY26 guidance downgrade in April had already pointed to sales tracking below expectations during the operating model transition, with supplier surcharges adding further pressure on earnings.
Brett Charlton, Chief Executive Officer and Managing Director
“Notwithstanding current trading, we believe underlying EBITDA growth in FY27 remains achievable, through deploying our new commercial model and with a continued focus on brands, customers and cost discipline.”
Charlton described brand performance during FY26 as follows:
- Swisspers: delivered a solid performance and maintained its leading position in its category.
- Manicare: continued to hold leadership positions across several categories despite challenging market conditions.
- Lady Jayne, Dr. LeWinn’s and Fusion Health: experienced greater disruption during the transition period, particularly in pharmacy.
FY26 results and balance sheet
Mervis described FY26 as “a disappointing result” and said the result was “clearly unsatisfactory”. He said the structural changes have not yet translated into the anticipated sales growth, earnings performance and shareholder returns.
The FY26 revenue decline of 14.9% to $118.3 million, alongside $20.7 million in non-cash intangible impairments, set the backdrop for the Board’s decision to withhold a dividend while the business works to rebuild earnings.
| Metric | FY26 | Context |
|---|---|---|
| Revenue from continuing operations | $118.3 million | n/a |
| Underlying EBITDA | $4.3 million | n/a |
| Statutory net loss after tax | $20.3 million | n/a |
| Net cash | $4.5 million | Compared with $8.8 million a year earlier; debt facilities undrawn |
The $4.3 million reduction in net cash reflects a deliberate decision to invest $5.5 million in working capital, predominantly inventory, to restore availability of core products. Excluding that investment, the business added approximately $1.2 million to net cash after capital expenditure, lease payments and the share buy-back.
The Board expects the inventory investment to unwind progressively through FY27 as stock levels normalise, releasing cash back to the balance sheet. It also commenced an on-market share buy-back, taking what it called a measured approach.
Given the retained loss position and FY26 financial performance, the Board did not determine to pay a dividend.
The new model delivered approximately $2.8 million of incremental EBITDA benefits and approximately $5.6 million of incremental EBIT benefits, both included in the FY26 result.
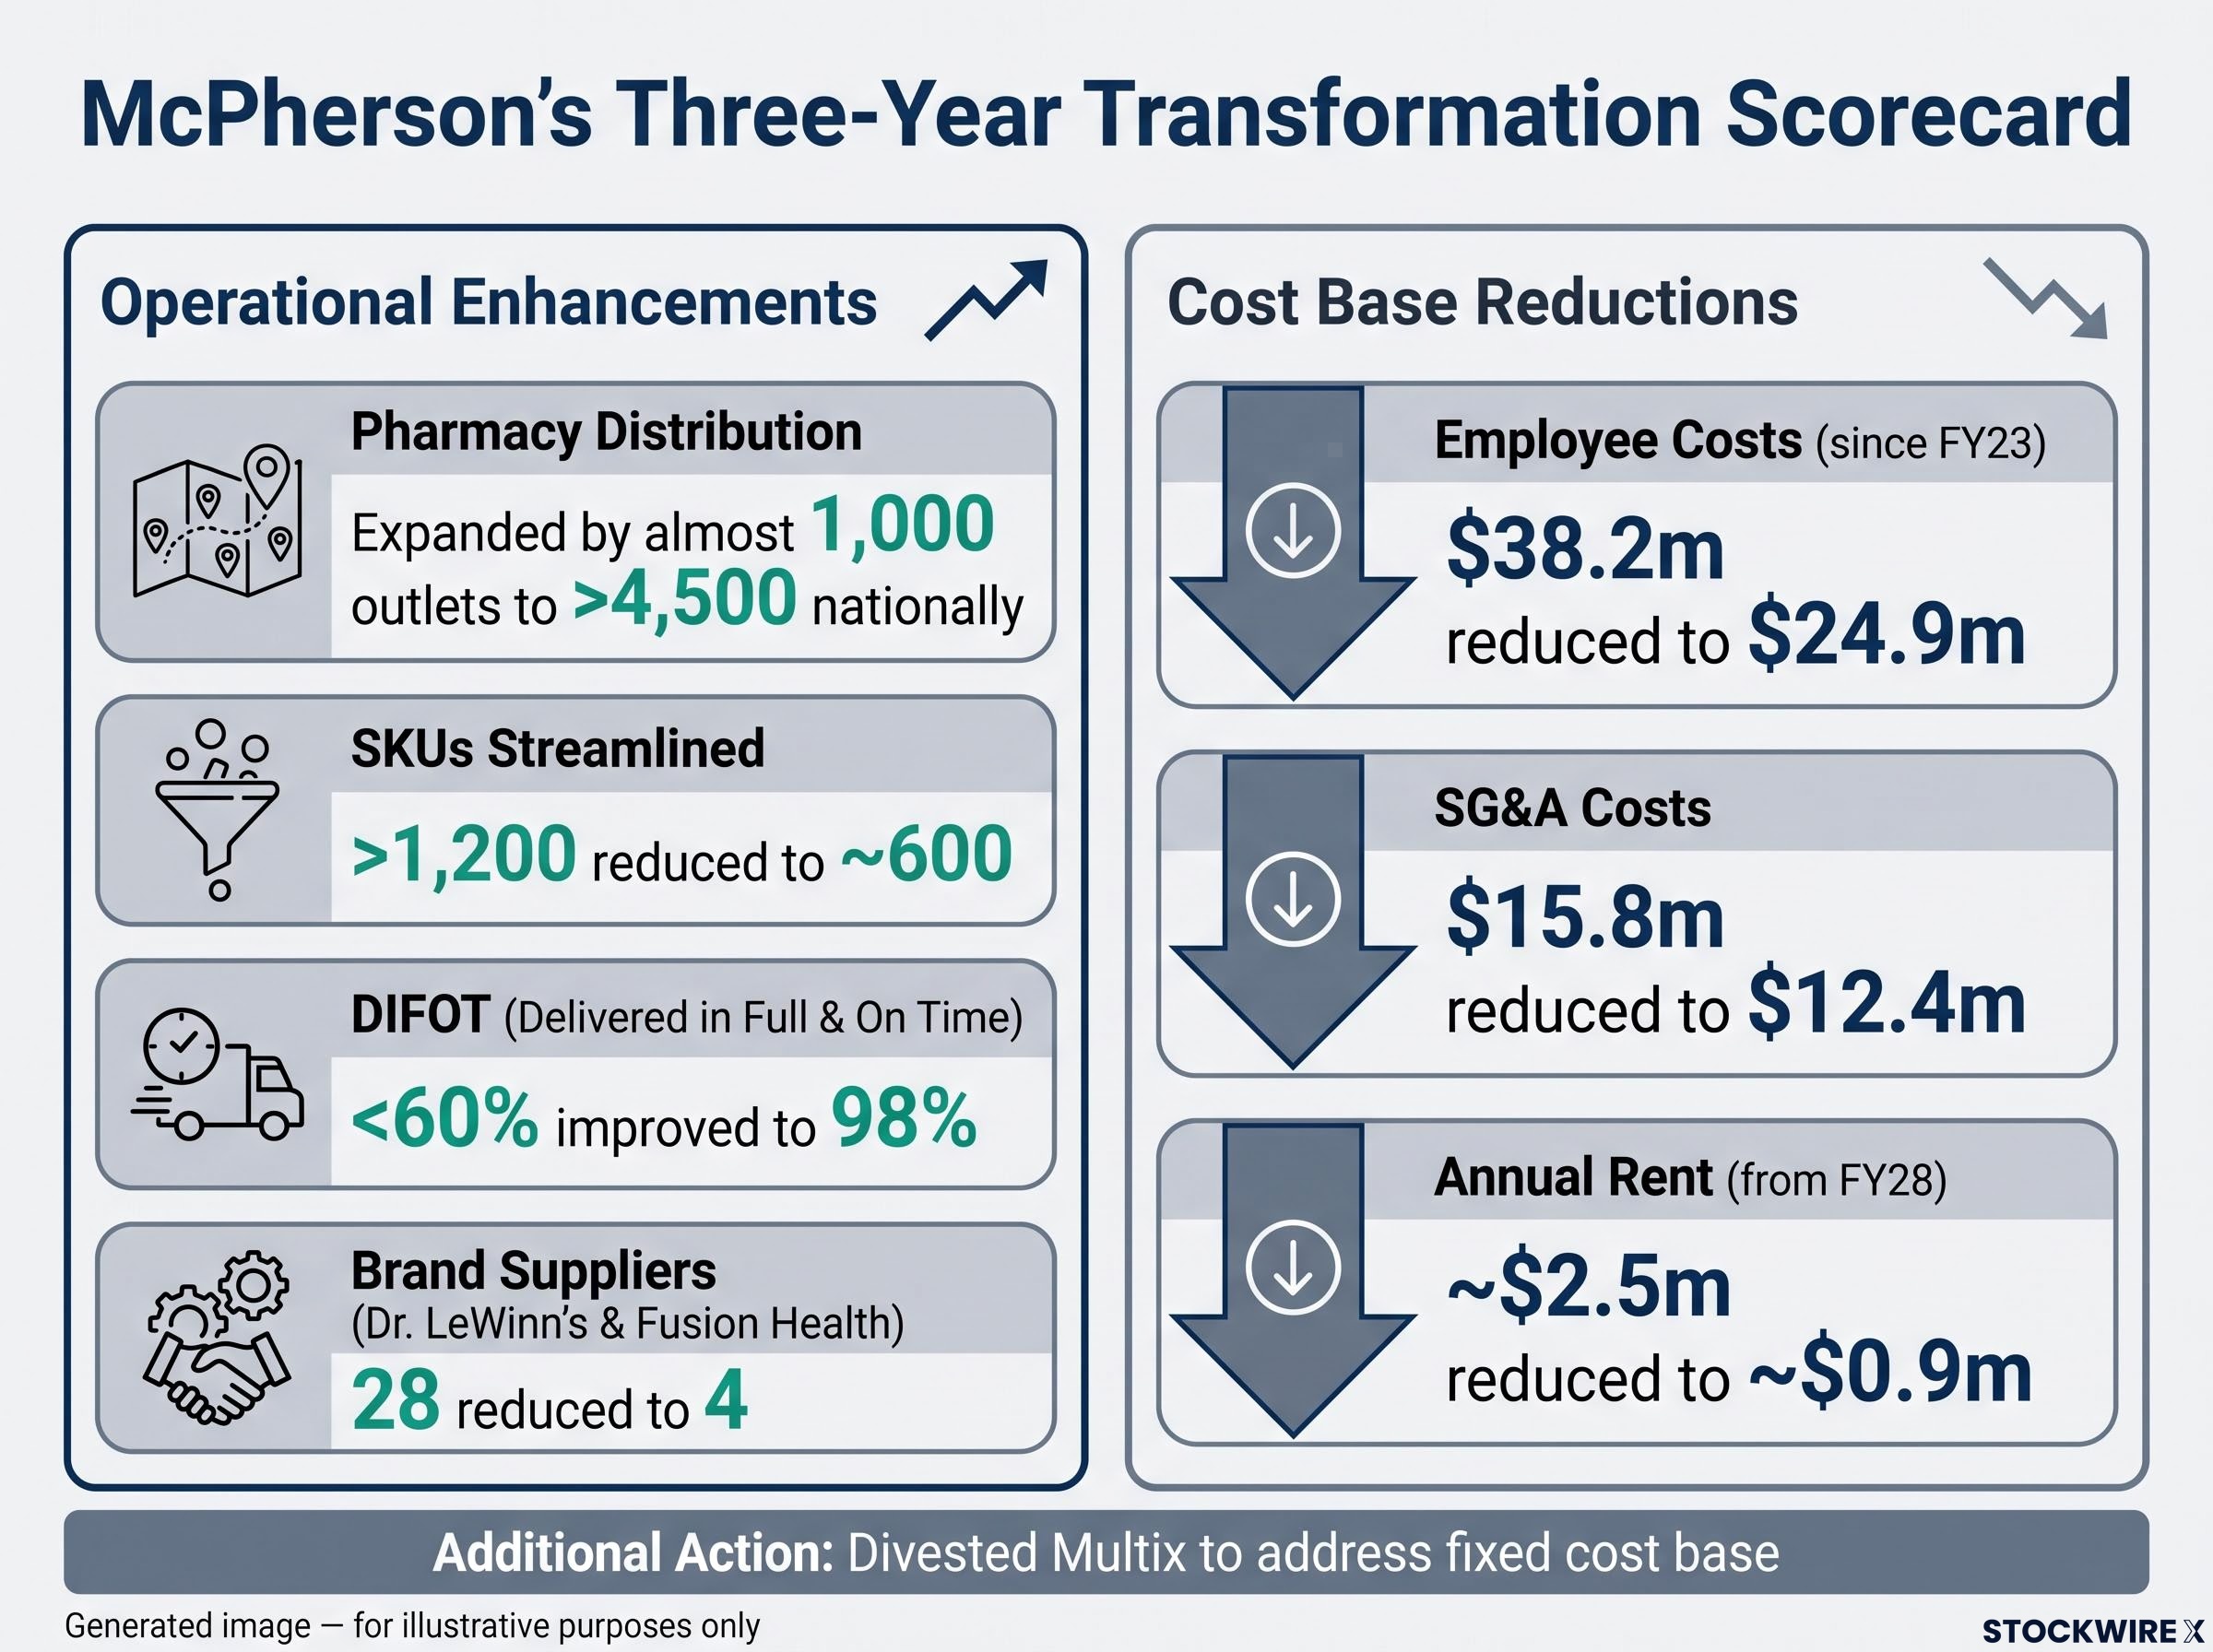
Three years of transformation: what has been rebuilt
A route-to-market model is how products reach shoppers, in this case through pharmacy wholesalers and third-party logistics providers. Ranging refers to which products pharmacies choose to stock, and it drives sales because cost savings only convert to earnings when products are stocked and available.
Charlton outlined the changes made over three years:
- Pharmacy distribution expanded by almost 1,000 outlets to more than 4,500 pharmacies nationally.
- SKUs streamlined from more than 1,200 to approximately 600.
- Suppliers for Dr. LeWinn’s and Fusion Health reduced from 28 to 4.
- DIFOT (Delivered in Full and On Time) increased from less than 60% to 98%.
- Employee costs reduced from $38.2 million to $24.9 million since FY23.
- Selling, General & Administration costs reduced from $15.8 million to $12.4 million.
- Annual rental costs falling from approximately $2.5 million to approximately $0.9 million from FY28, with the move to 383 Kent Street.
The company also divested Multix to address its fixed cost base and refinanced its debt facilities.
Leadership and Board priorities for FY27
Mervis said the major structural changes have now been implemented. The Board’s priorities for FY27 are:
- Overseeing the appointment of a new Chief Executive Officer to lead McPherson’s through its next phase.
- Continuing the Board’s renewal program, including the appointment of a new non-executive director following Alison Cook’s retirement.
- Supporting management as it executes the next phase of the strategy and works to restore growth and earnings momentum.
John Batistich, an independent non-executive director, stood for election at the AGM. Jane McKellar left the Board during FY26.
Ari Mervis, Chairman
“The next challenge is execution.”
The focus now shifts from structural change to converting it into sales and earnings.
What happens next for McPherson’s
- CEO appointment: the Board is to oversee the appointment of a new Chief Executive Officer, while Charlton remains in the role and supports an orderly transition.
- Non-executive director appointment: a new director is to be appointed following Alison Cook’s retirement, with the Board stating it will “shortly” farewell her.
- FY27 inventory unwind: the working capital investment is expected to unwind progressively through FY27.
- 1H27 result: the comparison period includes the December 2025 wholesaler stock orders.
- FY27 earnings weighting: management expects the full year result to be weighted to 2H27.
- Office move: annual rent of approximately $0.9 million from FY28 with the move to 383 Kent Street.
Don’t Miss the Next Consumer Staples Mover
Join 20,000+ investors getting FREE breaking ASX news within minutes of release, complete with in-depth analysis and the full announcement. Click the “Free Alerts” button at Big News Blast to receive real-time alerts the moment market-moving consumer news breaks, and stay ahead of the market.