
BNK Banking Corporation Q1 FY27 highlights: net interest income up 11% and margin widens year on year
In its Q1 FY27 trading update, BNK Banking Corporation recorded Net Interest Income of $6.25M, up 11% on Q1 FY26 and up 1.4% on Q4 FY26. The update was released on 29 October 2026.
Underlying (unaudited) NPAT came in at $315k, up 4% on Q1 FY26. Statutory (unaudited) NPAT was a loss of $59k, against a profit after tax of $75k in the prior corresponding period, which the company attributed to continued investment in technology.
| Metric | Q1 FY27 | Q1 FY26 | Change | Note |
|---|---|---|---|---|
| Underlying NPAT (unaudited) | $315k | n/a | Up 4% | On Q1 FY26 |
| Statutory NPAT (unaudited) | ($59k) loss | $75k profit | n/a | Reflects continued investment in technology |
| Net Interest Margin (NIM) | 1.92% | 1.83% | Up 9bps | Down 8bps from 2.00% in Q4 FY26 |
| Net Interest Income | $6.25M | $5.63M | Up 11% | Up 1.4% on Q4 FY26 |
Net Interest Margin of 1.92% was 9bps higher than the 1.83% recorded in Q1 FY26. It declined 8bps from the 2.00% achieved in Q4 FY26, which the company said was consistent with its commentary for the full year FY26 results.
BNK linked the rise in Net Interest Income to growth in its lending portfolio and a lift in its NCD program, which reached $52M across Q1 FY27. The company said this minimised funding reliance on market sensitive Term Deposits.
CEO commentary
Steve Kinsella, CEO
“The results for the quarter represent continued improvement in the base returns on the portfolio with cautious growth in our loan book.”
Kinsella also said:
“Our net margins are tracking in line with expectations, and we are confident that profitable growth opportunities continue to be available”.
When big ASX news breaks, our subscribers know first
Loan growth, funding and asset quality
Lending book
BNK reported a total lending book of $1.02bn, representing 2% growth in Q1 FY27 and 8% growth on the prior corresponding period. The commercial loan book grew 15% in Q1 FY27 to $284M.
Senior Secured lending rose 33% to $53M.
Funding and deposits
Total deposits stood at $1.08bn, supporting a deposit-to-loan ratio of 106%. The company described this ratio as strong.
Asset quality
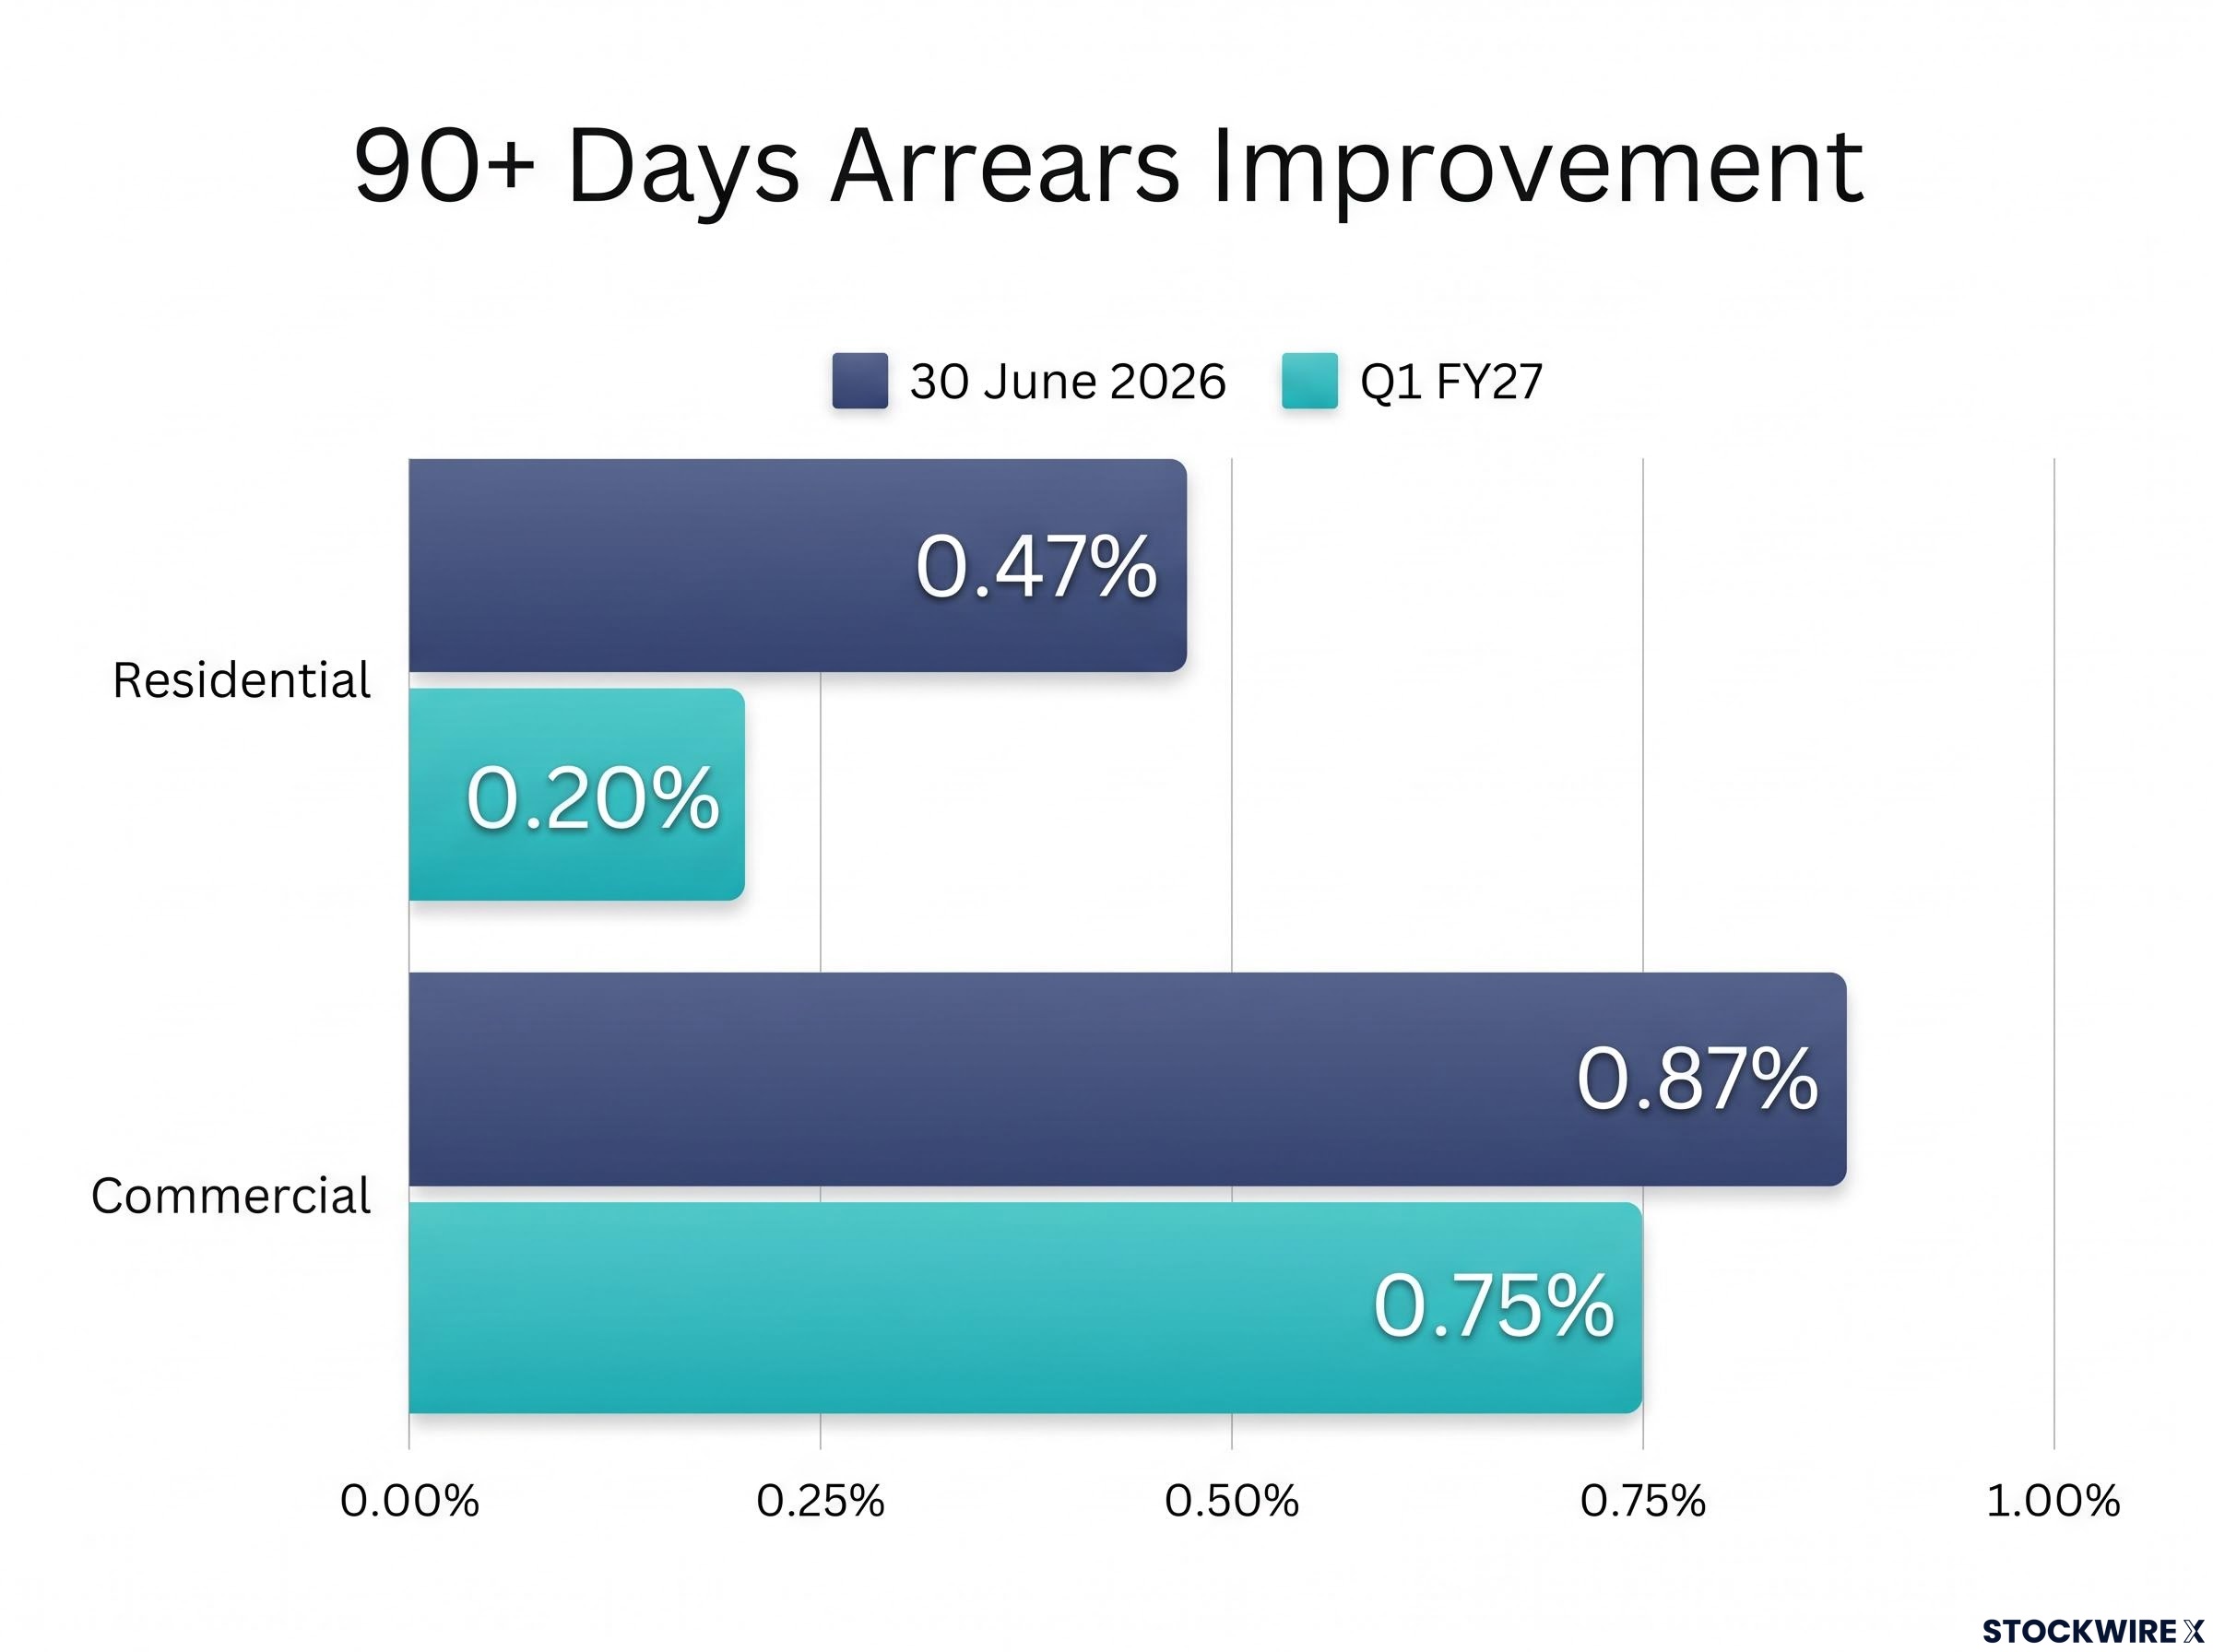
BNK said asset quality continued to strengthen from reductions achieved in Q4 FY26:
- 90+ days Residential arrears: 0.20%, down from 0.47% at 30 June 2026.
- 90+ days Commercial arrears: 0.75%, down from 0.87% at 30 June 2026.
Against a backdrop of elevated cost of living pressures, the company said these outcomes underscore the stability of its asset portfolio and the established early intervention frameworks.
Capital strength and what the Core Banking upgrade means for investors
BNK reported a Capital Adequacy Ratio (CAR) of 22.1%, after completing the redemption of $8.75M of Subordinated Tier 2 Notes in August 2026. The company said it maintained a strong CAR through Q1 FY27 while continuing to increase Commercial lending balances.
Net Tangible Assets (unaudited) per share remained stable at $0.99.
Why NIM and CAR matter
Net Interest Margin measures the spread between what a bank earns on its loans and what it pays to fund them. BNK’s 1.92% margin sits between its 1.83% a year earlier and 2.00% in the previous quarter.
BNK’s margin expansion strategy was already visible in the first half of FY26, when a shift toward commercial lending and senior secured investments lifted NIM to 1.88% and set the base for the quarterly margins now being reported.
Capital Adequacy Ratio compares a bank’s capital with its risk-weighted assets, acting as a buffer against losses. BNK’s CAR of 22.1% is the figure the company reported after the Tier 2 redemption.
Market conditions and strategy
Kinsella said market conditions remain competitive, with overall suppressed volumes, particularly in residential investment property, following increased interest rates and the Federal Budget changes in May 2026. Expectations of future rate rises also drove deposit competition and elevated rates.
The company remains focussed on three core areas of its strategy: improving customer experience, generating sustainable profitability and upgrading the Core Banking technology platform.
Phase 1 of the Core banking upgrade was achieved over the weekend of 17 and 18 October 2026. It involved a migration to a fully cloud based environment with minimal impact on customers.
What happens next for BNK’s Core Banking upgrade
The team is now focussed on Phase 2 of the Core banking upgrade, which Kinsella said will underpin and uplift BNK’s ability to provide a much-improved customer experience.
Stay Ahead on Banking and Finance News
Get FREE breaking ASX news from non-resource sectors delivered within minutes of release, complete with in-depth analysis. Join 20,000+ investors already receiving real-time alerts from Big News Blast. Click the “Free Alerts” button to see market-moving announcements the moment they land in your inbox.